Council Minutes - Section B: Reports - 14 May 2013
Contents | Previous Page: Section A - Procedural Matters | Next Page: Section C - Common Seal Register
Contents | Previous Page: Section A - Procedural Matters | Next Page: Section C - Common Seal Register
Reports tabled at the Ordinary Meeting of Council on Tuesday date held at City Hall, Little Malop Street in Geelong.
Portfolio: |
Finance - Cr S Kontelj |
Source: |
Corporate Services - Administration and Governance |
General Manager: |
Jeff Wall |
Index Reference: |
Budget Fin Yr 2013-2014 |
The proposed 2013-2014 Budget contains items in which Councillors have indicated they may have a conflict of interest.
The Local Government Act 1989 exempts a Councillor from a conflict of interest in circumstances when Council has previously approved the matter in which the Councillor has an interest, including funding, and the Councillor has disclosed the conflict of interest at the time the matter was approved by Council.
Any items proposed for inclusion in the Budget in which a Councillor has indicated a conflict of interest are proposed to be dealt with by separate resolution.
Once all declarations have been made and the items which are the subject of any declaration are determined upon by Council, all Councillors are able to vote on Agenda Item 2, being the Proposed 2013-2014 Budget.
Cr S Kontelj moved, Cr Harwood seconded -
That the Councillors who have a Conflict of Interest in items proposed for the inclusion in the 2013-2014 Budget declare the nature of that interest under the following categories:
General
Disbursements 2013-2014
Carried.
Victorian Local Governance Association (VLGA) Membership
Cr Farrell declared a Direct Interest in that she works as a contractor for the VLGA
Cr Farrell left the meeting room at 7:14pm
Cr Macdonald moved, Cr Richards seconded –
That funding of VLGA Annual Membership be approved for inclusion in the 2013-2014 Council Budget
Carried.
Cr Farrell returned to the meeting room at 7:14pm
Cr Heagney declared an Indirect Interest in that she is an employee of Alcoa.
Cr Heagney left the meeting room at 7:14 pm
Cr S Kontelj moved, Cr Richards seconded –
That a differential rate for Aluminium Production Land be set at 367% of the Residential Land Differential and be approved for inclusion in the 2013-2014 Council Budget.
Carried.
Cr Heagney returned to the meeting room at 7:15pm.
Disbursements 2013-2014
Geelong Harness Racing
Cr Richards declared an Indirect Interest in that he is President of the Geelong Harness Racing Board.
Cr Richards left the meeting room at 7:15 pm
Cr S Kontelj moved, Cr Macdonald seconded –
That funding of D11764 Geelong Harness Racing contribution of $10,000 be approved for inclusion in the 2013-2014 Council Budget.
Carried.
Cr Richards returned to the meeting room at 7:15pm.
In developing the 2013-2014 Budget an extensive range of activities and initiatives have been considered for funding. Councillors who may have a conflict of interest in any items to be considered are required to disclose the nature of any conflict of interest.
The Local Government Act 1989 requires a Councillor to declare any conflict of interest in relation to matters to be considered by Council and to leave the meeting for the duration of discussion and vote on that matter.
This report provides the opportunity for any disclosures of direct and indirect interest to be documented before consideration of the Budget. For items approved in previous budget and rolled over to 2013-2014, no further declaration is necessary.
A number of Councillors have indicated conflicts of interest in items contained within the proposed budget and to facilitate disclosure the following are suggested as categories for disclosure:
General - any item proposed for funding with the Budget but not specifically contained within a schedule to the Budget.
Disbursements 2013-2014 – any items within the Disbursements schedule to the Budget.
There are no environmental implications relative to this report.
Financial implications are addressed in the 2013-2014 Proposed Budget.
This report has been prepared to address requirements of the Local Government Act 1989, specifically section 79C(2) which deal with conflicts of interests in the Budget adoption process.
No officer involved in the preparation of this report has an interest relative to the advice provided.
The declaration of any interests ensures transparency.
Social considerations are addressed in the 2013-2014 Proposed Budget.
Council will advertise the Proposed Budget in local newspapers and take community response into account.
Portfolio: |
Finance - Cr S Kontelj |
Source: |
Corporate Services - Financial Services |
General Manager: |
Jeff Wall |
Index Reference: |
Financial Management/Reporting |
The Proposed 2013-2014 Budget has been prepared in accordance with the requirements of the Local Government Act 1989 (LGA) and the Best Practice Guidelines that were developed by a Local Government industry taskforce.
The Proposed Budget (Appendix 1) includes:
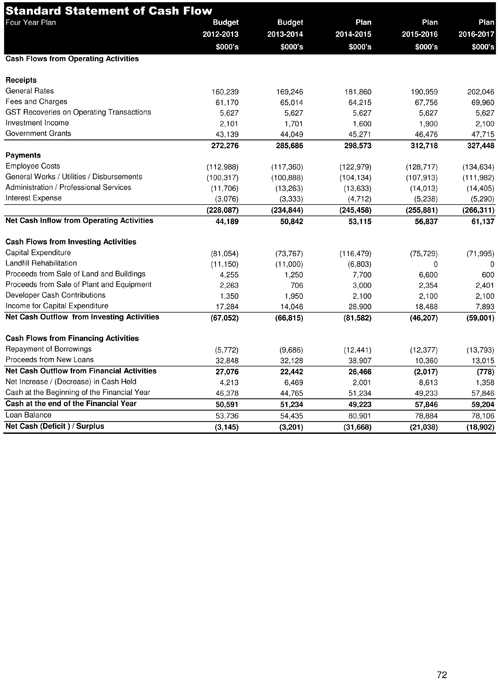
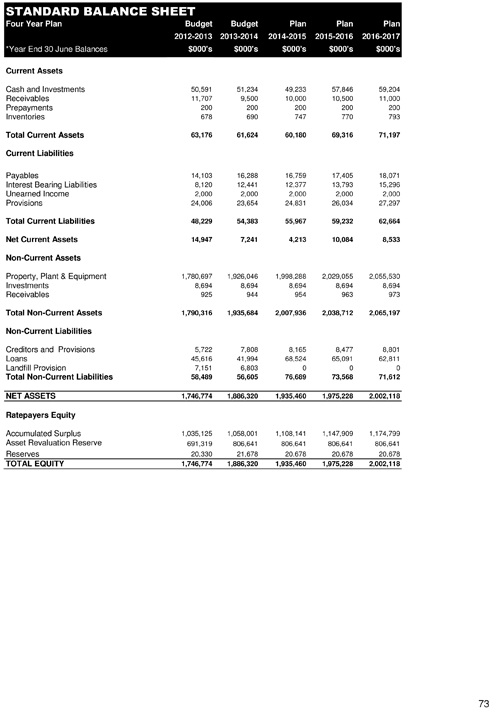
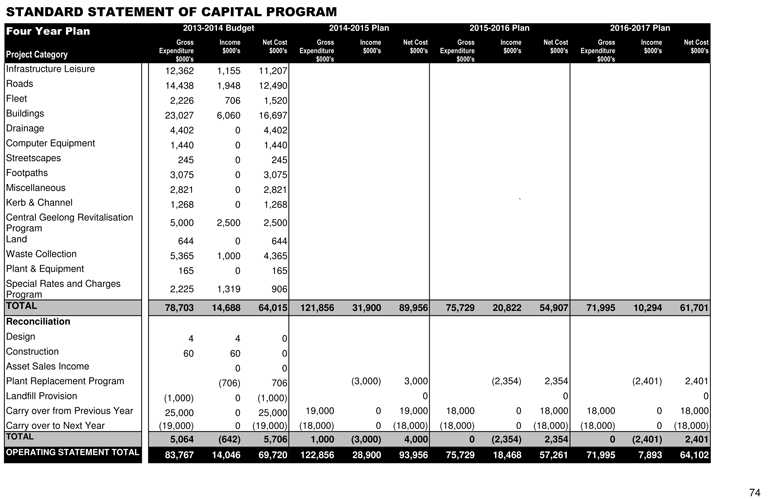
The Standard Statements of Income, Cash Flow, Balance Sheet and Capital Program.
The Key Strategic Activities to be undertaken during the financial year and performance targets and measures in relation to each Key Strategic Activity;
The relationship between the activities and initiatives in contributing to achieving the strategic objectives specified in the City Plan, and
Details of the activities and initiatives to be funded in the budget.
As required under the LGA a schedule declaring the differential rates and charges (Appendix 2) has been provided for public scrutiny and comment.
The Rating Strategy for 2013-2014 contains the Council Policy, Procedure, rate assistance and information on the City’s approach to the raising of property rates updated to reflect the outcome of Council’s budget deliberations.
Cr S Kontelj moved, Cr Harwood seconded -
That Council:
Pursuant to Section 127 of the LGA, the Council:
Receive and consider the Proposed 2013-2014 Budget document, (Appendix 1), which includes the Standard Statements of Income, Cash Flow, Balance Sheet and Capital.
Receive and consider the Four Year Strategic Resource Plan (Appendix 1, Section 3) including Standard Statements of Income, Cash Flow, Balance Sheet and Capital (under Section 126 of the LGA).
Receive and consider the Rates, Municipal Charge, Waste Collection & Recycling charge and other income (required to meet the appropriate financial requirements as proposed in the 2013-2014 Budget package).
Receive and consider the proposed declaration of Rates and Charges (Appendix 2), for the purpose of:
public scrutiny and comment, and
inclusion within the Rating Strategy 2013-2014 of Rate waivers under section 171of the LGA as detailed therein.
inclusion within the Rating Strategy 2013-2014 of Rate rebates, under section 169 of the LGA as detailed therein.
Receive and consider Councillor allowances in accordance with the notification published under section 73B of the LGA in the Victorian Government Gazette on 26 October 2012.
Advertise the Proposed Budget and make it available for inspection at Customer Service Centres and the Council website. The advertisement be placed in the Geelong Advertiser on Wednesday, 15 May, 2013 inviting written submissions from the public by 5pm on Tuesday, 11 June 2013.
Appoint a Budget Submissions Panel to hear submissions made in relation to the Budget, Differential Rating, and Councillor allowances, such Panel to:
consist of councillors each of whom shall have voting rights, with the quorum being three members;
meet on Friday, 14 June 2013 to consider any written submissions and to hear any person who wishes to address the Panel in support of a submission; and
report to Council in relation to the submissions that have been received and any recommended amendments to the Proposed Budget.
After considering the report of the Budget Submissions Panel, adopt the budget, declare the rates, and also adopt the Councillor allowance, the Deputy Mayor allowance and also the Mayoral allowance, at a Council Meeting to be held on Tuesday, 25 June 2013.
Advertise the adoption of the budget, declaration of the rates, and Councillor allowances, following the Council meeting on 25 June 2013.
Carried.
In accordance with Section 127 of the LGA, the City is required to prepare a budget for each financial year and must ensure that it contains:
The standard statements in the form and containing the matters required by the regulations;
A description of the activities and initiatives to be funded in the budget;
A statement as to how the activities and initiatives described under paragraph (b) will contribute to achieving the strategic objectives specified in the Council Plan;
Separately identified Key Strategic Activities to be undertaken during the financial year and performance targets and measures in relation to each Key Strategic Activity;
Any other details required by the regulations.
In addition, the City must ensure the budget considers the following:
The information the Council is required to declare under section 158(1);
If the Council intends to declare a differential rate under section 161, the details listed in section161(2), and
If the Council intends to declare a differential rate under section 161A, the details listed in section 161(2).
The Proposed 2013-2014 Budget for the financial year commencing 1 July 2013, as reviewed during recent Councillor Budget sessions, has been completed.
The Proposed 2013-2014 Budget document (Appendix 1) has been prepared on the basis of the Best Practice Guidelines as developed by a Local Government industry taskforce and issued to all municipalities across Victoria. The Proposed Budget document has been developed under the following sections:
Overview,
Budget Analysis,
Budget Strategies and
Appendices, including Activities and Initiatives linked with City Plan.
In accordance with the LGA, the Proposed 2013-2014 Budget also includes clear linkages to Council’s Proposed “City Plan 2013-2017”, and its supporting Key Strategies and Actions.
Specific inclusions in the Proposed Budget are a summary by Strategic Directions:
The activities and initiatives to be funded in the Budget.
How the activities and initiatives will contribute to achieving the strategic objectives, and,
The performance targets and measures in relation to each key strategic activity.
In addition, a component of the Proposed Budget is the setting of Rates and Charges. The Declaration of Rates and Charges for 2013-2014 is attached (Appendix 2). The formal Rating Strategy document will be updated that reflects Council’s statements of policy, procedure, general information and historical trends.
Council has declared a special rate in respect of the central business district of Geelong applicable to non-residential, non-exempt properties. The special rate is the Central Activities Area (CAA) Rate and is in addition to other rates and charges. The purpose of the special rate is to promote the CAA as a commercial shopping precinct using events, marketing and media.
Mayor and Councillor Allowances
The LGA regulates the allowance payable to the Mayor and Councillors of Local Governments in Victoria.
By notice in the Government Gazette published on 26 October 2012 the Minister for Local Government implemented an annual adjustment of allowances payable to Mayor, Deputy Mayor and Councillors effective from 27 October 2012. For the City of Greater Geelong the Mayoral Allowance is $177,570, the Deputy Mayoral Allowance is $55,591 and for Councillors $29,259. These allowances have been provided for in the 2013-2014 Budget.
Rating Strategy 2013-2014
The Rating Strategy document will be updated to reflect the outcome of Council’s Budget deliberations.
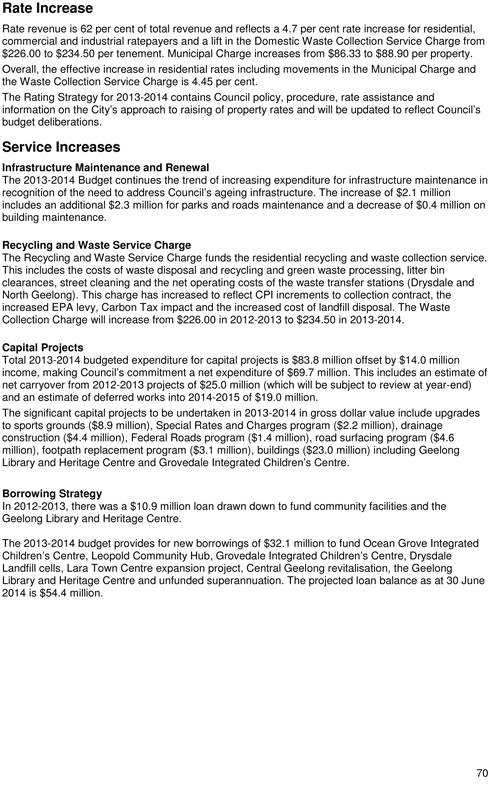
Rates and Charges are the major source of Council revenue accounting for 62% of the total Council revenue annually. An increase in rate income is required to meet the objectives of Council aspirations and community expectations for new infrastructure. The Strategic Resource Plan advocates sustainable rate increases over the next four years, required to fund new initiatives and maintain existing service levels.
Current Year Rate Increases
Changes proposed for 2013-2014 are:
Rates and charges on a residential property will increase overall by 4.45%, including rate in $ movement 4.7%, Municipal charge movement 3%, and Waste Collection Service Charge 3.8%. The residential rate has been set at $0.002665 per $ of CIV valuation.
Vacant Land rate in the dollar will increase to 140% of residential in order to encourage building activity and development.
The Local Government Legislation Amendment (Miscellaneous) Act 2012 imposes changes to Differential rating. The late licence differential is being discontinued in response to the Ministerial guidelines. The Commercial rate in $ will therefore increase by 7%.
Automobile, Petroleum and Aluminium differentials have been aligned to the same rate in the $. Councils objective is to reduce the gap between the rate in $ for these differentials and the Industrial differential. The Industrial rate increases by 7.7%.
The Waste Collection Service charge is calculated based on a fee for service, including direct, indirect and overhead costs. The charge is impacted by cost estimates of EPA levy $24.55 and Carbon Tax of $2.23 per tenement. The charge for 2013-2014 will increase from $226.00 to $234.50 or 3.8%.
The Municipal charge represents a fee on all rateable assessments as a contribution to the fixed and unavoidable costs of governance. The municipal charge is to increase from $86.33 to $88.90 or 3%.
The Farm rebate will remain at 36.2% with average rates increasing by 4.45% (as per residential). This rebate provides ongoing rate relief to farmers (33% rebate 2006-2007, 40% rebate 2007-2008, 45% 2008-2010, 45% for 2009-2010, 46.5% for 2010-2011, 46.5% for 2011-2012, 36.2% for 2012-2013). In 2013-2014 a 36.2% rebate represents a cost to Council of $1.384M.
The housing support rebate for eligible Charitable Housing will be replaced with a rates waiver for 2013-2014 and is available upon application.
The transitional rebate introduced in 2010-2011 for nominated charitable housing properties will remain at a 50% rebate in 2013-2014.
A rates waiver has been introduced for the New Corio Estate from 2013-2014 recognising this inappropriate subdivision and Planning Scheme Amendment C243.
The pensioner concession will increase from $198.00 in accordance with movement in CPI for Melbourne as advised by the Australian Bureau of Statistics to an estimated $202.00.
These increases are required in order to fund increases to recurrent expenditure, and the continuing capital works program.
Residential Rates and Charges
The average Capital Improved Value of residential properties within the municipality has increased from $363,800 to $365,610.
The total increase in rates and charges for the average property with a capital improved value of $365,610 is $55.24 or 4.45%. This increase is made up of $44.17 for General Rates, $2.57 for Municipal Charge and $8.50 for the Waste Collection service.
|
Residential Properties |
|
|
2012-2013 Rates on Average CIV $ |
2013-2014 Rates on Average |
Increase % |
|
General Rates CIV x Rate in $ |
|
|
930.11 |
974.28 |
4.75% |
|
Municipal Charge |
|
|
86.33 |
88.90 |
2.98% |
|
Waste Collection Service |
|
|
226.00 |
234.50 |
3.76% |
|
Total Rates and Charges |
|
|
1,242.44 |
1,297.68 |
4.45% |
Rate Waiver
Council declares a waiver under Section 171 of the LGA for residential land and farm land properties where the valuation of the assessment has increased between the 2010 valuation and the 2012 valuation by 50% or more and that increase is purely attributable to market factors, not attributable, in whole or in part, to improvements made to the assessment by the owner (or occupier). The amount of the waiver be set at:
between 25% and 49.99% of the general rates payable for the 2013-2014 financial year, increasing pro rata according to the valuation increase, for valuation increases between 50% and 59.99%; and
50% of the general rate payable for the 2013-2014 financial year for valuation increases of 60% or more.
The waiver is designed to mitigate the rates shock of a valuation increase and is only claimable once in a two year valuation cycle.
Council declare a Housing Support waiver under section 171 of the LGA of 100% of general rates and municipal charge for the following types of housing. Transitional, Emergency, Crisis Housing, Housing for Legatees or War Widows provided by the Geelong Legacy Club or provided by RSL, and supported Housing for disabled people. This waiver recognises that these properties provide specific needs within the community. Application can be made to Council to have land classified as being eligible for the waiver.
For 2013-2014 Council will declare a waiver under Section 171 of the LGA of 100% of General Rates and municipal charge, for privately owned properties within the inappropriate subdivision known as New Corio Estate. This rates assistance waiver recognises the financial burden associated with ownership of this land. Land within the New Corio Estate is zoned as farming land and the area has been determined to be an inappropriate subdivision due to the difficulty of providing utilities, drainage and distance from other residential areas. The Minister for Environment & Climate Change has approved a native vegetation plan for this land in support of natural temperate grassland of the Victorian Volcanic Plains. The waiver recognises the ongoing encumbrances on the land that prevents owners from making any demands on Council services now and into the future.
Council also provides a range of assistance measures to suit individual needs including pension rebates, farm rebates, rates deferral, and payment options such as regular Direct Debit, and Centrepay.
Rate Rebates
Council has declared a Farm rebate to support the continuation of broad acre farming at 36.2% of general rates.
For 2013-2014 Council declare a Transitional rebate under section 169 of the LGA of 50% of general rates and municipal charge. This rebate benefits the community by allowing a smooth transition from “exempt” to “rateable” status for these properties.
Rate Structure
Council has 13 rating or tariff groups with the application of differential rates to each of these groups in accordance with Section 161 of the LGA. The finalised Ministerial Guidelines for Differential Rating were gazetted on 26 April 2013 and will come into effect from 1 July 2013. The intention of the Guidelines is to provide clarity, consistency and transparency. Council needs to consider the objectives, the suitable uses and the types of classes of land when introducing a differential rate. The Guidelines establish three groups of types and classes of land categories for differential rates – those which are considered ‘appropriate’, those which must be ‘carefully considered’ by a council and those which would ‘not be appropriate’.
The Guidelines state that: “The use of a differential rate as a revenue instrument to raise funding for specific action to ameliorate the effects of problem gambling or late night venues is not an appropriate use of general rates which are intended for consolidated revenue and allocation via the Council budget process”.
The Late Licence differential rate will be discontinued from 2013-2014. The Late Licence differential rate was introduced in 2000-2001 in recognition of the cost associated with this activity. This differential rate is now seen as inappropriate. The properties that were categorised under this differential will now be categorised under the commercial differential rate to offset a reduction in revenue of $0.34M.
Fire Services Property Levy
The Fire Services Property Levy Act 2012 (FSPL) will come into effect from 1 July 2013 and will require Local Government to bill, receipt and collect a FSPL on rateable and non-rateable properties. It is estimated that Council will levy $23M for 2013-2014 and remit to the State Revenue Office.
The Act is in response to one of the recommendations of the Victorian Bushfires Royal Commission with the objective being to ensure that all property owners benefiting from Victoria’s Fire Services should make a contribution to the cost of the service compared with the existing insurance-based levy.
The new levy is designed to ensure that all property owners pay a fair contribution for fire services so that Victoria’s fire services continue to operate with sufficient resources. The new levy will be assessed on the Capital Improved Value (CIV) of property and is consistent with the valuation base used by most municipalities in levying rates. Since there will not be another revaluation cycle before 1 July 2013, a valuation of all non-rateable leviable properties has been undertaken to bring them into the valuation base so they can be levied.
The Levy will consist of a fixed component plus a variable component based on the property’s capital improved value. The fixed component will be $100 for residential properties and $200 for non-residential properties. The variable component will be a rate based on the land use classification code, known as the Australian Valuation Property Classification Code (AVPCC) for different property types (residential, commercial, industrial, primary production, public benefit, vacant) and will be determined by the Minister on or before 31 May each year. A $50 per property concession will apply to pensioner concession and Veterans Affairs gold card holders. The levy will contribute 77.5% of the annual funding requirements of the Country Fire Authority (CFA) with the State contributing the remaining 22.5%.
Council will also be required to apply the FSPL to all Council owned land and buildings. Land that is vested in, occupied or under the care, control or management of Council will only incur the fixed charge. This is property that is not operated for commercial purposes, but is available for public use such as halls and service club rooms, community and neighbourhood facilities and sports grounds.
Property that is currently assessed as non-rateable by Council will also be subject to the levy. A separate notice will be issued to non-rateable leviable land where no rate notice is currently issued.
The FSPL rates were released 2 May 2013. The City of Greater Geelong is in the CFA area only.
|
Land Use Classification for FSPL |
Fixed Charge |
Variable Charge per $ of CIV |
Council Differential |
|
Residential (including vacant residential land) |
$100.00 |
0.000115 |
Residential |
|
|
|
|
The Point Residential |
|
|
|
|
Vacant* |
|
|
|
|
The Point Vacant* |
|
Vacant (excluding vacant residential land) |
$200.00 |
0.000115 |
Vacant* |
|
|
|
|
The Point Vacant* |
|
Commercial |
$200.00 |
0.001092 |
Commercial |
|
|
|
|
Mixed Use |
|
|
|
|
The Point Commercial |
|
Industrial |
$200.00 |
0.001709 |
Industrial |
|
|
|
|
Automobile |
|
|
|
|
Petroleum |
|
|
|
|
Aluminium |
|
Primary Production |
$200.00 |
0.000312 |
Farm |
|
Public Benefit |
$200.00 |
0.000115 |
Cultural & Recreational |
*Vacant Land for Council rates are all under the Vacant Land Differential rate. |
|||
| For FSPL Vacant Land is split between Residential Land and other Vacant Land |
|||
The Proposed Budget identifies the sources and allocation of the resources to implement the many environmental initiatives that impact on the community as outlined with Council’s 2013-2017 City Plan.
The budget has been prepared in accordance with the direction provided by Council. Changes in rates, fees and charges have been structured to meet the financial requirements as proposed for the 2013-2014 financial year.
Expenditure includes the continuation of Council services to the community.
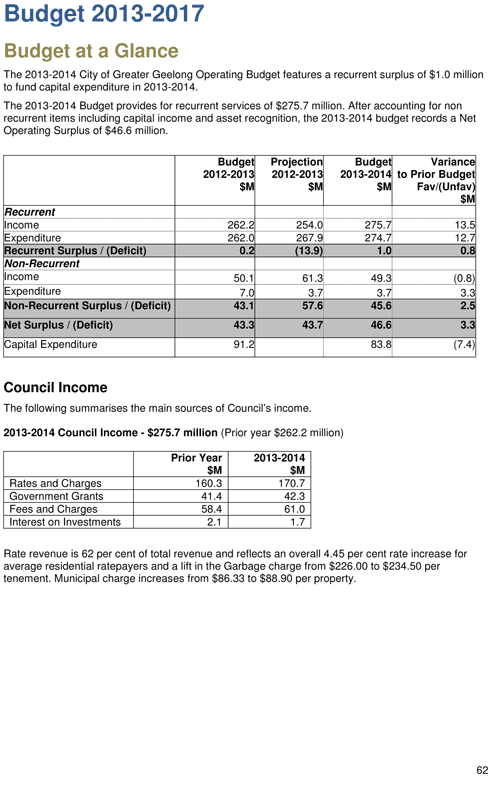
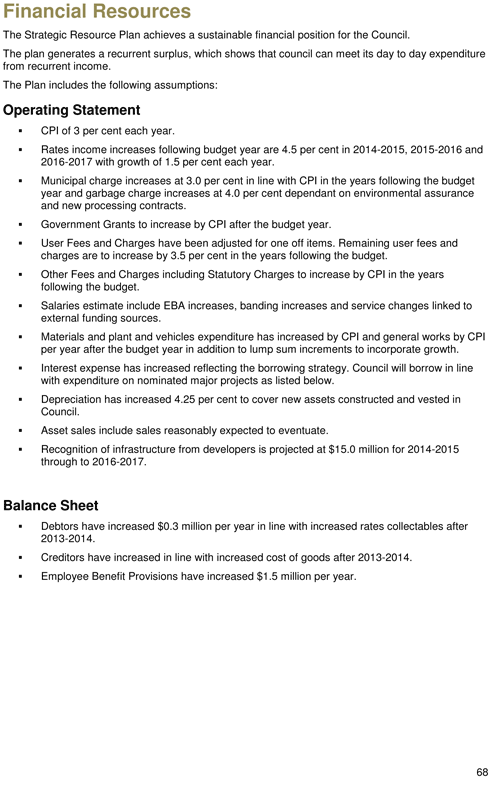
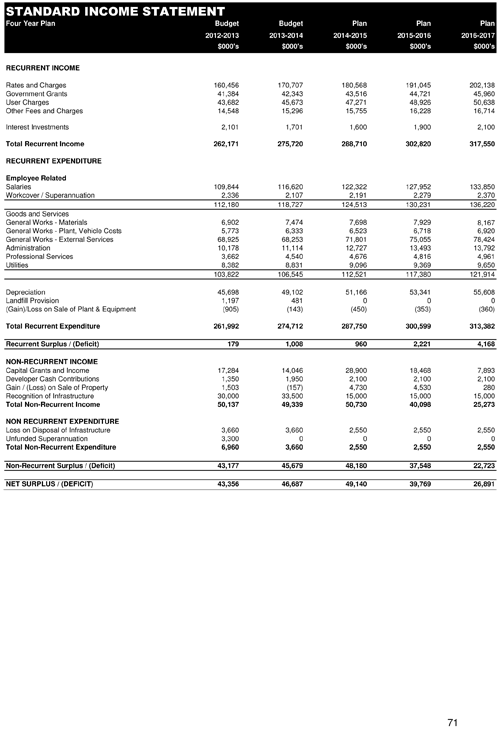
The Budget includes a recurrent operating surplus of $1.0M.
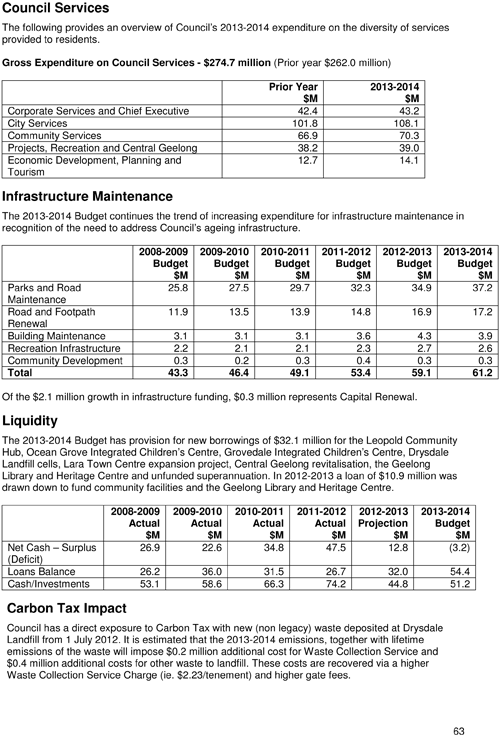
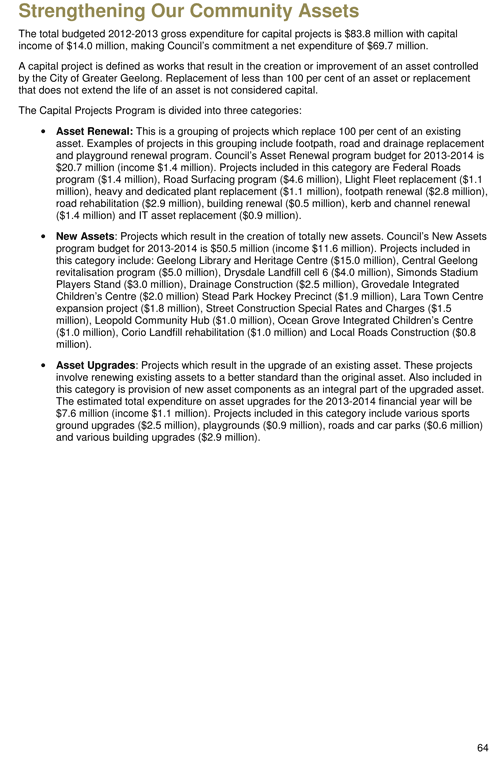
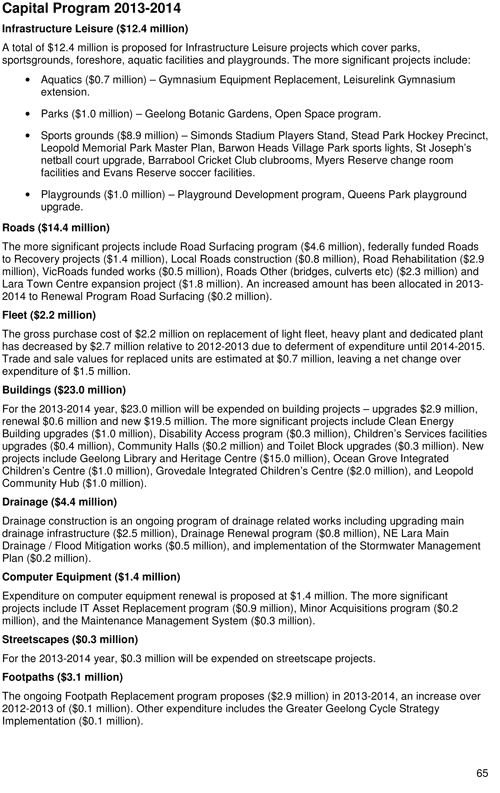
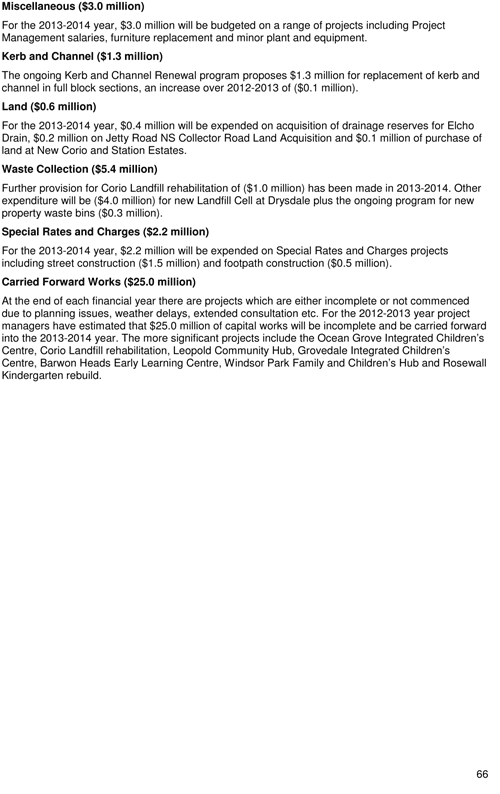
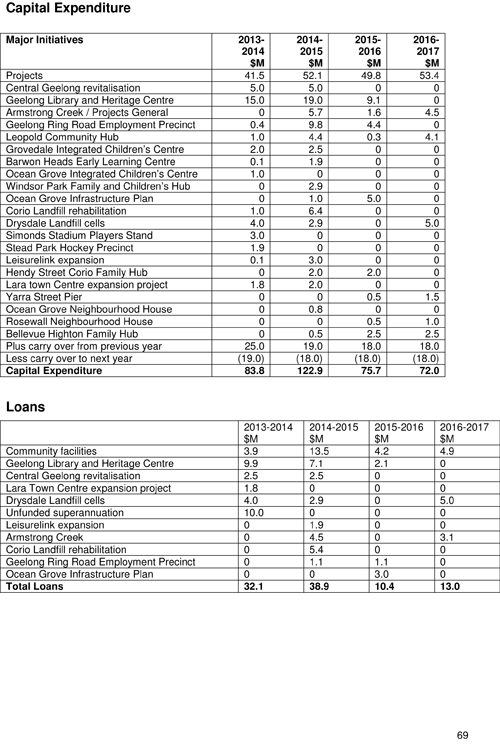
The gross capital expenditure of $83.7M includes new funding of $12.3M on Infrastructure leisure, $23.2M on roads, footpaths, kerb & channel and drains and $23.0M on buildings.
New loans of $32.13M are proposed for 2013-2014 The projected total amount of borrowings as at 30 June 2014 is $54.4M.
The timetable is compliant with the provisions of the LGA, which deals with the preparation and adoption of budgets.
The timetable also recognises the need to align the Annual Budget to the direction and allocation of resources identified within the proposed City Plan.
No Council officers involved in the preparation of this report have a direct or indirect interest in any matter to which this report relates.
Although not required to adopt the Annual Budget until August there are adverse implications if the process is delayed. These include:
A lack of internal control to monitor the financial position of the City into the new financial year.
Delays in commencing (and therefore completion) of projects identified within the Annual Budget.
Delaying the issuing of the first rate instalment notices (due in early September) and possible breach of the LGA.
The Proposed Budget identifies the sources and allocation of resources to implement the many social initiatives that impact on the community as outlined with Council’s 2013–2017 City Plan.
A Public Notice is scheduled to be published in the Geelong Advertiser on Wednesday, 15 May 2013 advising that the Proposed 2013-2014 Budget will be available for public scrutiny and inviting written submissions to be made.
Following the closing date for the written submissions, it is proposed to convene a Budget Submissions Panel on Friday, 14 June 2013 to review any submissions that have been received and put forward to Council a report on any recommended amendments to the Proposed Budget.
Council is scheduled to meet on Tuesday, 25 June 2013 at which time the report from the Budget Submissions Panel will be considered.
Public Notice of the adopted budget and declaration of rates and charges will be advertised following the Council Meeting.
Amount Intended to be raised by General Rates, Municipal Charge, and Annual Service Charge for the period 1 July 2013 - 30 June 2014.
An amount of $169,030,764 be declared as the amount which Council intends to raise by General Rates, Municipal Charge and the Annual Service Charge, which amount is calculated as follows:
General Rates $136,099,978
Municipal Charge $9,808,148; and
Annual Service Charge $23,122,638.
General Rates
2.1 A general rate be declared for the period 1 July 2013 to 30 June 2014.
2.2 It be further declared that the general rate be raised by the application of differential rates.
2.3 A differential rate be respectively declared for rateable land having the respective characteristics specified below, which characteristics will form the criteria for each differential rate so declared.
2.3.1. Farm Land – means any land which:
is not less than 2 hectares in area; and
is used predominantly for the business of grazing (including agistment), dairying, pig-farming, poultry farming, fish farming, tree farming, bee-keeping, viticulture, horticulture, fruit growing or the growing of crops of any kind or for any combination of those activities; or
satisfies the criteria for municipal purpose benefit for large holdings to the extent that it is, for example, land that is predominantly used and maintained for heritage, cultural or environmental purposes, or land that is held as natural bushland under a trust for nature covenant, or land that is held under some other type of similar formal undertaking.
To avoid doubt, 'business' for the purposes of identifying Farm Land has the same meaning as that given to it by section 2(1) of the Valuation of Land Act 1960 for the same purpose, being a business that:
has a significant and substantial commercial purpose or character; and
seeks to make a profit on a continuous or repetitive basis form its activities on the land; and
is making a profit from its activities on the land, or that has a reasonable prospect of making a profit from its activities on the land if it continues to operate in the way that it is operating.
2.3.2 Residential Land - means any land:
that is used exclusively for residential purposes; or
on which a habitable building is erected, which building is unoccupied, and which is zoned residential under the Greater Geelong Planning Scheme.
2.3.3 Vacant Land - means any land:
that does not have the characteristics of Farm Land; and
on which no building is erected, save for any uninhabitable shed or shelter, the size of which does not exceed 5% of the total area of the land.
2.3.4 Petroleum Production Land – means any land that is:
used primarily for the production or conveyance of petroleum and/or petroleum by-products; and
is described as such in Schedule A.
2.3.5 Industrial Land – means any land that:
does not have the characteristics of
Vacant Land; or
Commercial Land; or
Petroleum Production Land; or
Aluminium Production Land; or
Automobile Manufacture Land; and
is used predominately for industrial purposes, which includes manufacturing, repairing, servicing, processing and reprocessing.
2.3.6 Commercial Land – means any land that:
does not have the characteristics of:
Farm Land; or
Industrial Land; or
Petroleum Production Land; or
Aluminium Production Land, or
Automobile Manufacture Land; and
is used predominately for the sale of goods or services or other commercial purposes; or
on which a habitable building is erected, which building is unoccupied, and which is zoned other than residential under the Greater Geelong Planning Scheme.
2.3.7 Aluminium Production Land - means any land that is:
used primarily for the manufacture or production of aluminium or aluminium products and
is described as such in Schedule A.
2.3.8 Automobile Manufacture Land – means any land that is:
used primarily for the manufacture of automobiles or automobile products; and
is described as such in Schedule A.
2.3.9 Mixed Use Land – means any land that:
has the characteristics of Residential Land combined with the characteristics of Commercial Land or Industrial Land; and
is used partly for residential purposes and partly for commercial and/or industrial purposes.
2.3.10 The Point – Residential Land - means any land that:
is used exclusively for residential purposes; or
on which a habitable building is erected, which building is unoccupied, and which is zoned residential under the Greater Geelong Planning Scheme; and
is described as such in Schedule A.
2.3.11 The Point – Vacant Land - means any land:
that does not have the characteristics of Farm Land; and
on which no building is erected save for any small uninhabitable storage shed or shelter, the size of which does not exceed 5% of the total land area; and
is described as such in Schedule A.
2.3.12 The Point – Commercial Land - means any land that:
does not have the characteristics of:
Farm Land; or
Industrial Land; and
is used predominantly for the sale of goods or services, or other commercial purposes; or
on which a habitable building is erected, which building is unoccupied, and which is zoned other than residential under the Greater Geelong Planning Scheme; and
is described as such in Schedule A.
2.4 A rate pursuant to the Cultural and Recreational Lands Act 1963 be declared for rateable land having the respective characteristics specified below.
2.4.1 Cultural and Recreational Land -
Any land which -
has the characteristics of Recreational land as defined by the Cultural and Recreational Lands Act 1963; and
is described as such in Schedule A .
2.5 Each differential rate and Cultural and Recreation Lands Rate will be determined by multiplying the Capital Improved Value of each rateable land (categorised by the characteristics described in paragraph 2.3 and 2.4 by the relevant percentages indicated in the following table:
CATEGORY %
Farm Land .002665 (or .2665 percent of Capital Improved Value).
A rebate of 36.2% of the CIV by rate in dollar in accordance with Council policy for farm rating.
Residential Land .002665 (or .2665 percent of Capital Improved Value)
Vacant Land .003731 (or .3731 percent of Capital Improved Value)
The Point Residential Land .002665 (or .2665 percent of Capital Improved Value)
The Point Vacant Land .003731 (or .3731 percent of Capital Improved Value)
The Point Commercial Land .005437 (or .5437 percent of Capital Improved Value)
Petroleum Production Land .009782 (or .9782 percent of Capital Improved Value)
Industrial Land .007252 (or .7252 percent of Capital Improved Value)
Commercial Land .005437 (or .5437 percent of Capital Improved Value)
Aluminium - Manufacture Land .009782 (or .9782 percent of Capital Improved Value)
Automobile - Production Land .009782 (or.9782 percent of Capital Improved Value)
Mixed Use Land .003966 (or .3966 percent of Capital Improved Value)
Cultural and Recreational .001685 (or .1685 percent of Capital Improved Value).
2.6 It be recorded that Council considers that each differential rate will contribute to the equitable and efficient carrying out of Council functions; and that
2.6.1 the respective objectives of each differential rate be those specified in Schedule B;
2.6.2 the respective types or classes of land which are subject to each differential rate be those defined in Schedule B;
2.6.3 the respective uses and levels of each differential rate in relation to those respective types or classes of land be those described in Schedule B; and
2.6.4 the relevant
uses of; and
geographical locations of; and
planning scheme zonings of; and
types of buildings on the respective types or classes of land be those identified in Schedule B; and
2.7 It be confirmed that no amount is fixed as the minimum amount payable by way of general rate in respect of each rateable land within the municipal district.
Rebates
3.1 Farm Rebate
For 2013-2014 Council declare a rebate under section 169 of the LGA of 36.2% for all land classified and rated as farm land. Properties defined as farms will be entitled to a rebate recognising that there is a benefit to the community in encouraging the retention of large lot primary producing holdings. An application can be made to Council to have land classified as Farm land.
3.2 Transitional Rebate
For 2013-2014 Council declare a rebate under section 169 of the LGA of 50% of general rates and municipal charge for the following listed properties. This rebate benefits the community by allowing a smooth transition from “exempt” to “rateable” status for these properties. It had been Councils intention to continue the transition process and reduce the rebate, but with the introduction of the Fire Services Property Levy, these properties will be leviable. This will represent an additional impost to these ratepayers and therefore the rebate will be remain at 50% for 2013-2014.
Properties having the benefit of the Transitional Rebate for 2013-2014:
|
Owners |
Location |
||||||
|
Housing Associations |
|
||||||
|
Winteringham Housing Association / Alexander Miller Homes |
|
||||||
|
Housing Choices Australia (previously known as Melbourne Affordable Housing Association) |
|
||||||
|
|
31A Noble Street, Newtown |
||||||
|
Retirement Villages |
|
||||||
|
St Laurence Community Services Inc. |
|
||||||
|
Uniting Care |
|
||||||
|
Multicultural Aged Care Services Geelong Inc. |
16 De Stefano Drive, North Geelong |
||||||
|
Other Non Rated Properties to be Rateable |
|
||||||
|
Melbourne Anglican Trust Corporation |
110 West Fyans Street, Newtown |
Waivers
4.1 Rates Assistance Waivers
Council declares a waiver of general rates under Section 171 of the LGA for the class of persons comprised of ratepayers in respect of assessments which are categorised as Residential Land or Farm Land where the valuation of the assessment has increased, between the 2010 valuation and the 2012 valuation, by 50% or more and that increase is purely attributable to market factors, not attributable, in whole or in part, to improvements made to the assessment by the owner (or occupier). The amount of the waiver is set at:
4.1.1 between 25% and 49.99% of the general rates payable for the 2013-2014 financial year, increasing pro rata according to the valuation increase, for valuation increases between 50% and 59.99%; and
4.1.2 50% of the general rates payable for the 2013-2014 financial year for valuation increases of 60% or more.
The waiver is designed to mitigate the rates shock of a valuation increase and can only be claimed in respect of an assessment once in a two year valuation cycle.
4.2 Council declares a Housing Support waiver of 100% of general rates and municipal charge under section 171 of the LGA for the class of persons comprised of ratepayers in respect of assessments which contain the following types of housing:
4.2.1 transitional, emergency or crisis housing;
4.2.2 housing for Legatees or War Widows, provided by the Geelong Legacy Club or provided by RSL; and
4.2.3 supported housing for disabled people.
This waiver recognises that these properties provide for specific needs within the community. Application can be made to Council to have land classified as being eligible for the waiver.
4.3 New Corio Estate (Inappropriate Subdivision)
For 2013-2014 financial year, Council declares a waiver of 100% of general rates and municipal charge under Section 171 of the LGA for the class of persons comprised of ratepayers in respect of assessments which are in private ownership within the inappropriate subdivision known as New Corio Estate. This rates assistance waiver recognises the financial burden associated with ownership of this land. Land within the New Corio Estate is zoned as farming land and the area has been determined to be an inappropriate subdivision due to the difficulty of providing utilities and drainage and due to its distance from other residential areas. The Minister for Environment & Climate Change has approved a native vegetation plan for this land in support of natural temperate grassland of the Victorian Volcanic Plains. The waiver recognises the ongoing encumbrances on the land that prevent owners from making any demands on Council services now and into the future.
Municipal Charge
5.1 An annual municipal charge be declared for the period commencing 1 July 2013 to 30 June 2014.
5.2 The purpose of the municipal charge is to recover some of the administrative costs of the Council.
5.3 The charge be the sum of $88.90 for each rateable property in the municipality.
5.4 Applications for exemption for farm land in accordance with section 159 of the LGA, is to be made within two months from the date of issue of annual rate notice.
Annual Service Charge
6.1 An Annual Service Charge be declared for the period commencing 1 July 2013 to 30 June 2014.
6.2 The Annual Service Charge be declared for the collection and disposal of refuse.
6.3 The Annual Service Charge be $234.50 for each rateable land and non-rateable land (or part) in respect of which the Annual Service Charge may be levied.
6.4 The criteria specified below, be the criteria, which form the basis of the Annual Service Charge, so declared:
Geographic existence within those areas of the municipal district in which Council provides a domestic refuse collection and disposal service. The charge will be raised irrespective of whether the service is used or not.
Central Activities Area Rate
Council has declared a special rate in respect of the central business district of Geelong applicable to non-residential, non-exempt properties. The special rate is the Central Activities Area (CAA) Rate and is in addition to other rates and charges. The purpose of the special rate is to promote the CAA as a commercial shopping precinct using events, marketing and media.
For 2013-2014 the rate will raise $736,000 ($671,000 in 2012-2013). The rate in dollar for 2013-2014 is set at $0.0005716 and $0.0001771 for Cultural & Recreation (Cultural and Recreation properties are charged a reduced CAA rate, in accordance with the ratio of the recreation rate to the commercial rate).
Incentives
No incentives be declared as the incentives to be given by Council for the payment of General Rates, Municipal Charge and the Annual Service Charge (described earlier in this document) before the dates fixed for their payment under Section 167 of the LGA.
Consequential
8.1 Notwithstanding anything said in any earlier Resolution of Council, the Geelong Advertiser and the Geelong Independent be chosen, as the newspapers in which the public notice will appear.
8.2 The Responsible Officer of Council be authorised to levy and recover the General Rates, Municipal Charge and the Annual Service Charge described earlier in accordance with the LGA.
Interest
Interest on unpaid rates and charges will be charged in accordance with Section 172 of the LGA. Interest will be charged at the penalty interest rate. In proven cases of hardship where Council allows rates to be deferred, interest will be charged at 6.57% for 2013-2014.
All that land generally bounded more or less by Princes Highway, Shell Parade, Corio Bay Foreshore, Wharf Road, Station Road and neighbouring land.
All that land generally bounded more or less by Point Henry Road, Corio Bay Foreshore and Stoddart Lane.
(a) All that land generally bounded more or less by Cowies Creek, Melbourne Road, North Shore Road and Geelong – Melbourne Railway, excluding the land known as 60-80 North Shore Road being the Ford Research and Development Facility.
(b) All that land generally bounded more or less by Sea Beach Parade, St Georges Road, Geelong-Melbourne Railway and neighbouring southern land.
All the residential land formerly described in Certificate of Title Volume 09901 Folio 324 and also described in Lot B LP 214468.
All the vacant land formerly described in Certificate of Title Volume 09901 Folio 324 and also described in Lot B LP 214468.
All the commercial land formerly described in Certificate of Title Volume 09901 Folio 324 and also described in Lot B LP 214468.
Any land reserved under the Cultural and Recreational Lands Act 1963 including:
|
Ratepayer Name |
Property Address |
|
Bareena Bowling Club Incorporated |
89 Noble Street, Newtown VIC 3220 |
|
Drumcondra Bowling Club |
9 Glenleith Court, Geelong VIC 3220 |
|
Geelong Race Course Trustees |
99 Breakwater Road, Breakwater VIC 3219 |
|
Geelong Agricultural & Pastoral Society |
79 Breakwater Road, Breakwater VIC 3219 |
|
Royal Geelong Yacht Club |
25 Eastern Beach Road, Geelong VIC 3220 |
|
Eastern Park Bowling Club Inc |
51-55 Garden Street, East Geelong VIC 3219 |
|
Geelong Football Club Incorporated |
360-380 Moorabool Street, South Geelong VIC 3220 |
|
East Geelong Golf Club |
Eastern Park Circuit, East Geelong VIC 3219 |
|
Highton Bowling Club Inc |
204 Roslyn Road, Highton VIC 3216 |
|
Barwon Heads Golf Club Incorporated |
Golf Links Road, Barwon Heads VIC 3227 |
|
Belmont Bowling Club Incorporated |
16-36 Reynolds Road, Belmont VIC 3216 |
|
Geelong Lawn Tennis Club Incorporated |
12-20 Sommers Street, Belmont VIC 3216 |
|
Geelong Bowls Club Incorporated |
4-10 Sommers Street, Belmont VIC 3216 |
|
Beckley Park Committee of Management Inc |
40 Broderick Road, Corio VIC 3214 |
|
Bell Park Sport & Rec Club Inc |
68 Calvert Street, Hamlyn Heights VIC 3215 |
|
St Leonards Golf Club Inc |
79-175 Harvey Road, St Leonards VIC 3223 |
|
Clifton Springs Golf Club Incorporated |
86-88 Clear Water Drive, Clifton Springs VIC 3222 |
|
Clifton Springs Bowling Club |
Clifton Street, Clifton Springs VIC 3222 |
|
Drysdale Bowling & Croquet Club inc |
19-29 Collins Street, Drysdale VIC 3222 |
|
Lonsdale Golf Club |
31-69 Fellows Road, Point Lonsdale VIC 3225 |
|
Portarlington Bowls Club Incorporated |
Harding Street, Portarlington VIC 3223 |
|
Portarlington Golf Club |
92-160 Hood Road, Portarlington VIC 3223 |
|
Leopold Sportsmans Club Inc |
131-139 Kensington Road, Leopold VIC 3224 |
|
Ocean Grove Bowling Club |
16-24 The Terrace, Ocean Grove VIC 3226 |
|
St Leonards Bowling Club |
1274 Murradoc Road, St Leonards VIC 3223 |
|
Curlewis Golf Club Incorporated |
1201-1419 Portarlington Road, Curlewis VIC 3222 |
|
Australian Croatian Sporting Centre |
15 Gibbons Road, Lara VIC 3212 |
|
Bell Park Sports Club Inc |
515 Ballarat Road, Batesford VIC 3221 |
|
Geelong West Bowling Club Incorporated |
12 Bowlers Avenue, Geelong West VIC 3218 |
|
Barwon Rowing Club Inc |
2 Barwon Terrace, South Geelong VIC 3220 |
|
Geelong Grammar School Rowing Club |
6 Barwon Terrace, South Geelong VIC 3220 |
|
Geelong Rowing Association |
8 Barwon Terrace, South Geelong VIC 3220 |
|
Corio Bay Rowing Club |
10 Barwon Terrace, South Geelong VIC 3220 |
|
East Geelong Uniting Church Tennis Club Inc |
39 Denman Street, East Geelong VIC 3219 |
|
East Geelong Recreation Reserve Committee |
137-139 McKillop Street, Geelong VIC 3220 |
|
Portarlington Sailing Club |
219 Point Richards Road, Portarlington VIC 3223 |
|
Indented Head Boat Club |
The Esplanade, Indented Head VIC 3223 |
|
Indented Head Yacht Club |
The Esplanade, Indented Head VIC 3223 |
|
St Leonards Yacht Club & Motor Squadron |
Lower Bluff Road, St Leonards VIC 3223 |
|
Geelong Watersports Club Incorporated |
493-499 Wilsons Road, St Albans Park VIC 3219 |
|
Geelong College Rowing Club |
4 Barwon Terrace, South Geelong VIC 3220 |
|
Geelong Pistol Club |
70-80 Williams Road, Mount Duneed VIC 3216 |
|
Geelong Table Tennis Association |
84-88 Church Street, North Geelong VIC 3215 |
|
Western Beach Boat Club Incorporated |
74-90 Western Foreshore Road, Geelong VIC 3220 |
|
Lagoon Boat Club Inc |
Foreshore Road, Corio VIC 3214 |
|
Lara Sporting Club Incorporated |
4 Walkers Road, Lara VIC 3212 |
|
Western District Car Club |
55 Beach Road, Avalon VIC 3212 |
|
Corio Bay Sailing Club |
Foreshore Road, Corio VIC 3214 |
|
North Shore Sports & Community Club Inc |
39 Rose Avenue, Norlane VIC 3214 |
|
Herne Hill Bowls Club Inc |
180 McCurdy Road, Fyansford VIC 3221 |
|
Norlane Bowling Club Incorporated |
26-36 St Georges Road, Corio VIC 3214 |
|
Lara Bowling Club Inc |
120 Station Lake Road, Lara VIC 3212 |
|
Barwon Heads Bowling Club |
18 Geelong Road East, Barwon Heads VIC 3227 |
|
Geelong & Dist Angling Club & Fish Protect Soc. |
9 Yuille Street, Geelong West VIC 3218 |
|
Seabrae Boat Owners Club Inc |
302 Clifton Avenue, Leopold VIC 3224 |
Properties granted Cultural & Recreational Rate status include any other not-for-profit clubs or associations having similar characteristics and objectives to Cultural & Recreational land as defined which is extended to include indoor sporting, recreational and cultural activities. To be considered, each property should have limited venue hire, restricted liquor licensing provisions and have little impact on neighbouring amenity.
|
Ratepayer Name |
Property Address |
|
Geelong Bridge Club |
148-152 Portarlington Road, Newcomb Vic 3219 |
|
Austrian Club Geelong Incorporated |
258 Plantation Road, Lovely Banks Vic 3221 |
|
Serbian Parish Youth Club |
256 Plantation Road, Lovely Banks, Vic 3221 |
|
Polish Community Association in Geelong |
35 Ryrie Street, Geelong Vic 3220 |
1. Farm Land
Rating Objectives:
To ensure that all rateable land makes an equitable and efficient financial contribution to the cost of carrying out the functions of Council generally, including the:
construction and maintenance of public infrastructure;
development and provision of health and community services; and
provision of general support services.
To encourage and support the business of primary production and, where appropriate, expand the business of primary production.
These objectives will be met by setting the Farm Land differential at 100% of the Residential Land differential and by the provision of a farm rebate under Section 169 of the LGA.
Types and Classes
Rateable land having the relevant characteristics described previously in 2.3.
Use and Level of Differential Rate
The differential rate will be used to fund some of those items of expenditure described in the Budget adopted by Council.
The level of the differential rate less the applicable rebate is the level, which Council considers it necessary to achieve the objectives specified above.
Geographic Location
Wherever located within the municipal district.
Use of Land
Any use permitted under the Greater Geelong Planning Scheme.
Planning Scheme Zoning
The zoning applicable to each rateable land within this category, as determined by consulting maps referred to in the Greater Geelong Planning Scheme.
Types of Buildings
All buildings which are now constructed on the land or which are constructed prior to 30 June 2014.
2. Residential Land
Rating Objective:
To ensure that all rateable land makes an equitable and efficient financial contribution to the cost of carrying out the functions of Council generally, including the:
construction and maintenance of public infrastructure;
development and provision of health and community services; and
provision of general support services.
Types and Classes
Rateable land having the relevant characteristics described previously in 2.3.
Use and Level of Differential Rate
The differential rate will be used to fund some of those items of expenditure described in the Budget adopted by Council.
The level of the differential rate is the level which Council considers is necessary to achieve the objectives specified above.
Geographic Location
Wherever located within the municipal district.
Use of Land
Any use permitted under the Greater Geelong Planning Scheme.
Planning Scheme Zoning
The zoning applicable to each rateable land within this category, as determined by consulting maps referred to in the Greater Geelong Planning Scheme.
Types of Buildings
All buildings which are now constructed on the land or which are constructed prior to 30 June 2014.
Rating Objectives:
To ensure that all rateable land makes an equitable and efficient financial contribution to the cost of carrying out the functions of Council generally, including the:
construction and maintenance of public infrastructure;
development and provision of health and community services; and
provision of general support services.
To encourage the prompt development of vacant land to attract new residents and businesses to the City of Greater Geelong.
To discourage untimely and unnecessary divisions of land.
These objectives will be met by setting the Vacant Land differential at 140% of the Residential Land differential.
Types and Classes
Rateable land having the relevant characteristics described previously in 2.3.
Use and Level of Differential Rate
The differential rate will be used to fund some of those items of expenditure described in the Budget adopted by Council.
Geographic Location
Wherever located within the municipal district.
Use of Land
Any use permitted under the Geelong Regional Planning Scheme.
Planning Scheme Zoning
The zoning applicable to each rateable land within this category, as determined by consulting maps referred to in the Geelong Regional Planning Scheme.
Types of Buildings
No building must be located on the land or constructed prior to 30 June 2013 save
for any uninhabitable shed or shelter that does not exceed more than 5% of the total area of the land.
Rating Objective:
To ensure that all rateable land makes an equitable and efficient financial contribution to the cost of carrying out the functions of Council generally, including the:
construction and maintenance of public infrastructure;
development and provision of health and community services; and
provision of general support services.
The Petroleum Production Land differential is set at 367% of the Residential Land differential with the long term intention that the Petroleum Production Land differential will move closer to the Industrial Land differential over time.
Types and Classes
Rateable land having the relevant characteristics described previously 2.3.
Use and Level of Differential Rate
The differential rate will be used to fund some of those items of expenditure described in the Budget adopted by Council.
Geographic Location
As described in Schedule A.
Use of Land
Any use permitted under the Greater Geelong Planning Scheme.
Planning Scheme Zoning
The zoning applicable to each rateable land within this category, as determined by
consulting maps referred to in the Greater Geelong Planning Scheme.
Types of Buildings
All buildings which are now constructed on the land or which are constructed prior to
30 June 2014.
Rating Objective:
To ensure that all rateable land makes an equitable and efficient financial contribution to the cost of carrying out the functions of Council generally, including the:
construction and maintenance of public infrastructure;
development and provision of health and community services; and
provision of general support services.
Types and Classes
Rateable land having the relevant characteristics described previously in 2.3.
Use and Level of Differential Rate
The differential rate will be used to fund some of those items of expenditure described in the Budget adopted by Council.
Geographic Location
Wherever located within the municipal district.
Use of Land
Any use permitted under the Greater Geelong Planning Scheme.
Planning Scheme Zoning
The zoning applicable to each rateable land within this category, as determined by consulting maps referred to in the Greater Geelong Planning Scheme.
Types of Buildings
All buildings which are now constructed on the land or which are constructed prior to 30 June 2014.
Rating Objective: To ensure that all rateable land makes an equitable and efficient financial contribution to the cost of carrying out the functions of Council generally, including the:
construction and maintenance of public infrastructure;
development and provision of health and community services; and
provision of general support services.
The Aluminium Production Land differential is set at 367% of the Residential Land differential with the long term intention that the Aluminium Production Land differential will move closer to the Industrial Land differential over time.
Types and Classes
Rateable land having the relevant characteristics described previously in 2.3.
Use and Level of Differential Rate
The differential rate will be used to fund some of those items of expenditure described
in the Budget adopted by Council.
Geographic Location
As described in Schedule A.
Use of Land
Any use permitted under the Greater Geelong Planning Scheme.
Planning Scheme Zoning
The zoning applicable to each rateable land within this category, as determined by
consulting maps referred to in the Greater Geelong Planning Scheme.
Types of Buildings
All buildings which are now constructed on the land or which are constructed prior to
30 June 2014.
Rating Objective:
To ensure that all rateable land makes an equitable and efficient financial contribution to the cost of carrying out the functions of Council generally, including the:
construction and maintenance of public infrastructure;
development and provision of health and community services; and
provision of general support services.
The Automobile Manufacture Land differential is set at 367% of the Residential Land differential with the long term intention that it will move closer to the Industrial Land differential over time.
Types and Classes
Rateable land having the relevant characteristics described previously in 2.3.
Use and Level of Differential Rate
The differential rate will be used to fund some of those items of expenditure described
in the Budget adopted by Council.
Geographic Location
As described in Schedule A.
Use of Land
Any use permitted under the Greater Geelong Planning Scheme.
Planning Scheme Zoning
The zoning applicable to each rateable land within this category, as determined by consulting maps referred to in the Greater Geelong Planning Scheme.
Types of Buildings
All buildings which are now constructed on the land or which are constructed prior to 30 June 2014.
Rating Objective:
To ensure that all rateable land makes an equitable and efficient financial contribution to the cost of carrying out the functions of Council generally, including the:
construction and maintenance of public infrastructure;
development and provision of health and community services; and
provision of general support services.
Types and Classes
Rateable land having the relevant characteristics described previously in 2.3.
Use and Level of Differential Rate
The differential rate will be used to fund some of those items of expenditure described in the Budget adopted by Council.
Geographic Location
Wherever located within the municipal district.
Use of Land
Any use permitted under the Greater Geelong Planning Scheme.
Planning Scheme Zoning
The zoning applicable to each rateable land within this category, as determined by consulting maps referred to in the Greater Geelong Planning Scheme.
Types of Buildings
All buildings which are now constructed on the land or which are constructed prior to 30 June 2014.
Rating Objectives:
To ensure that all rateable land makes an equitable and efficient financial contribution to the cost of carrying out the functions of Council generally, including the:
construction and maintenance of public infrastructure;
development and provision of health and community services;
provision of general support services; and
management of environmentally sensitive land.
To ensure that, following the development of the Point Land, and transfer to Council of the management of environmentally sensitive land, including the provision of a range of services around an existing waterway, constructed lake and canal system, an equitable and efficient financial contribution to the cost of Council's management responsibilities will be made by the ratepayers in respect of that land.
Types and Classes
Rateable land having the relevant characteristics described previously in 2.3.
Use and Level of Differential Rate
The differential rate will be used to fund some of those items of expenditure described in the Budget adopted by Council.
Geographic Location
As described in Schedule A.
Use of Land
Any use permitted under the Greater Geelong Planning Scheme.
Planning Scheme Zoning
The zoning applicable to each rateable land within this category, as determined by consulting maps referred to in the Greater Geelong Planning Scheme.
Types of Buildings
All buildings which are now constructed on the land or which are constructed prior to 30 June 2014.
Rating Objectives:
To ensure that all rateable land makes an equitable and efficient financial contribution to the cost of carrying out the functions of Council, generally including the:
construction and maintenance of public infrastructure;
development and provision of health and community services;
provision of general support services; and
management of environmentally sensitive land.
To ensure that, following the development of the Point Land, and transfer to Council of the management of environmentally sensitive land, including the provision of a range of services around an existing waterway, constructed lake and canal system, an equitable and efficient financial contribution to the cost of Council's management responsibilities will be made by the ratepayers in respect of that land.
Types and Classes
Rateable land having the relevant characteristics described previously in 2.3.
Use and Level of Differential Rate
The differential rate will be used to fund some of those items of expenditure described in the Budget adopted by Council.
Geographic Location
As described in Schedule A.
Use of Land
Any use permitted under the Greater Geelong Planning Scheme.
Planning Scheme Zoning
The zoning applicable to each rateable land within this category, as determined by consulting maps referred to in the Greater Geelong Planning Scheme.
Types of Buildings
All buildings which are now constructed on the land or which are constructed prior to 30 June 2014.
Rating Objectives:
To ensure that all rateable land makes an equitable and efficient financial contribution to cost of carrying out the functions of Council, generally including the:
construction and maintenance of public infrastructure;
development and provision of health and community services;
provision of general support services; and
management of environmentally sensitive land.
To ensure that, following the development of the Point Land, and transfer to Council of the management of environmentally sensitive land, including the provision of a range of services around an existing waterway, constructed lake and canal system, to ensure that an equitable and efficient financial contribution to the cost of Council's management responsibilities will be made by the ratepayers in respect of that land.
Types and Classes
Rateable land having the relevant characteristics described previously in 2.3.
Use and Level of Differential Rate
The differential rate will be used to fund some of those items of expenditure described in the Budget adopted by Council.
Geographic Location
As described in Schedule A.
Use of Land
Any use permitted under the Greater Geelong Planning Scheme.
Planning Scheme Zoning
The zoning applicable to each rateable land within this category, as determined by consulting maps referred to in the Greater Geelong Planning Scheme.
Types of Buildings
All buildings which are now constructed on the land or which are constructed prior to 30 June 2014.
Has the characteristics of Recreational land as defined by the Cultural and Recreational Lands Act 1963.
Types and Classes
Rateable land having the relevant characteristics described previously in 2.4.
Use and Level of Differential Rate
The differential rate will be used to fund some of those items of expenditure described in the Budget adopted by Council.
Geographic Location
As described in Schedule A.
Use of Land
Any use permitted under the Greater Geelong Planning Scheme.
Planning Scheme Zoning
The zoning applicable to each rateable land within this category, as determined by consulting maps referred to in the Greater Geelong Planning Scheme.
Types of Buildings
All buildings which are now constructed on the land or which are constructed prior to 30 June 2014.
Portfolio: |
Governance – Cr Fagg (Mayor) |
Source: |
Economic Development, Planning & Tourism – Strategic Implementation |
General Manager: |
Jeff Wall |
Index Reference: |
Subject: Corporate Strategy |
The Local Government Act 1989 provides that following the October 2012 Council Election, Council is required to prepare a new Council Plan and have it submitted to the Minister for Local Government by 30 June 2013.
Section 125 of the Local Government Act also prescribes that a Council Plan must include:
The strategic objectives of the Council,
Strategies for achieving the objectives for the Council term,
Strategic indicators for monitoring the achievement of these objectives,
A Strategic Resource Plan, and
Any other matter prescribed by the regulations.
In developing City Plan 2013-2017, nine community workshops were held. Workshops were held in Belmont, Drysdale, Geelong CBD, Hamlyn Heights, Lara and Norlane, along with workshops with the CALD, Disability and Indigenous groups. Workshops were also held with Councillors and the Joint Managers and Coordinators groups with a total number of 242 people participating in the workshops.
A survey was also conducted with 278 completed. Surveys were completed both online (160) and by hard copy (118). 41 comments were also provided on the online forum.
In total, 9,888 pieces of information were collected from the above workshops and surveys.
A desktop review of relevant strategies was also conducted and included: the Bellarine Peninsula Strategic Plan 2006-2016; Corio Norlane Structure Plan; G21 Regional Growth Plan; GeeYoung Project; Grovedale Oberon 3216 Community Plan; Multicultural Action Plan; Vision 2; and the Whittington Action Plan. Results from the Springdale Neighbourhood Summit were also considered.
Further workshops were held with Council and ‘Arena’ groups featuring the Management group to review information gathered through the above workshops, survey results and desktop review, and to develop City Plan 2013-2017 priorities.
Following the community and organisation engagement process Council has developed a vision for inclusion in the draft City Plan – ‘Greater Geelong: building our community through enterprise, opportunity and innovation in a quality environment.’
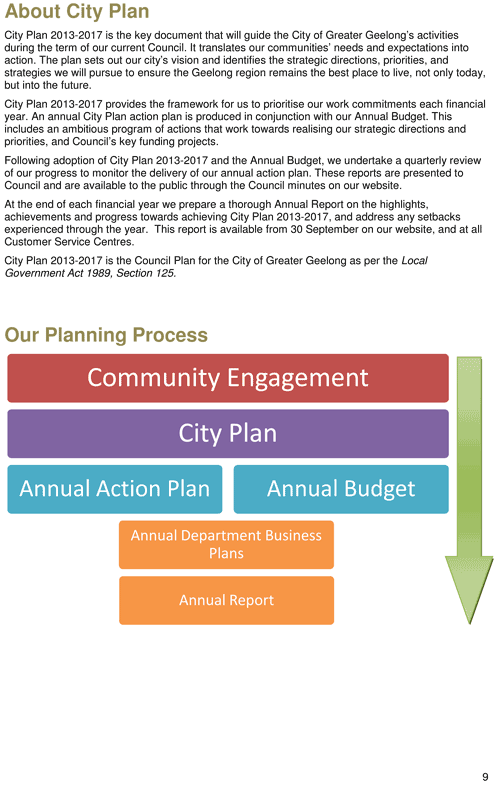
A draft of ‘City Plan 2013-2017’ has been produced to be launched at the Annual Community Leaders City Plan/Budget breakfast. This draft links the Annual Budget to the four-year strategic direction of the City.
It is intended that a complete draft version will be available at Customer Service Centres and on the Council’s web site shortly after 14 May 2013.
Cr S Kontelj moved, Cr Harwood seconded -
That Council:
Receives and considers the proposed City Plan 2013-2017 as per Appendix 3-1.
In conjunction with the proposed 2013-2014 Budget, Council advertises the proposed City Plan 2013-2017 and invites written submissions.
After considering the report of the Submissions Panel adopts the City Plan 2013-2017 at the Council Meeting scheduled to be held on Tuesday 25 June 2013.
Carried.
The Local Government Act requires that a Council must prepare, approve and submit to the Minister a Council Plan (i.e. “City Plan”):
By 30 June 2013, and
Within the period of 6 months after each general election year or by the next 30th June, whichever is the latter.
Section 125 of the Local Government Act also prescribes that a Council Plan must include:
The strategic objectives of the Council,
Strategies for achieving the objectives for at least the next four years,
Strategic indicators for monitoring the achievement of these objectives,
A Strategic Resource Plan, and
Any other matter prescribed by the regulations.
In subsequent years, councils are required to, at least once in each financial year, consider whether the current Council Plan requires any adjustment in respect of the remaining period of the Council Plan.
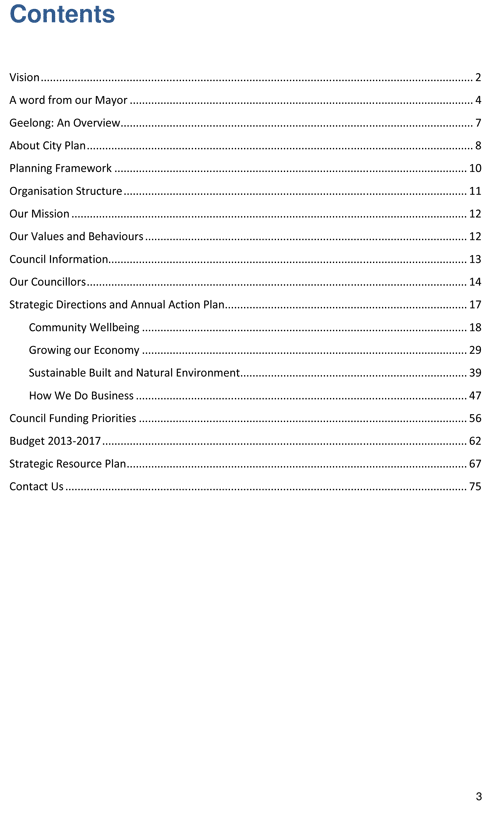
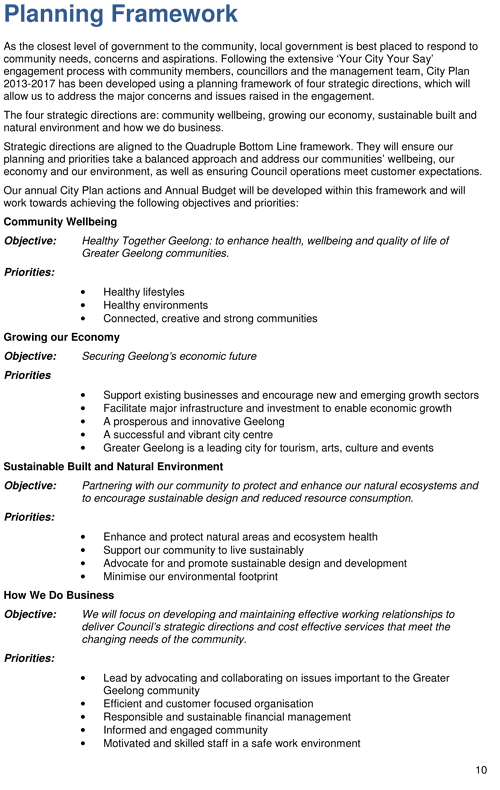
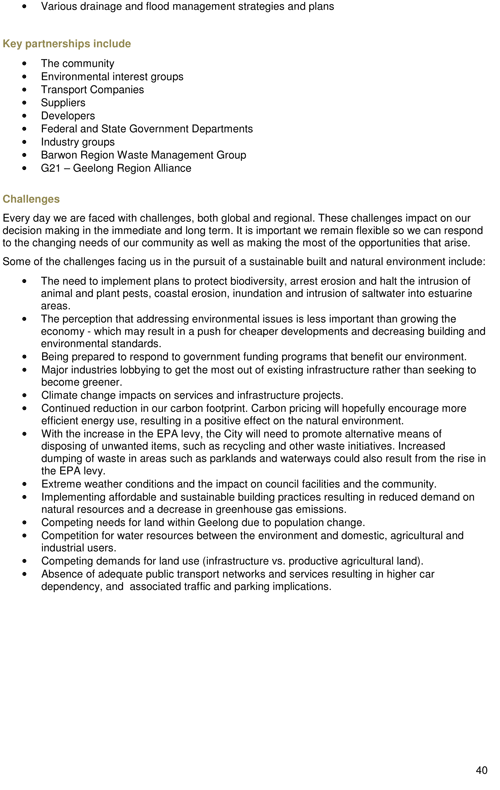
The framework for the City Plan 2013-2017 incorporates the planning framework based on the on the Quadruple Bottom Line framework and features four strategic directions (Community Wellbeing, Growing our Economy, Sustainable Built and Natural Environment and How We Do Business), supporting internal objectives and the Council’s Vision, Mission, Values and Behaviours section.
The Council’s performance and results in achieving the strategic indicators of the City Plan are required to be reported in the Council’s Annual Report for 2013-2014.
City Plan 2013-2017 has been developed to reflect the results of the community engagement undertaken, Council’s current priorities and the supporting resource allocation.
Council have also developed the following vision for inclusion in City Plan 2013-2017, which takes into account the community’s input from engagement process:
‘Greater Geelong: building our community through enterprise, opportunity and innovation in a quality environment.’
All the actions within City Plan have been developed collaboratively across the organisation and support the long-term social, environmental and economic benefits for the community articulated through the Vision, Mission and Objectives established by the Council.
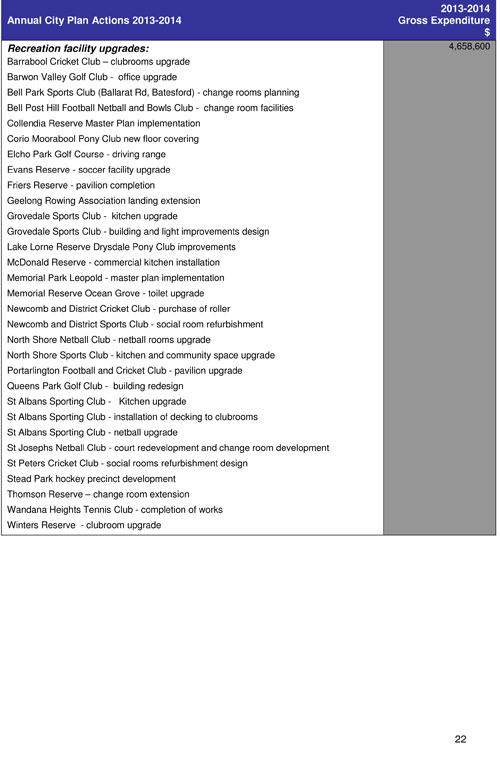
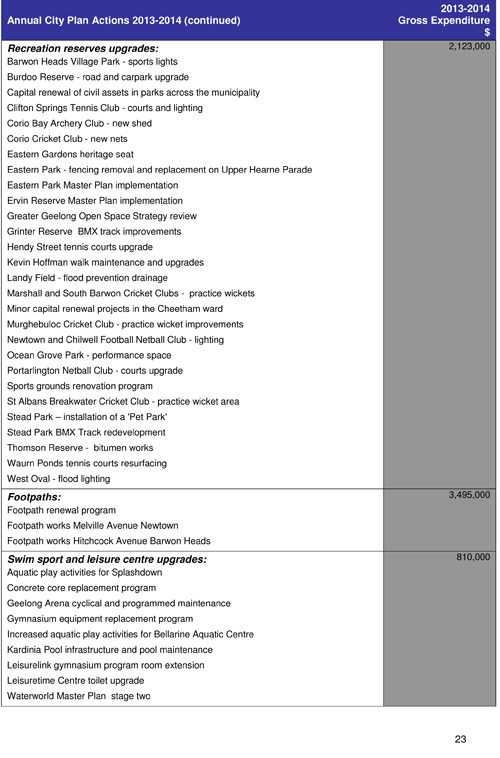
City Plan identifies the key priorities, strategies and progress indicators that are currently planned over the said four-year period, as well as detailed actions associated with implementing this four-year City Plan.
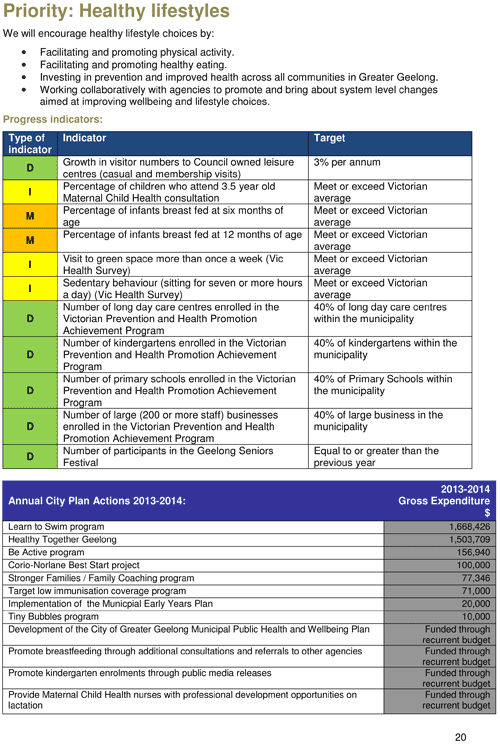
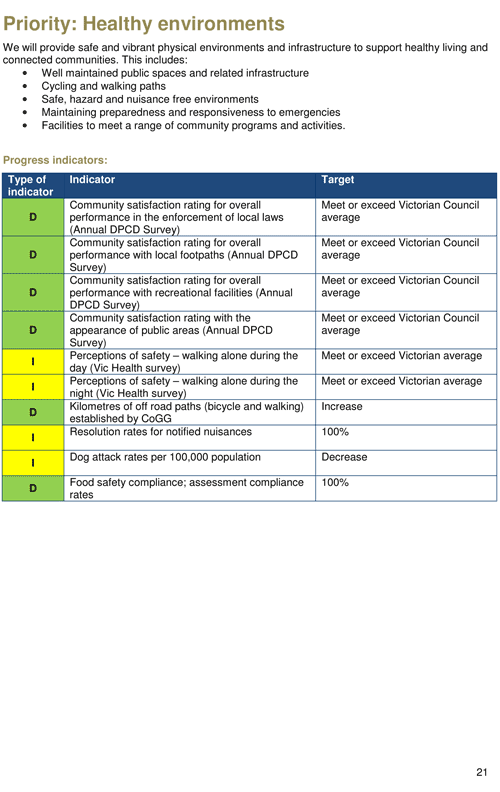
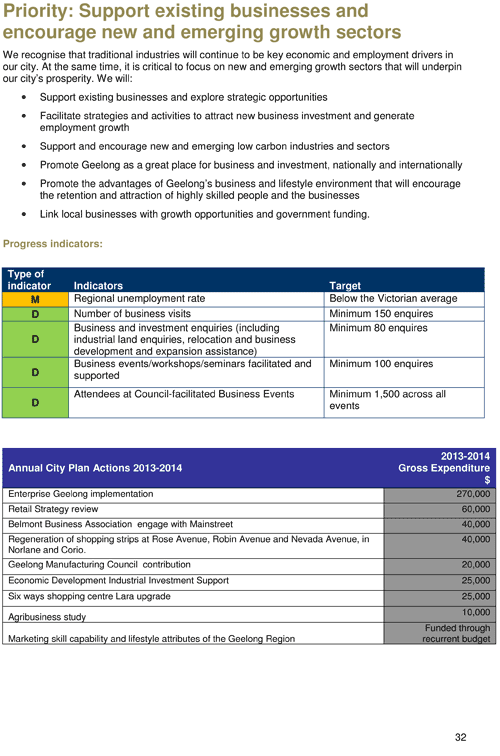
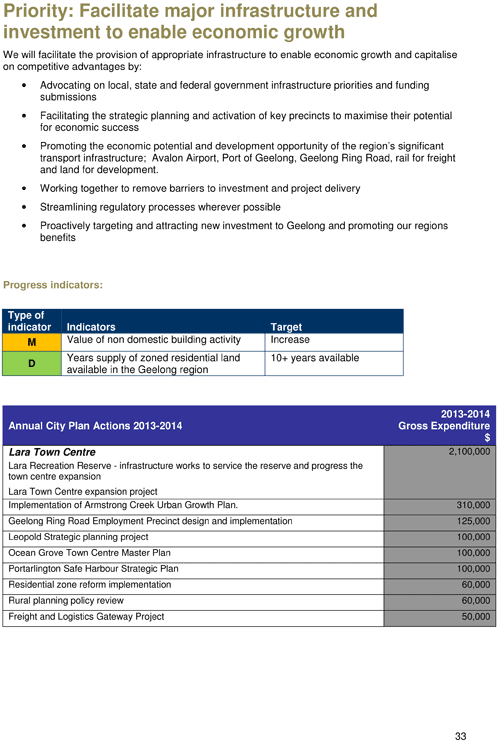
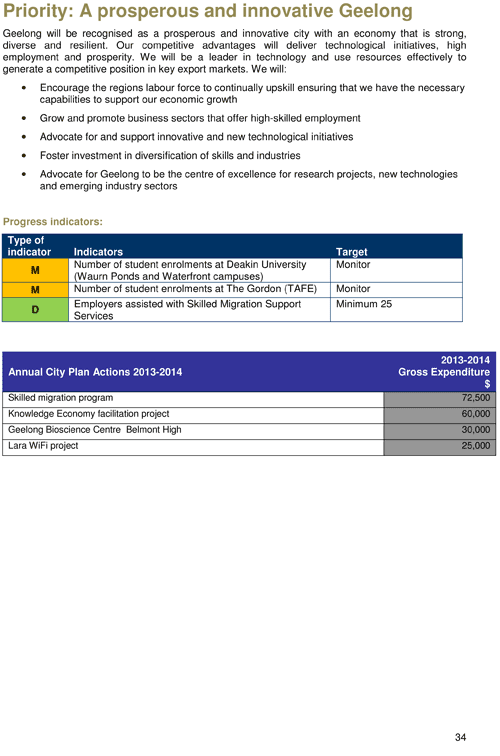
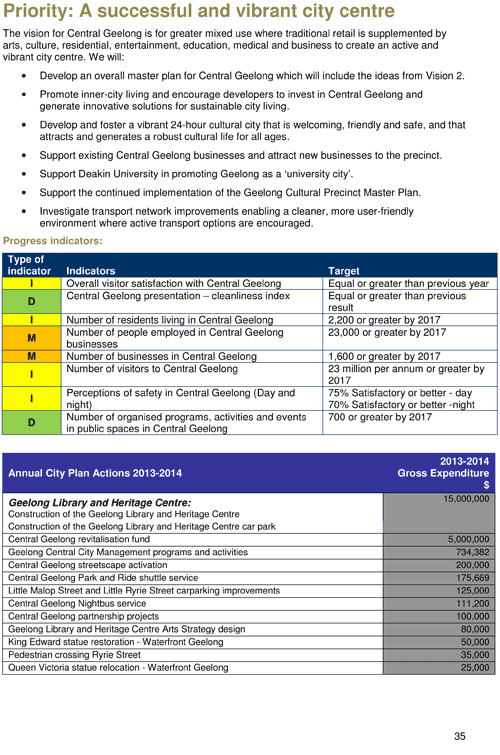
The priorities under each of the four strategic directions are as follows:
Community Wellbeing
Healthy lifestyles
Healthy environments
Connected, creative and strong communities
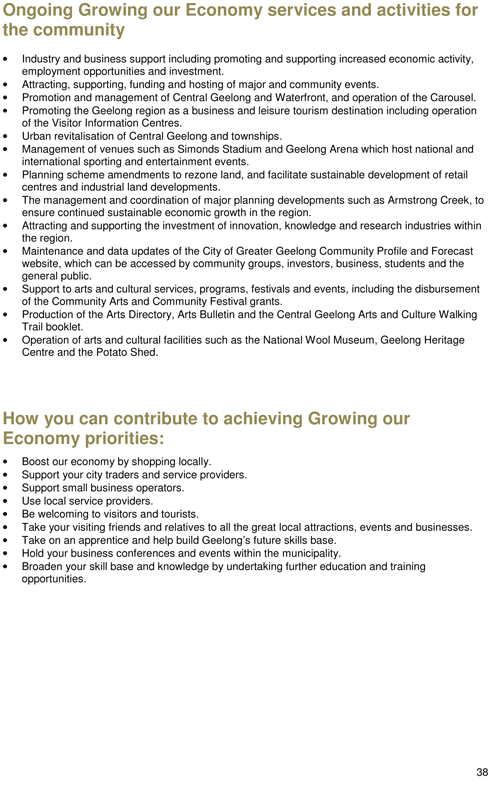
Growing our Economy
Support existing businesses and encourage new and emerging growth sectors
Facilitate major infrastructure and investment to enable economic growth
A prosperous and innovative Geelong
A successful and vibrant city centre
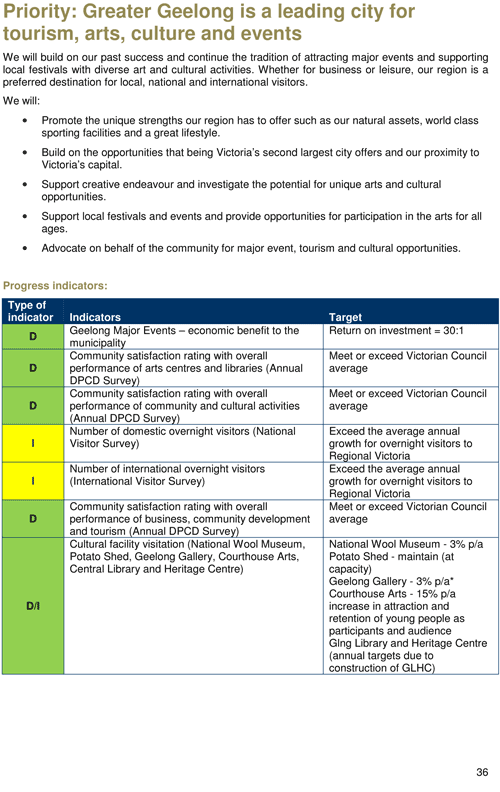
Greater Geelong is a leading city for tourism, arts, culture and events
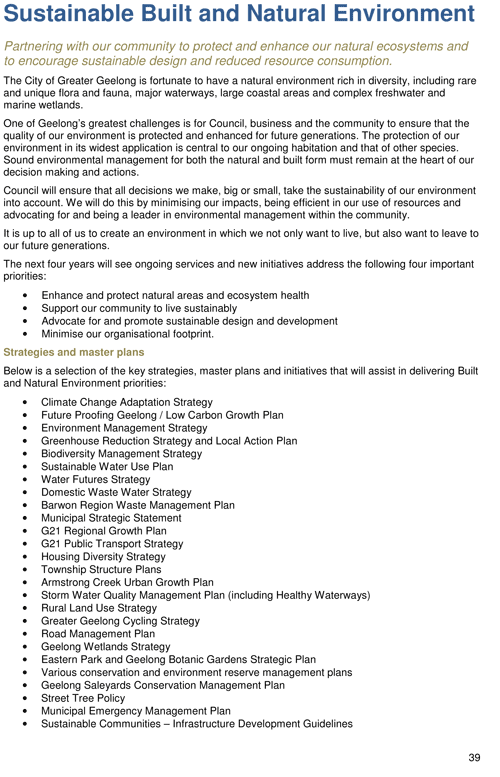
Sustainable Built and Natural Environment
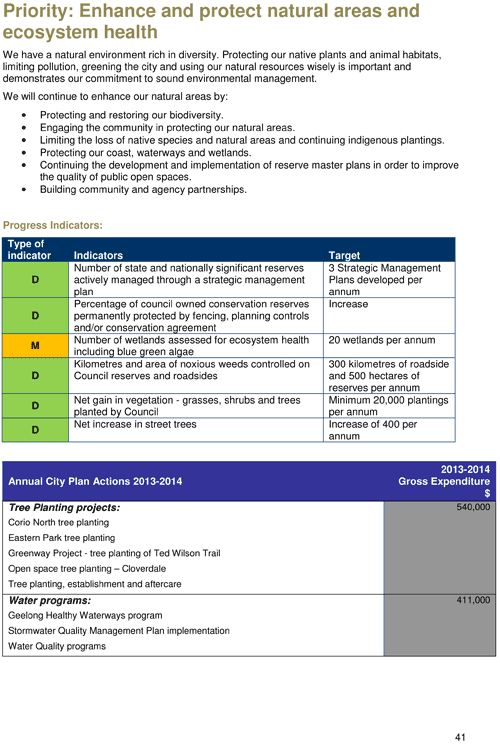
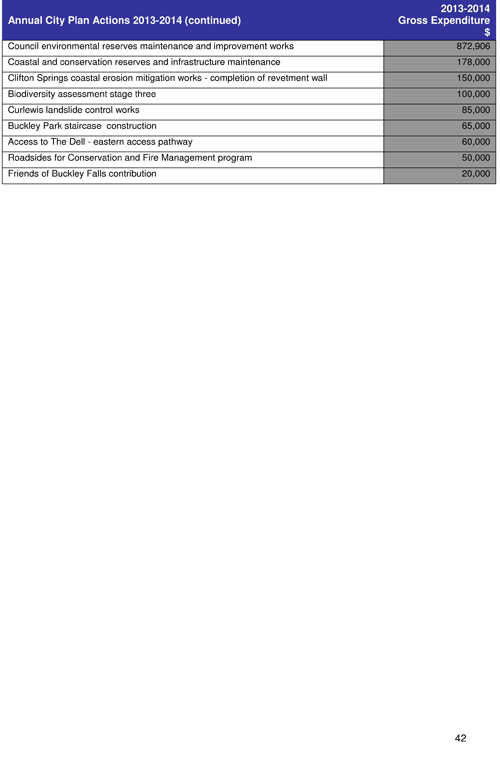
Enhance and protect natural areas and ecosystem health
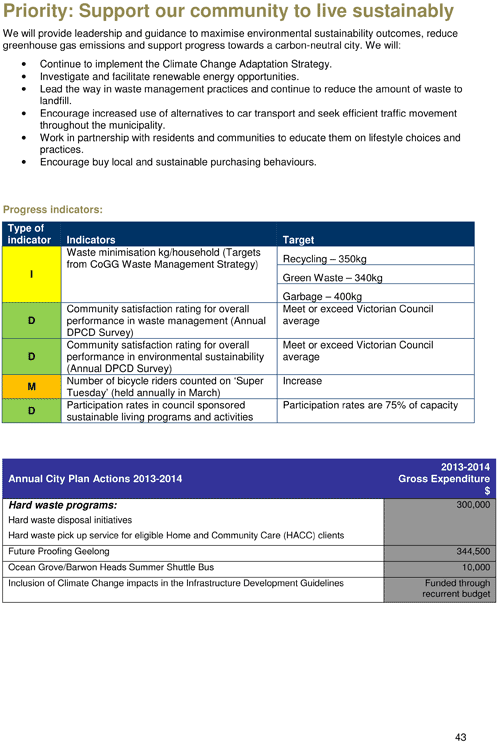
Support our community to live sustainably
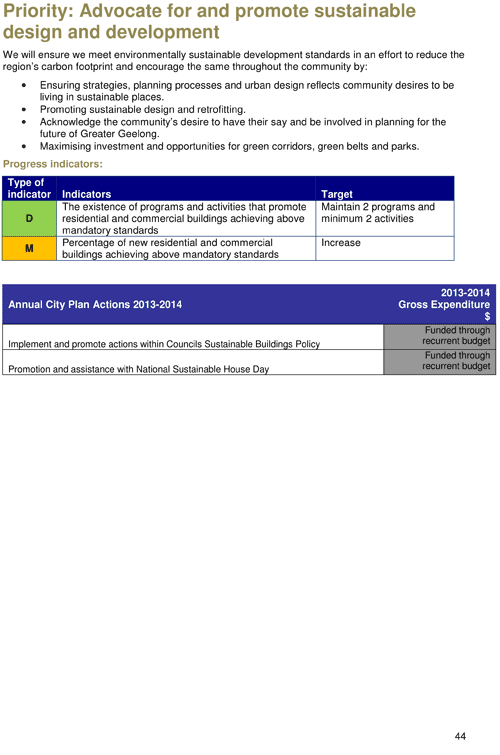
Advocate for and promote sustainable design and development
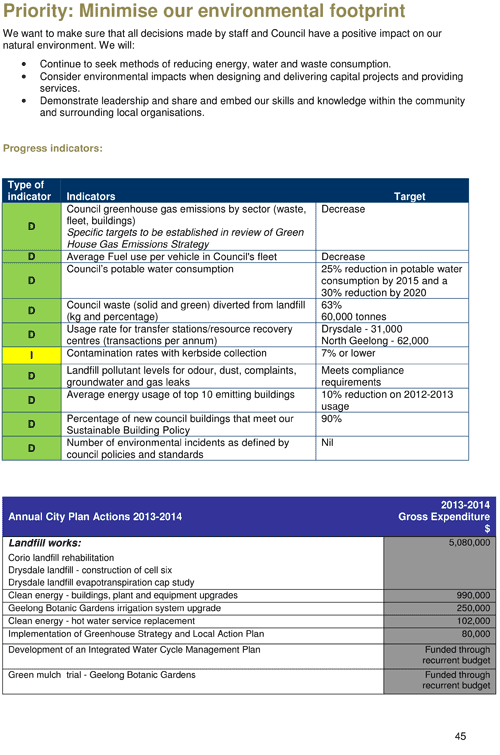
Minimise our environmental footprint
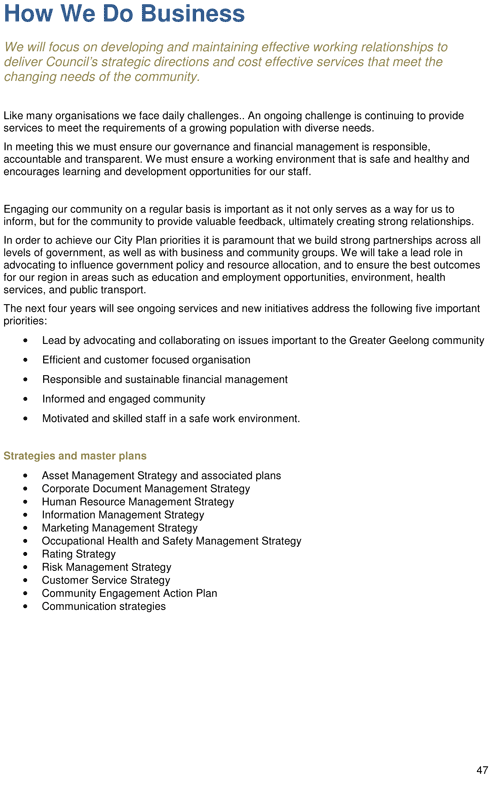
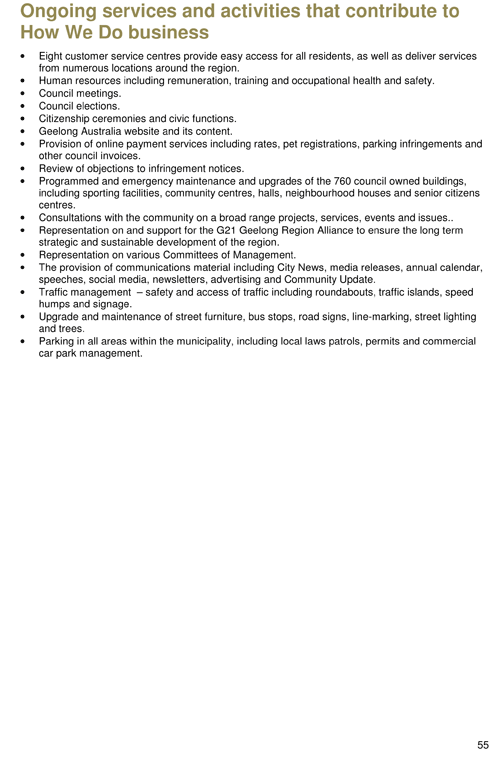
How We Do Business
Lead by advocating and collaborating on issues important to the Greater Geelong community
Efficient and customer focused organisation
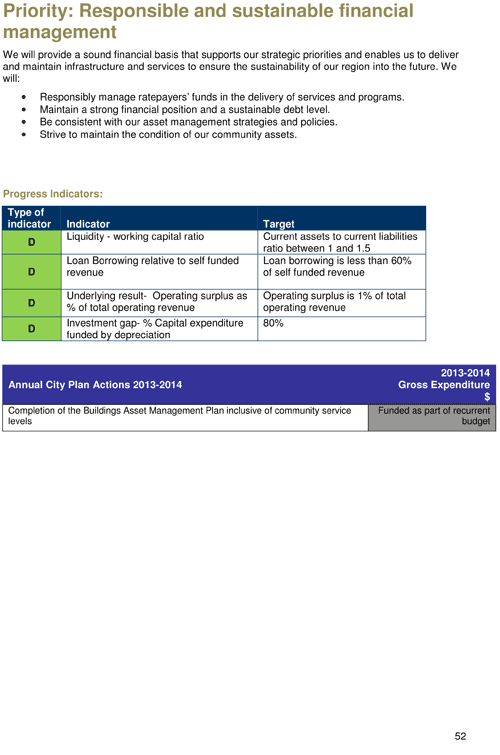
Responsible and sustainable financial management
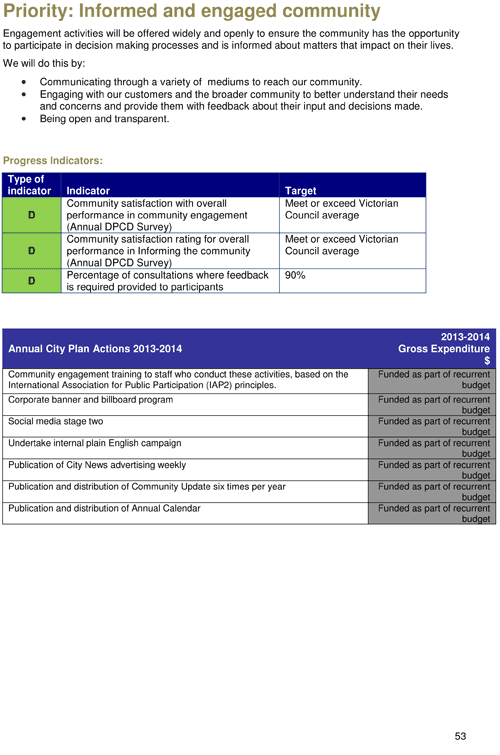
Informed and engaged community
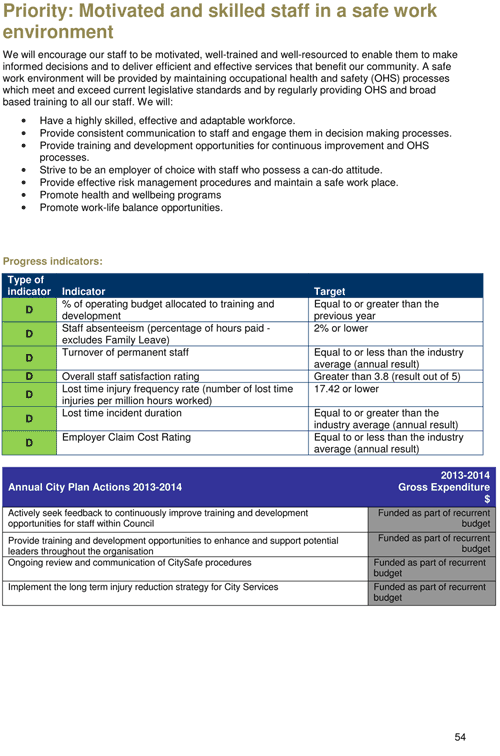
Motivated and skilled staff in a safe work environment
It is planned to have the full version of City Plan 2013-2017 available on the Council’s web site shortly after 30 June 2013.
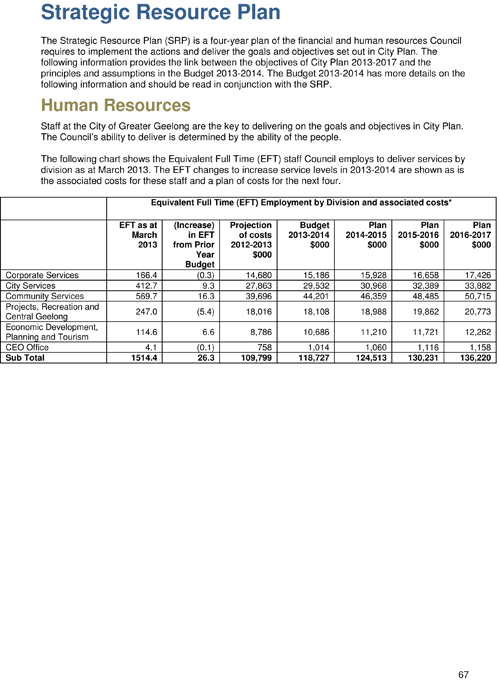
As part of the legislative requirement, City Plan includes the Strategic Resource Plan (updated taking into account the 2013-2014 Annual Budget as a base year), which contains the financial and non-financial (human resources) information for the next four years.
‘City Plan 2013-2017’ document is scheduled to be presented at the Community Leaders City Plan Budget Breakfast on 15 May 2013 as the “Draft City Plan 2013-2017” document.
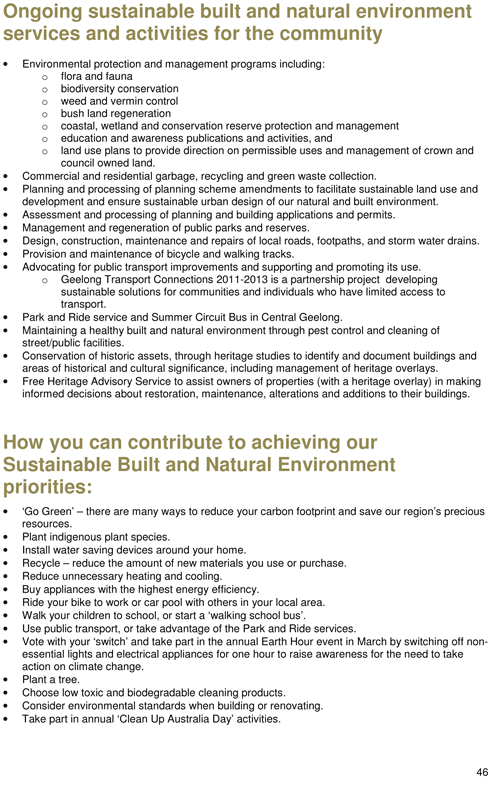
City Plan 2013-2017 outlines the objectives and strategies to deliver the environmental benefits to the community. Details of these can be found within the Sustainable Built and Natural Environment Strategic Direction.
City Plan 2013-2017 includes Council’s four-year financial strategy and plan with the 2013-2014 Annual Budget representing the first year in implementing the updated plan.
The Local Government Act requires that a Council must prepare, approve and submit to the Minister for Local Government a Council Plan (i.e. “City Plan”):
By 30 June 2013, and
Within the period of 6 months after each general election year or by the next 30th June, whichever is the latter.
Section 125 of the Local Government Act also prescribes that a Council Plan must include:
The strategic objectives of the Council;
Strategies for achieving the objectives for at least the next four years;
Strategic indicators for monitoring the achievement of these objectives;
A Strategic Resource Plan, and
Any other matter prescribed by the regulations.
The Act also prescribes that any amendments to City Plan must be advised to the Minister within 30 days.
The draft City Plan 2013-2017 complies with the Local Government Act, 1989.
There is no direct or indirect officer interest to which this report relates.
Failing to submit City Plan 2013-2017 to the Minister by 30 June 2013 would result in non-compliance.
City Plan 2013-2017 outlines the objectives and strategies to deliver the social benefits to the community.
Public access to City Plan 2013-2017 will be through the City of Greater Geelong Customer Service Centres and Council’s Internet site (www.geelongaustralia.com.au).
As the Local Government Act provides for public submissions it is proposed to invite public submission to the draft City Plan 2013-2017 in conjunction with the 2013-2014 Annual Budget for the prescribed 28 day period, with a view to adoption at the Council Meeting scheduled to be held on Tuesday 25 June 2013.
Portfolio: |
Governance – Cr Fagg (Mayor) |
Source: |
Corporate Services – Corporate Strategy |
General Manager: |
Jeff Wall |
Index Reference: |
Index/Corporate Management |
Council at its meeting of 26 June 2012 adopted City Plan 2009-2013, 2012-2013 Update, that outlined the Objectives and Strategies planned by the City over the final year of that four year period, and the Annual Business Plan Actions planned for 2012-2013.
This report is the progress report to Council of the organisations achievements against these actions.
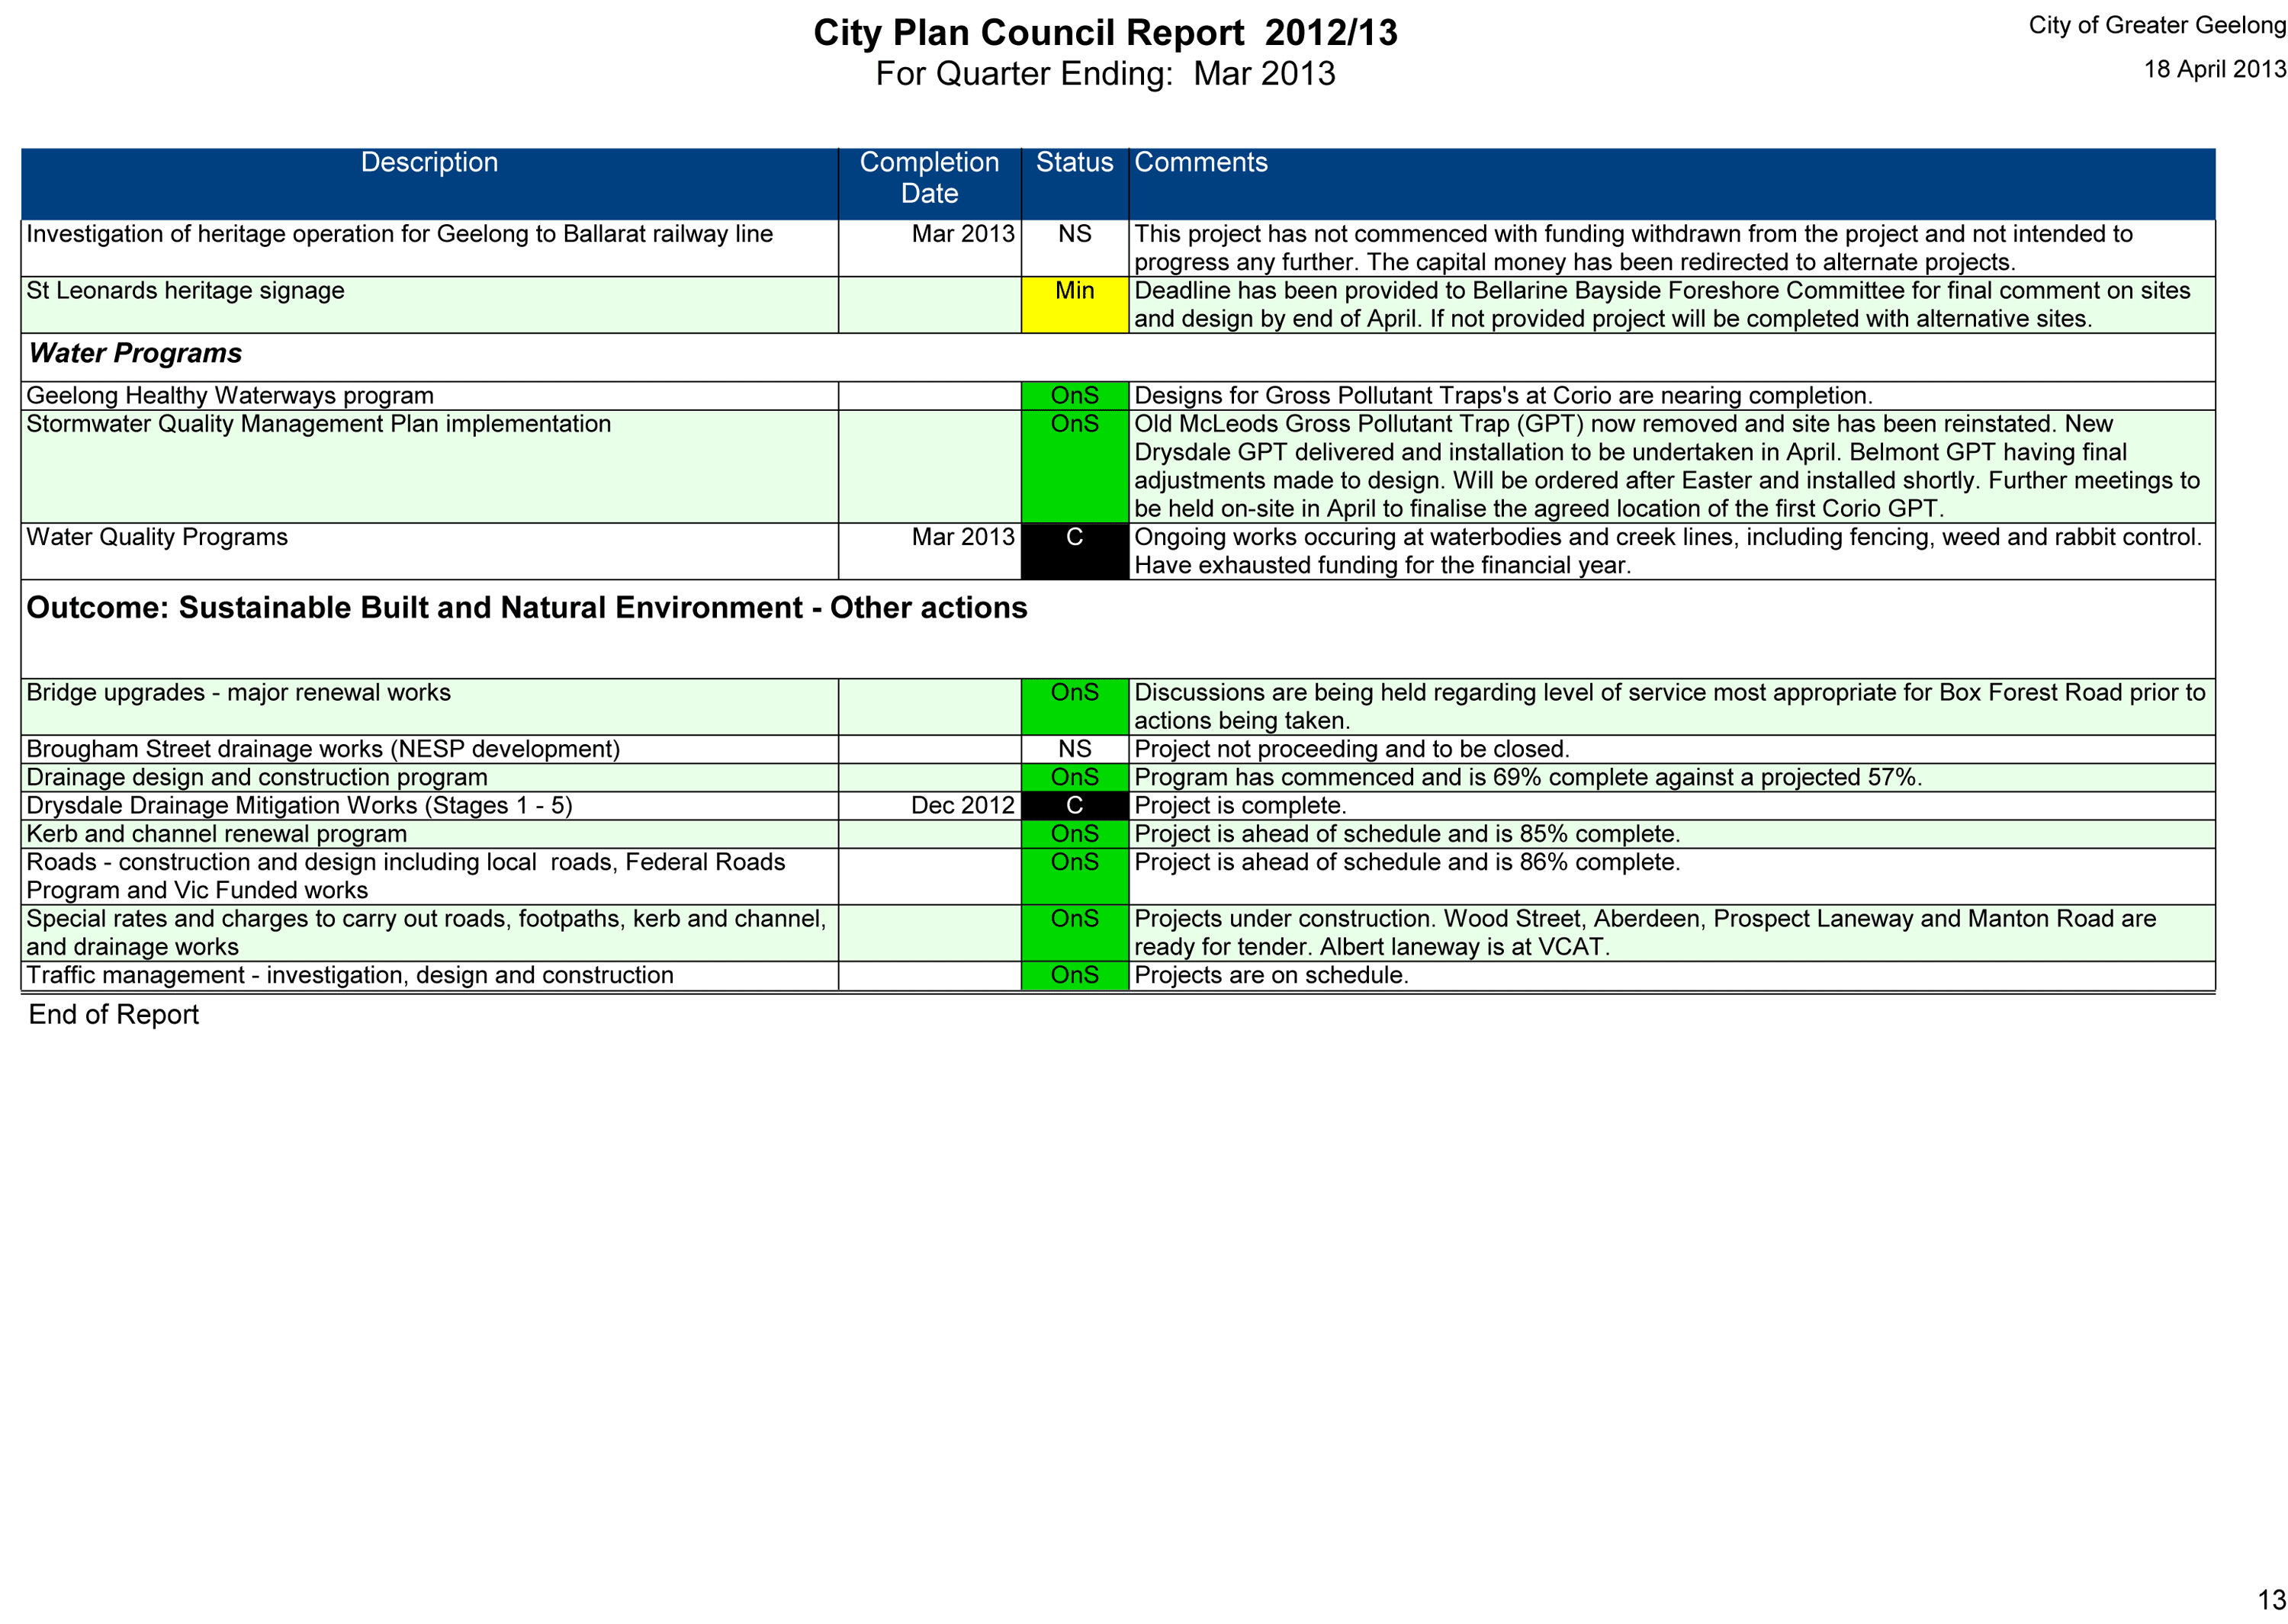
Attachment A details the status and provides commentary against the Annual Business Plan actions. This report has been generated from the Corvu Performance Management System. The key to the status of actions is:
Major Issue |
Red |
2 |
Minor Issue |
Yellow |
8 |
Not yet Started |
White |
8 |
On Schedule |
Green |
171 |
Completed |
Black (‘C’ in white font) |
39 |
Total Actions |
|
228 |
Cr S Kontelj moved, Cr Harwood seconded -
That Council receives and notes the City Plan Progress Report to 31 March 2013.
Carried.
Council at its meeting of 26 June 2012 adopted City Plan 2009-2013, 2012-2013 Update which has been developed within a framework of three Strategic Directions:
Community Wellbeing
To improve the health and quality of life of all residents of Greater Geelong
Growing the Economy
Securing Geelong’s economic future
A Sustainable Built and Natural Environment
The City of Greater Geelong leads the community in sustainable planning and environmental action.
This report and attachment indicates the status of the actions in City Plan for the 2012-2013 financial year.
Status and comments are provided for each of the 228 actions within three strategic directions.
Some significant progress and completions within the quarter include:
Community Wellbeing
Status Summary
On Schedule |
103 |
Completed |
26 |
Major Issue |
1 |
Minor Issue |
2 |
Not Started |
4 |
|
|
The fOrt Youth Centre has been officially opened following a $420,000 major upgrade. The fOrt is a youth centre for young people to socialise and develop new skills in art, cooking, music and sport. The upgrade has included a new teaching kitchen, music room, office, storage space and new furniture and equipment. The upgrade will help to cater for the growing number of young people using the fOrt for the diverse range of activities it offers.
Five community halls and clubs have now received $658,364 in amenity upgrades to improve access to their facilities as part of the Disability Access program and Community hall upgrade funding. Centenary Hall, Cobradah House, Norlane Senior Citizens Club, Whittington Senior Citizens Club, and the Hamlyn Park Tennis Club have all been upgraded. Front entrance ramps, handrails and access to men’s and women’s toilets have been improved as part of the works. The upgrades will significantly benefit people in our community who live with a disability and will create more equal opportunities for everyone to participate in social activities. Construction works on Centenary Halll continue with stages two and three to consist of upgrades to the front entrance as well as landscaping and paving works.
The $750,000 Alex Rizun Pavilion upgrade, home to the Bell Park Football, Netball and Cricket clubs, is nearing completion. The upgrade to the pavilion, situated in the Hamlyn Park Recreation Reserve includes a new kitchen, away team change rooms, spectator’s area, public toilets including a disabled toilet and umpire’s change rooms. An extension to the pavilion will also make room for new home team change rooms, trainer’s rooms, ice baths, a team address room, football manager’s office, a workshop, toilets and showers.
Shell Road Reserve in Ocean Grove is continuing its transformation into a significant community hub, with new cricket, football, and netball facilities complete. The netball courts have now been resurfaced and have new lighting poles installed, new cricket practice wickets have also been installed as well as 13-metre light poles around the football oval. The Ocean Grove Integrated Children’s Centre which is also being put on Shell Road Reserve is progressing on schedule with construction well underway.
State Government funding has been secured for facility upgrades to two of the City’s sport and recreation reserves. Evans Reserve in Norlane has received $100,000 to upgrade its soccer facilities with a second pitch, a turf irrigation system and two additional light towers which will provide full ground lighting to a training standard. Stead Park in Corio has also received a $625,000 contribution from Sport and Recreation Victoria to go towards the $1.8 million project to install a second synthetic hockey pitch. A second pitch will allow for the Geelong Hockey Association to grow its member base particularly in the adult and youth category. The necessity for a new pitch was identified in the G21 Regional Sport and Recreation Infrastructure Strategy as well as the City’s 2010 Stead Park Master Plan.
Growing the Economy
Status Summary
On Schedule |
23 |
Completed |
7 |
Major Issue |
1 |
Minor Issue |
2 |
Not Started |
0 |
Geelong’s appeal as an international cruise ship destination and the need for a Yarra Street Pier has continued to grow with the ‘Seaborn Odyssey’ cruise ship visit in February, attracting approximately 450 people to the shores of Geelong. The ship made just two Victorian stops on its current Australasian tour – Geelong and Melbourne – demonstrating Geelong and Melbourne operate excellently as complimentary cruise ship destinations with each offering a different visitor experience. The addition of a purpose built pier would add considerably to Geelong’s appeal as a more regular port on international itineraries. The City of Greater Geelong has committed $5 million to build a new Yarra Street Pier and the Royal Geelong Yacht Club has pledged and additional 2.5 million. The anticipated cost of the proposed development is $33 million which Council is continuing to lobby for.
The design development phase for the new Geelong Library and Heritage Centre is now nearing completion which marks a significant milestone in the project and is the trigger for several major project components to commence. The unique dome design will house a new library, heritage repository, reading room and café. The building will provide all the very latest technologies and services expected of a 21st century library and heritage centre. The Geelong Library and Heritage Centre is jointly funded with Council contributing $20 million, the State Government $15 million, and the Federal Government $10 million.
A large number of events showcasing our region were held during the last quarter including the Australian International Airshow, Mitchelton Bay Cycling Classic (formerly Jayco Bay), The Great Australian Beer Festival, a Melbourne Rebels game at Simonds Stadium, The Hill Winery (formerly Pettavel) Music Concert, 2013 Men’s and Women’s Victorian Open Golf Championship, Nitro Circus Live, Festival of Sails, SKI Racing Victoria Grand Prix, Geelong Multi-Sport Festival, Pako Festa, Weet-Bix Kids TRYathlon, Head of the School Girls rowing regatta, Gatorade Triathlon, Barwon Heads Festival of the Sea and Lara Food and Wine Festival.
The continued planning of infrastructure across Armstrong Creek is progressing well. The West Precinct has now been adopted and planning permits issued for initial stages of development. The West Precinct includes 5,700 lots which now provide opportunities for competition to the earlier approved East Precinct. Further significant planning work is also being undertaken as part of the Town Centre Precinct and Horseshoe Bend Precinct, with both these precincts to progress to exhibition for planning scheme amendments in the second quarter of 2013.
The Freight and Logistics Gateway Project tender process was completed in February 2013 with the appointment of GHD and Luke Fraser to undertake the study. The strategic assessment for the Geelong Port and Land Freight Infrastructure Plan will identify the capacity of existing infrastructure as well as a cost benefit analysis of suggested infrastructure upgrades. The study is progressing well with interviews of key port users and other relevant parties being currently undertaken.
A Sustainable Built and Natural Environment
Status Summary
On Schedule /td> | 45 |
Completed |
6 |
pMajor Issue/ | 0 |
Minor Issue |
4 |
Not Started |
4 |
|
The major stormwater harvesting system at Eastern Park installed last year has already proved to be a success with over 296,000 litres of water from the dam used since November 2012. The stormwater harvesting project takes the form of a man-made lake in Eastern Park which is designed to look like a natural part of the landscape. The project is estimated to save 30 million litres of mains drinking water a year, recycling stormwater and using it to maintain the Geelong Botanic Gardens. The Geelong Botanic Gardens is in the top five water users for the City, and this project will be able to supply around 90 percent of the gardens’ water demands.
The City was one of 1,000 cities and towns worldwide to show their commitment to the environment and switch off lights for Earth Hour on 23rd March. The City turned off its non-essential lighting at City Hall, Ryrie Street (aesthetic street lighting), and the City of Greater Geelong flagpoles on Princess Highway, Corio. Participation in Earth Hour is a part of the Council’s ecoCHALLENGE initiative and long term commitment to reducing the organisations environmental footprint.
The ‘Rethink Your Rubbish’ program continues to be a success with various initiatives being held during the last quarter. A recent tyre promotion at Anakie Road Depot provided residents with the opportunity to drop off tyres at the discounted price of $3 per tyre. A total of 232 residents took advantage of the offer bringing in almost 1,200 tyres. The City also participated in a free TV drop-off weekend in March at the Geelong Racecourse, held by e-waste company TechCollect as a part of the National Television and Computer Recycle Scheme. The weekend received a huge response from the community with over 2,000 residents taking advantage, disposing of almost 8,000 televisions, plus computers and other electronic equipment which amounted to almost 80-90 tonnes of goods. This is the equivalent of 8-9 weeks of television drop-offs at the City’s resource recovery centres. Clean Up Australia Day 2013 held in March also helped to clean up our local environment and attracted 185 volunteers to 22 sites.
The state-wide Sustainable Living Festival was a great success in February featuring 46 local events run by community groups and small businesses around Geelong. Local events included food swaps, workshops, film nights, and garden tours. The City, through its Future Proofing Geelong initiative also presented international key note speaker Jason Roberts, founder of the ‘Better Block’ – a form of community led action to make for more a more sustainable environment.
There are several actions under the Sustainable Built and Natural Environment Strategic Direction within City Plan that aim to increase the use of public and active transport within the municipality, reduce the organisation’s environmental footprint, enhance and protect our natural areas, and develop a Climate Change Adaptation Strategy.
The City’s Annual Budget provides the Resource Plan to support the initiatives identified within the adopted Annual Business Plan.
The City’s external auditors will undertake a Performance Audit of the planned Key Strategic Activities and prepare a report as part of the ‘sign off’ of the Annual Accounts.
There is no conflict of interest to be disclosed.
The risks arising from the Actions are managed within the framework of the City’s adopted Policies, Procedures and Risk Management strategies.
Several of the actions identified within City Plan are aimed at improving the quality of life for the residents in the City of Greater Geelong. This is particularly the case for actions within the Community Wellbeing Strategic Direction.
The outcomes arising from the Performance Audit will be published in the City’s Annual Report for 2012-2013 that will be submitted to the Minister for Local Government.
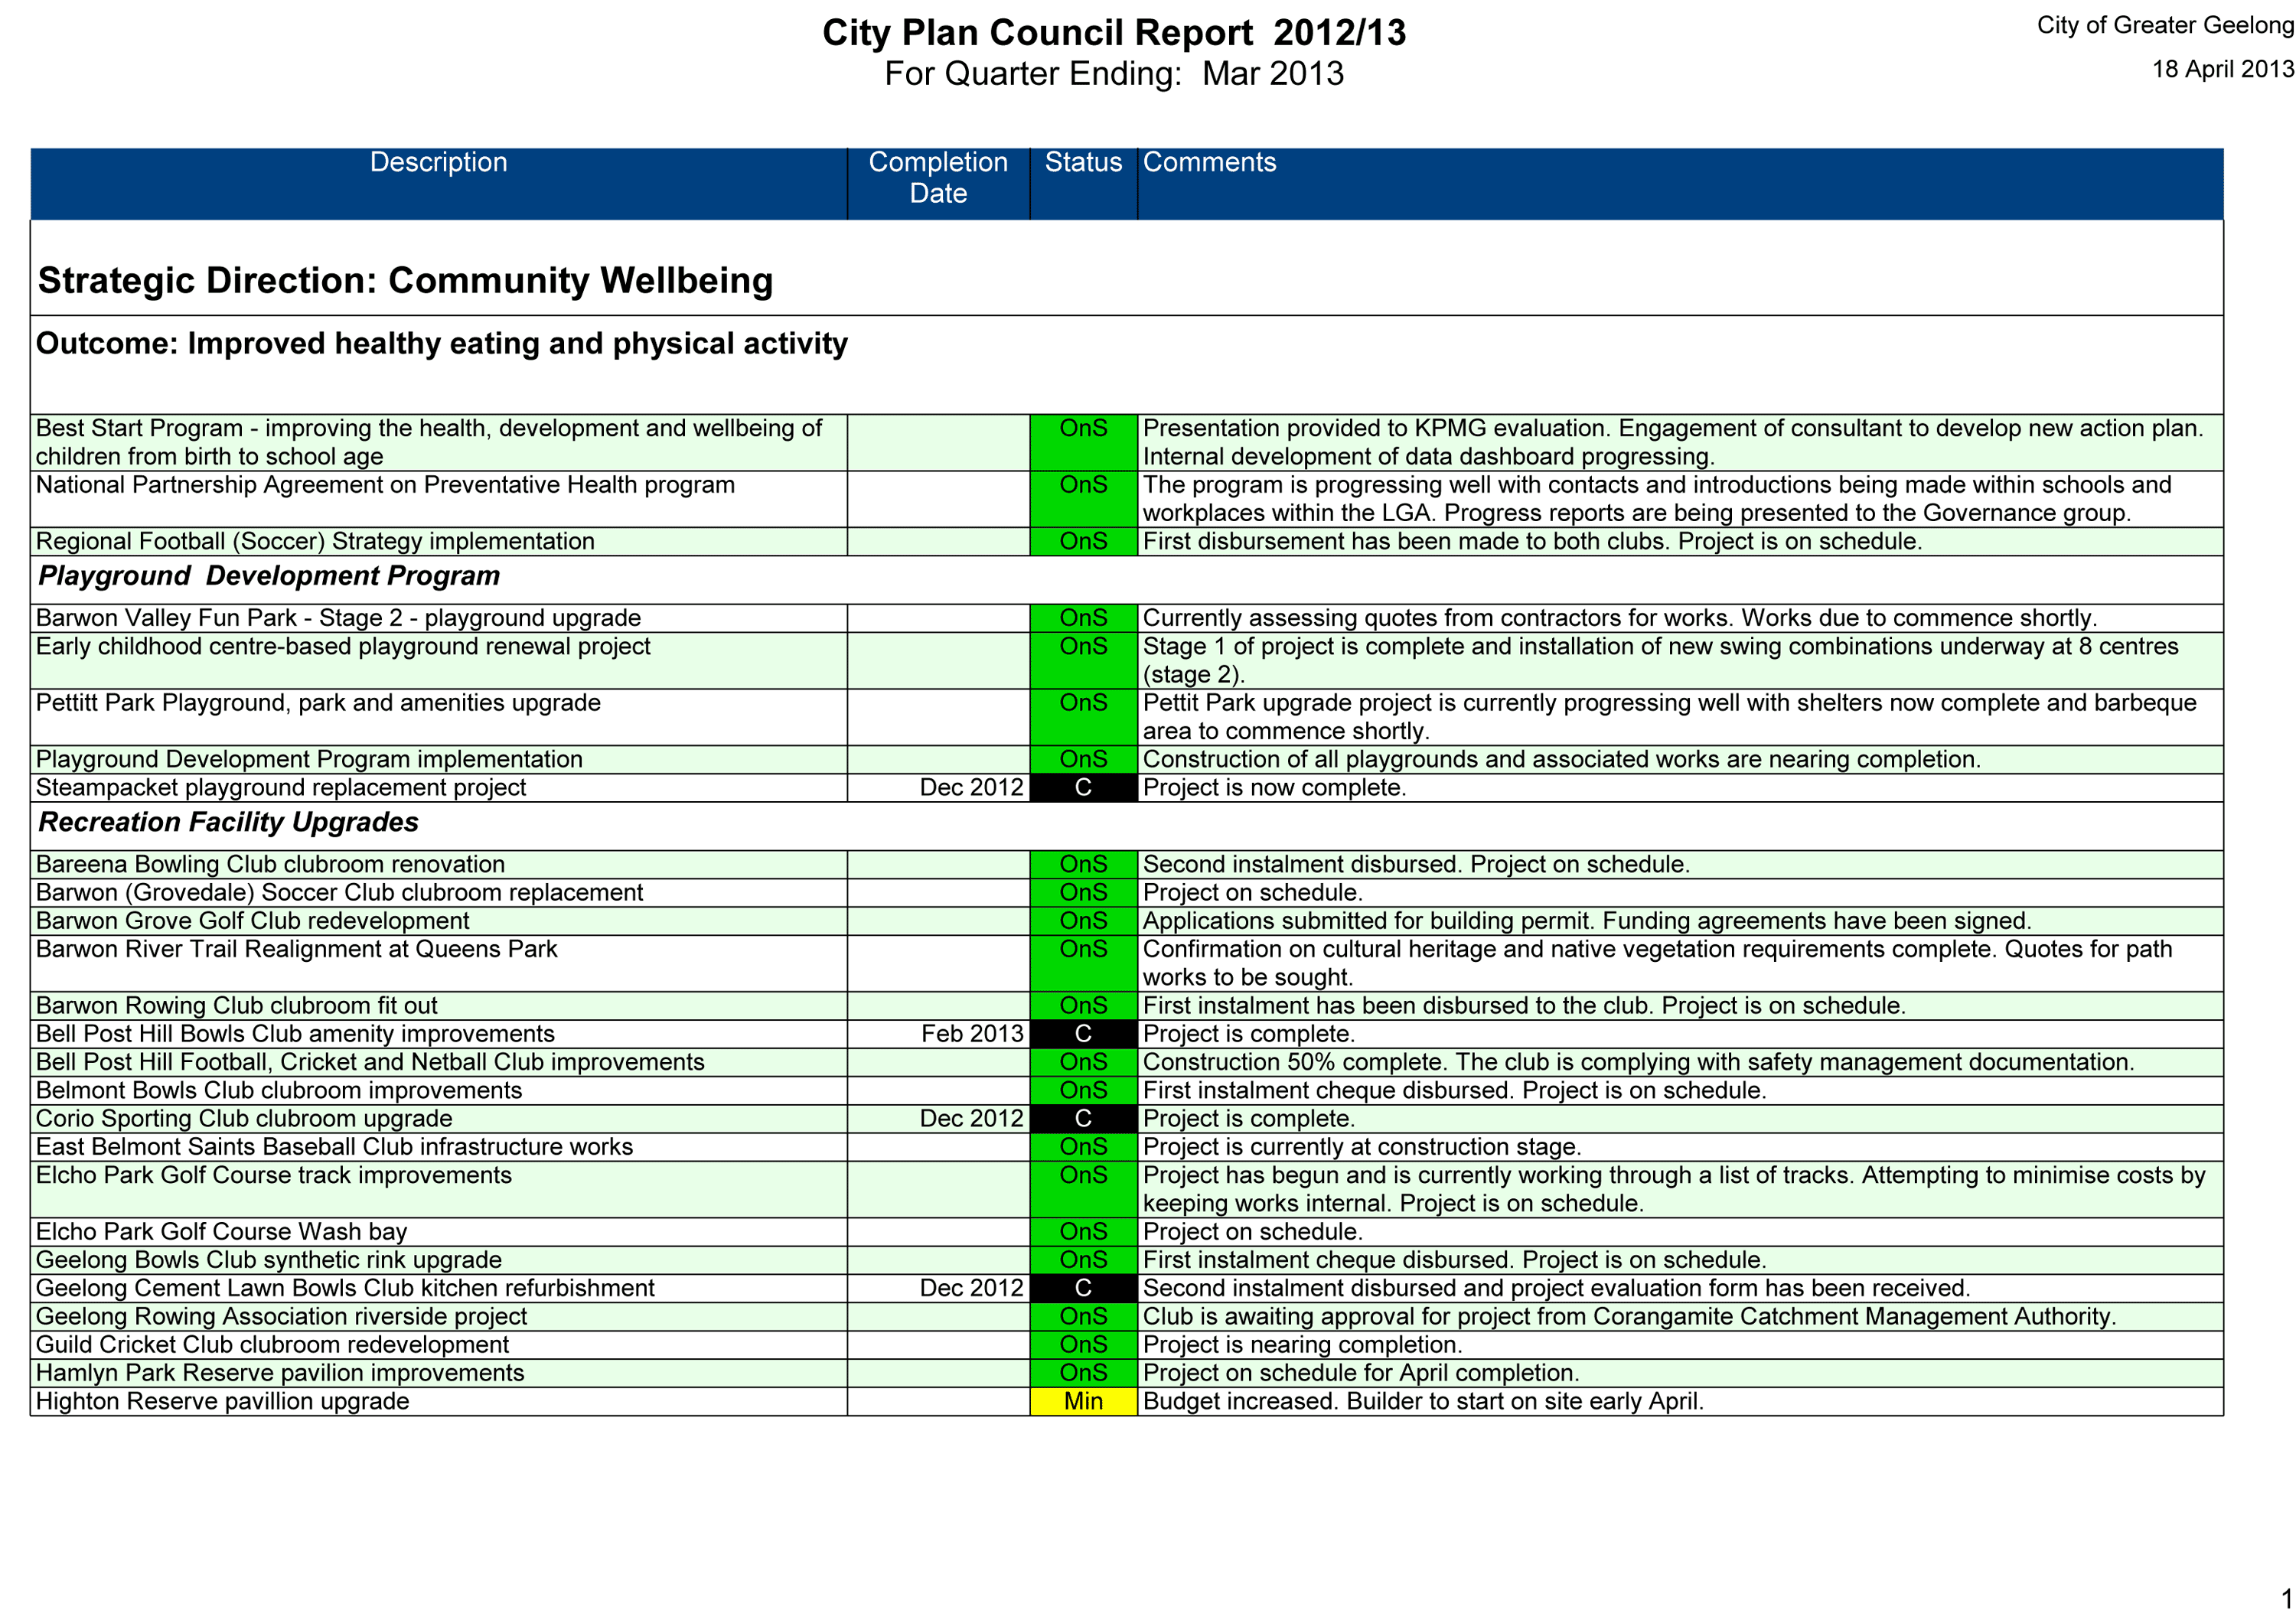
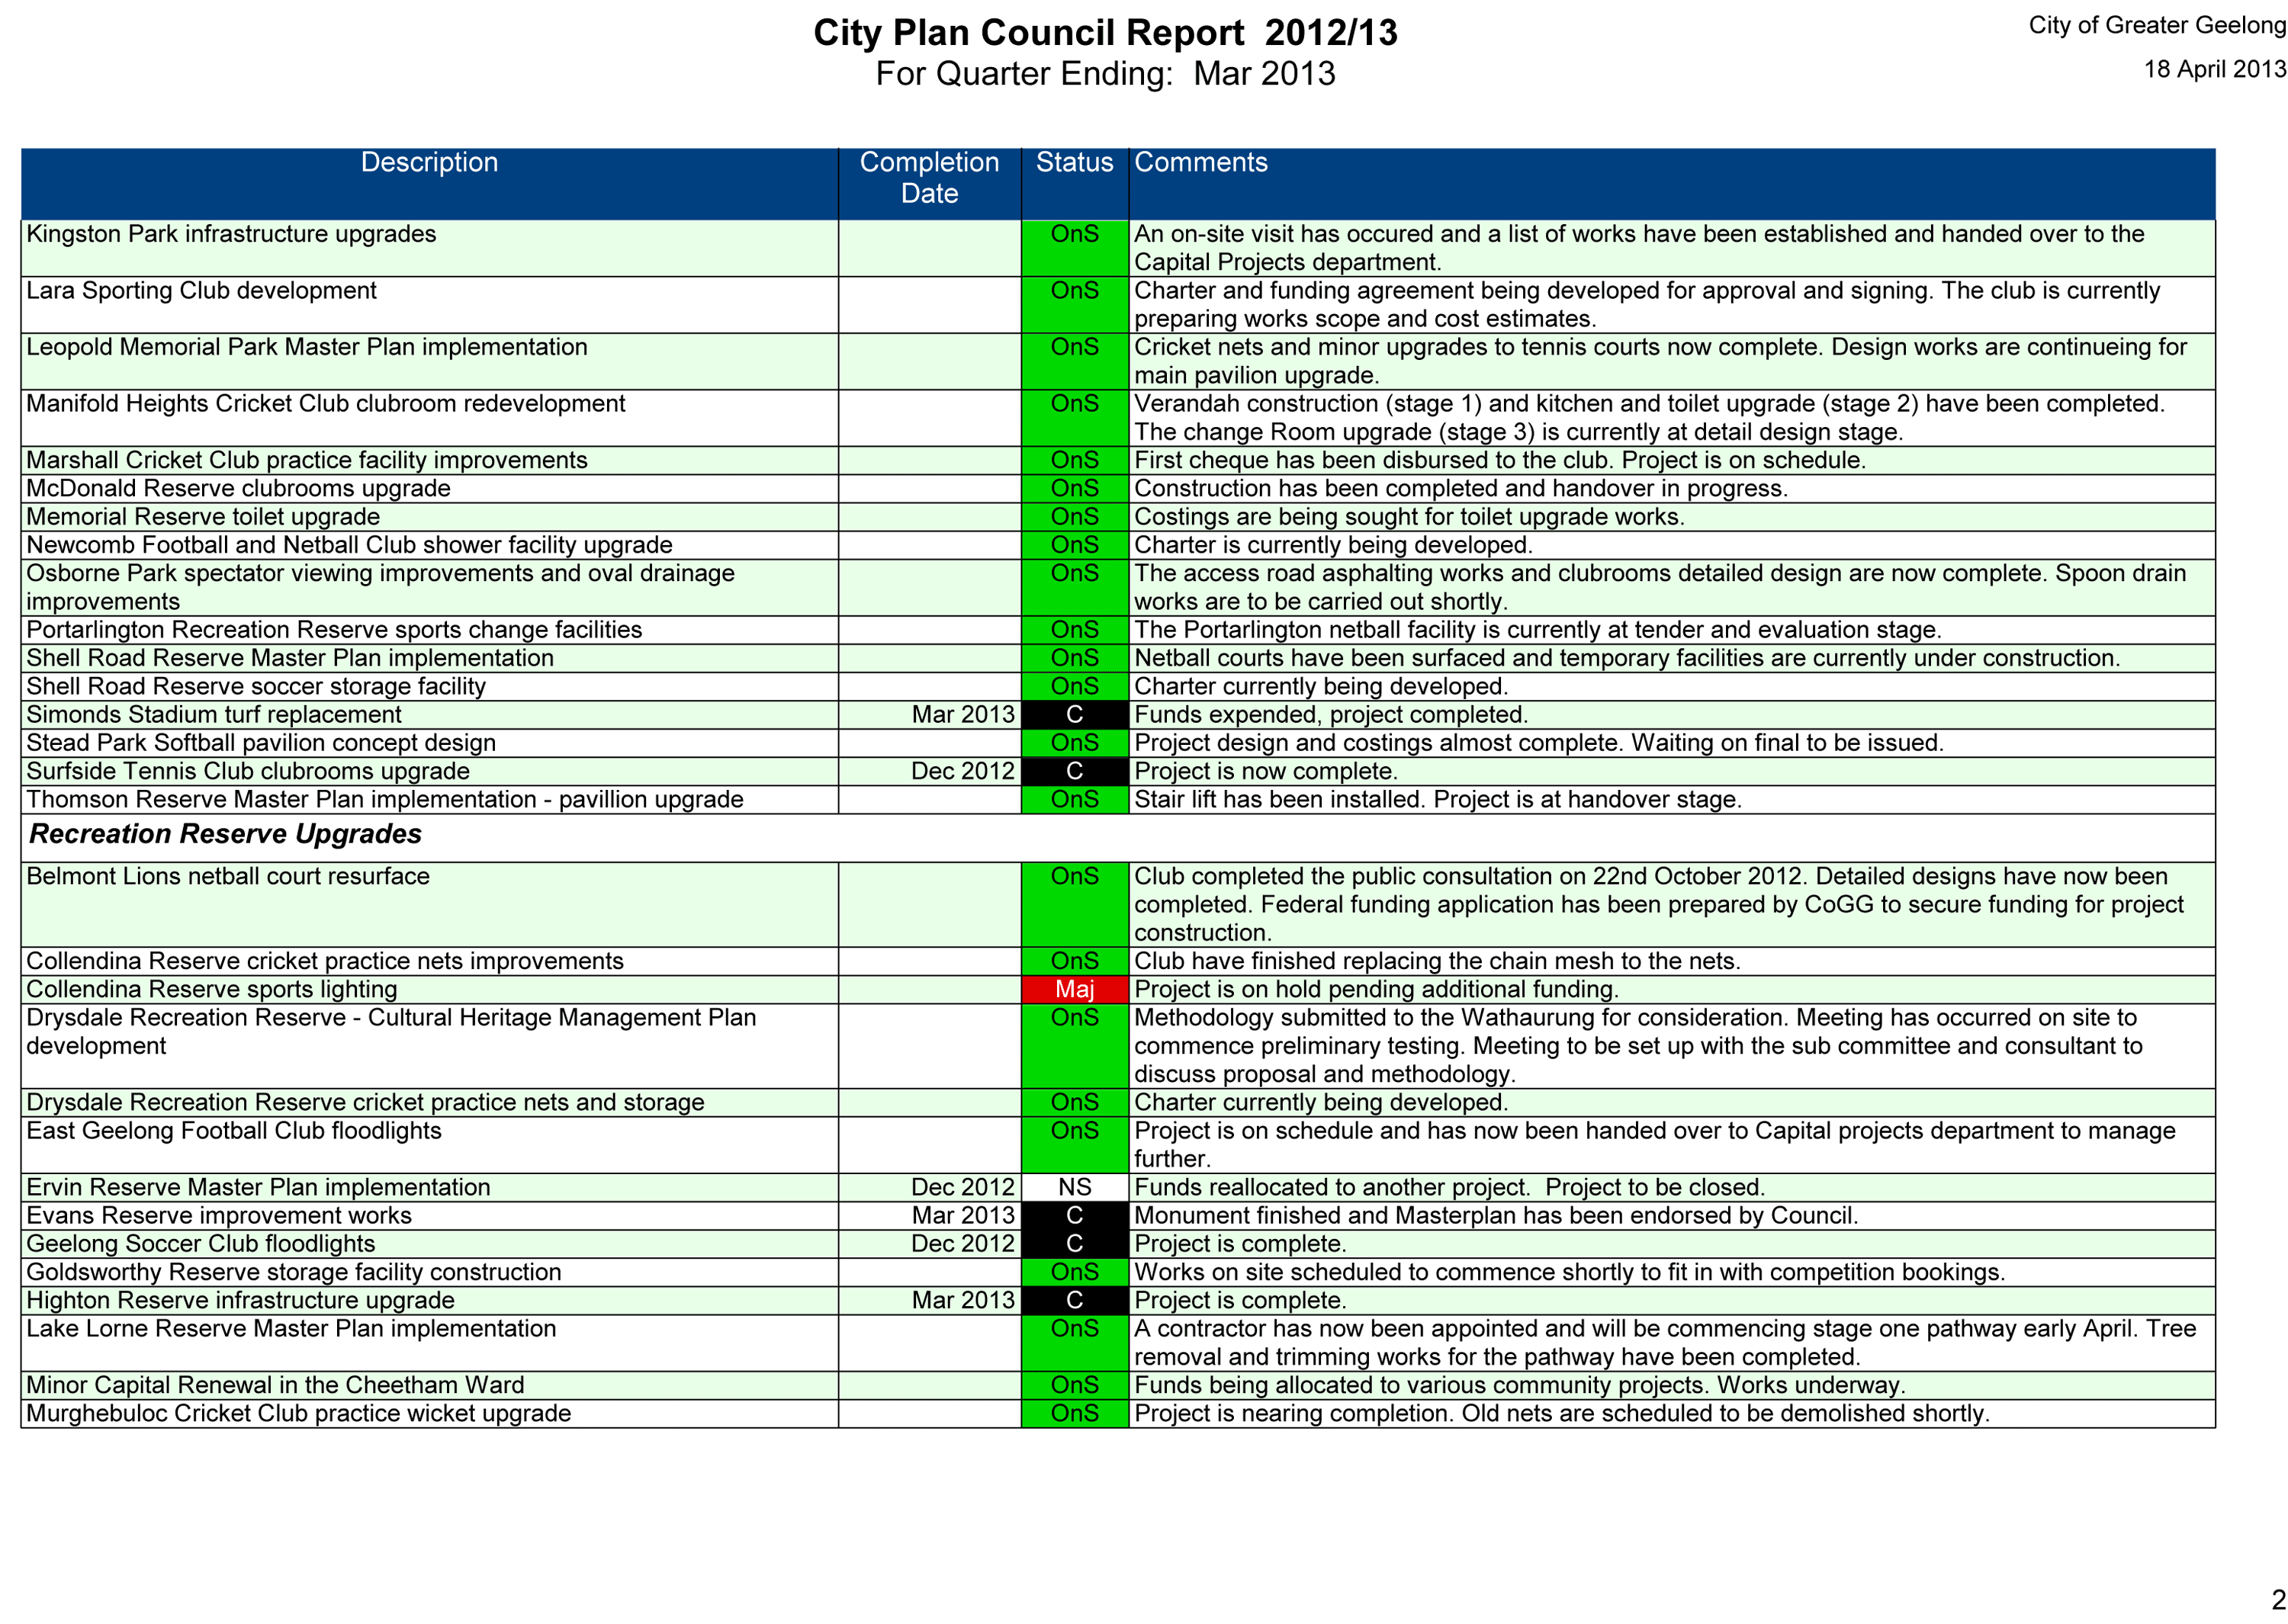
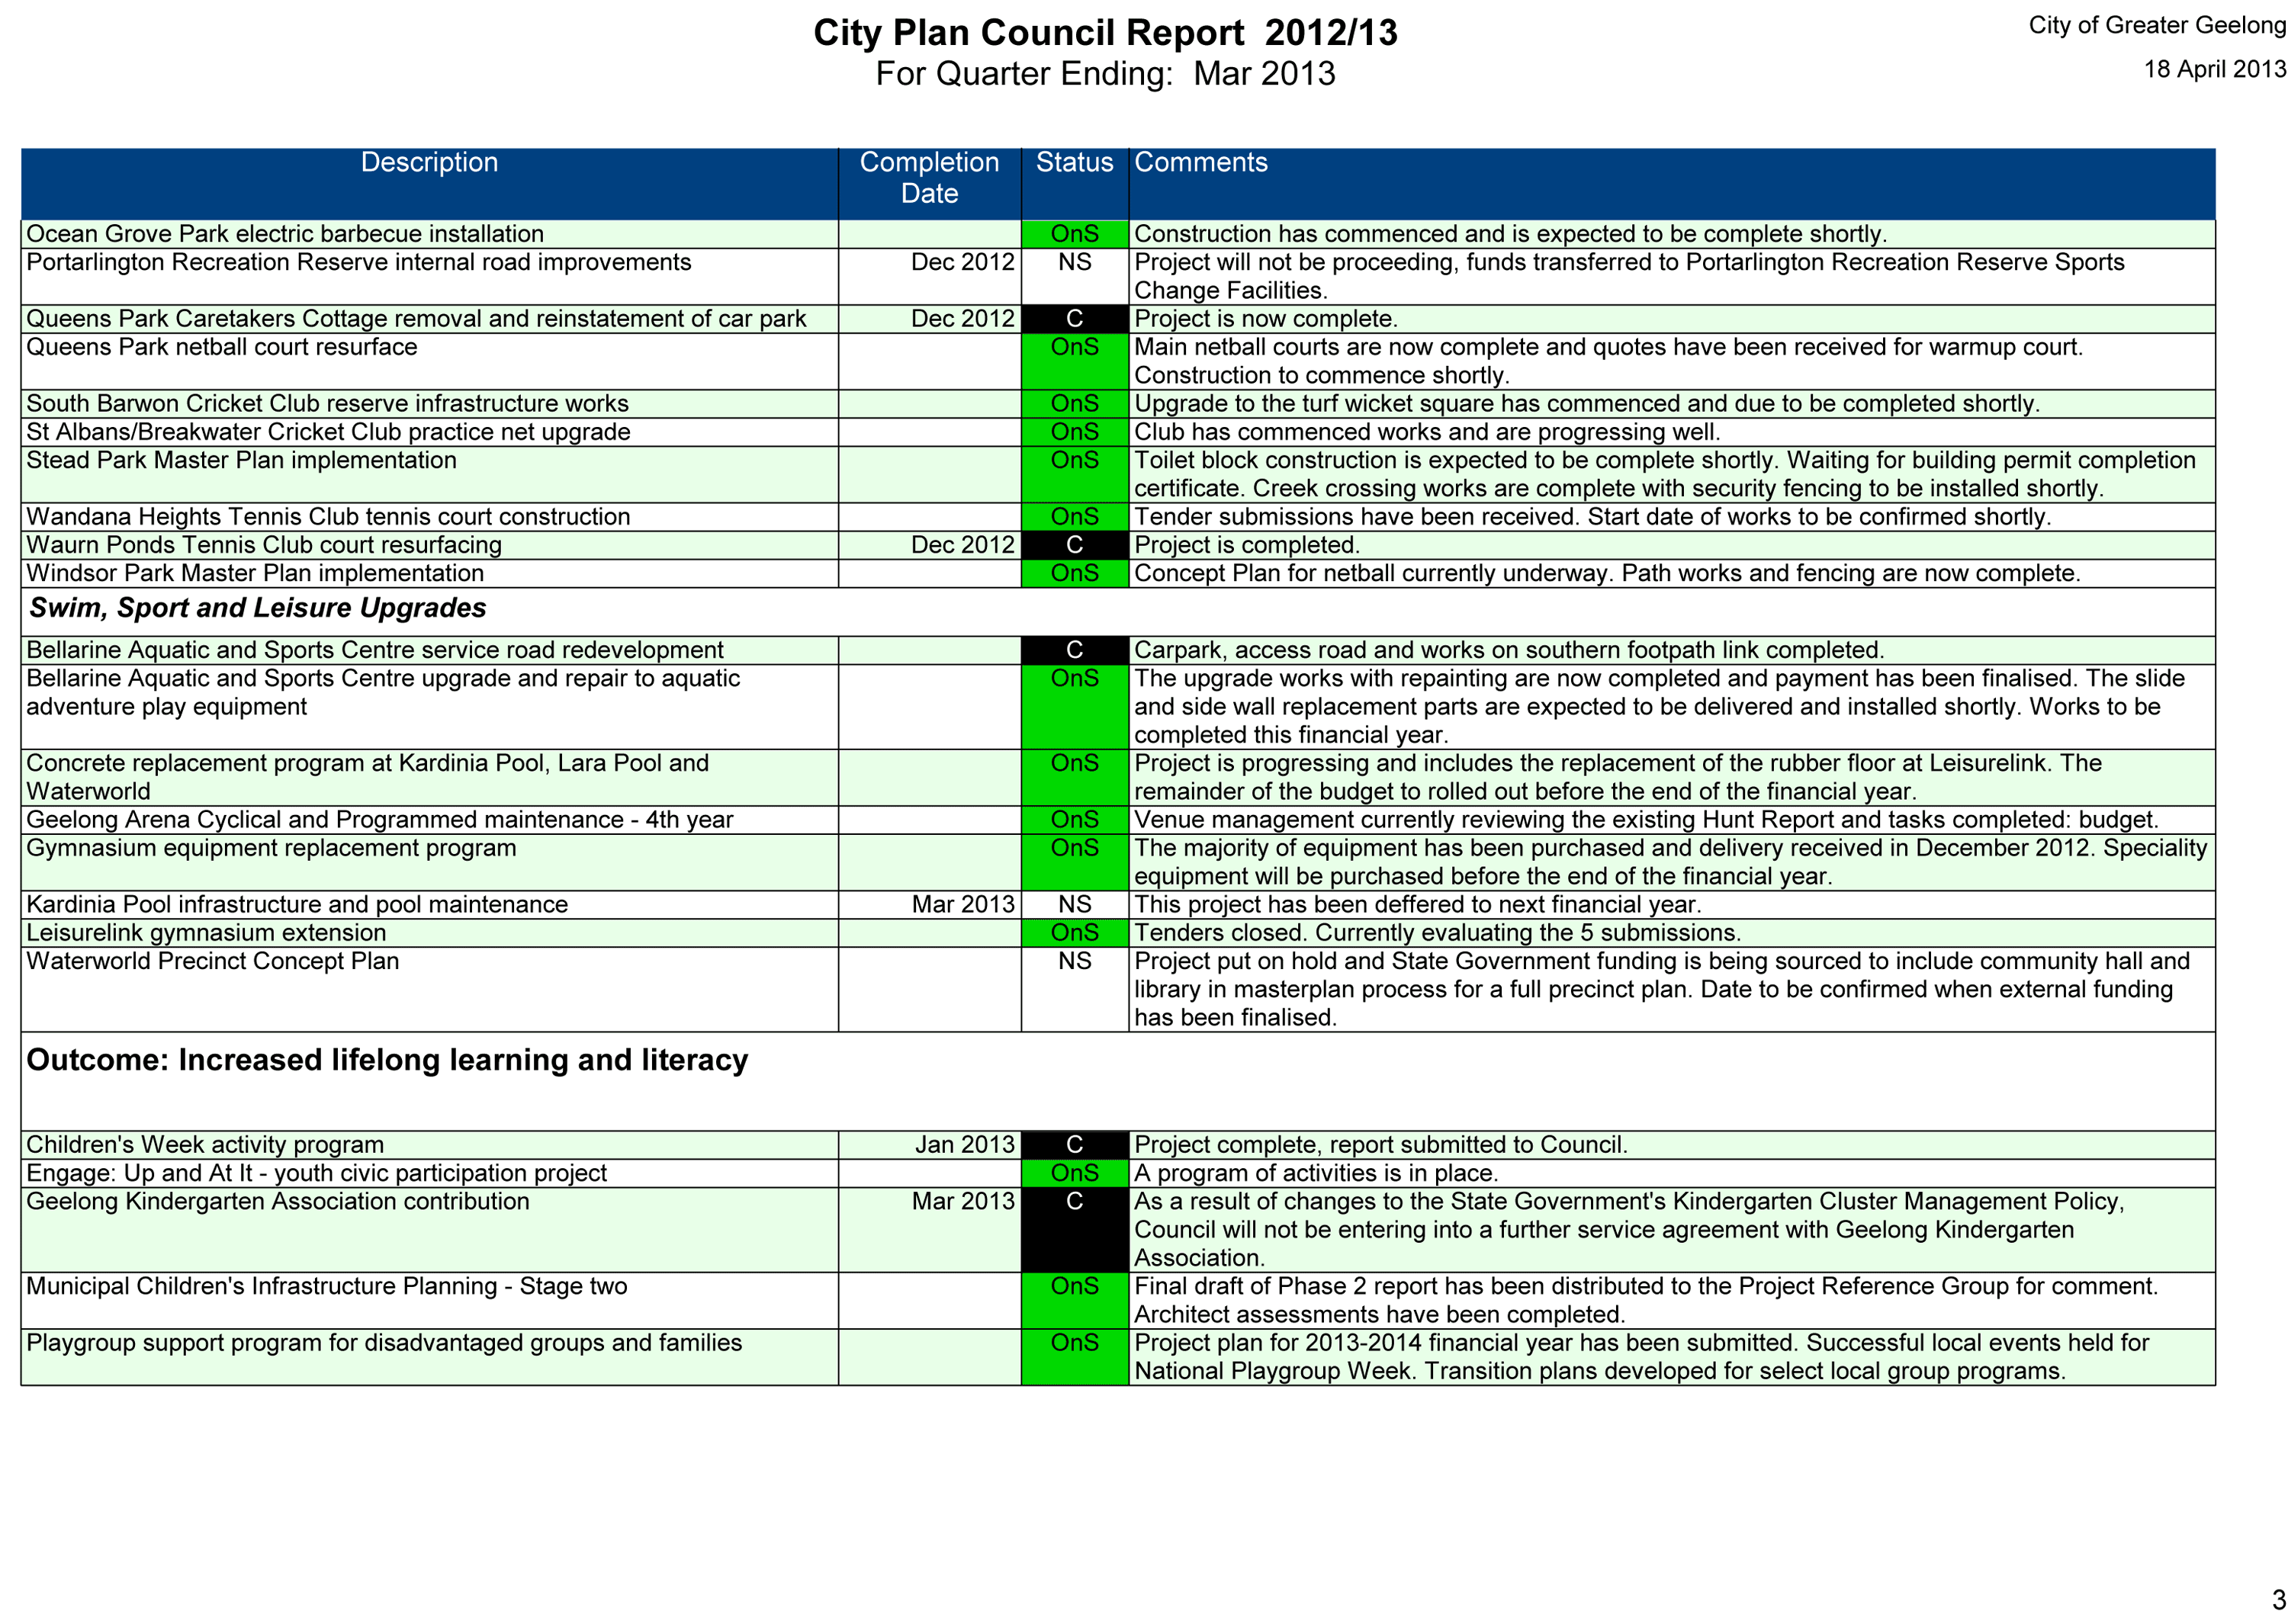
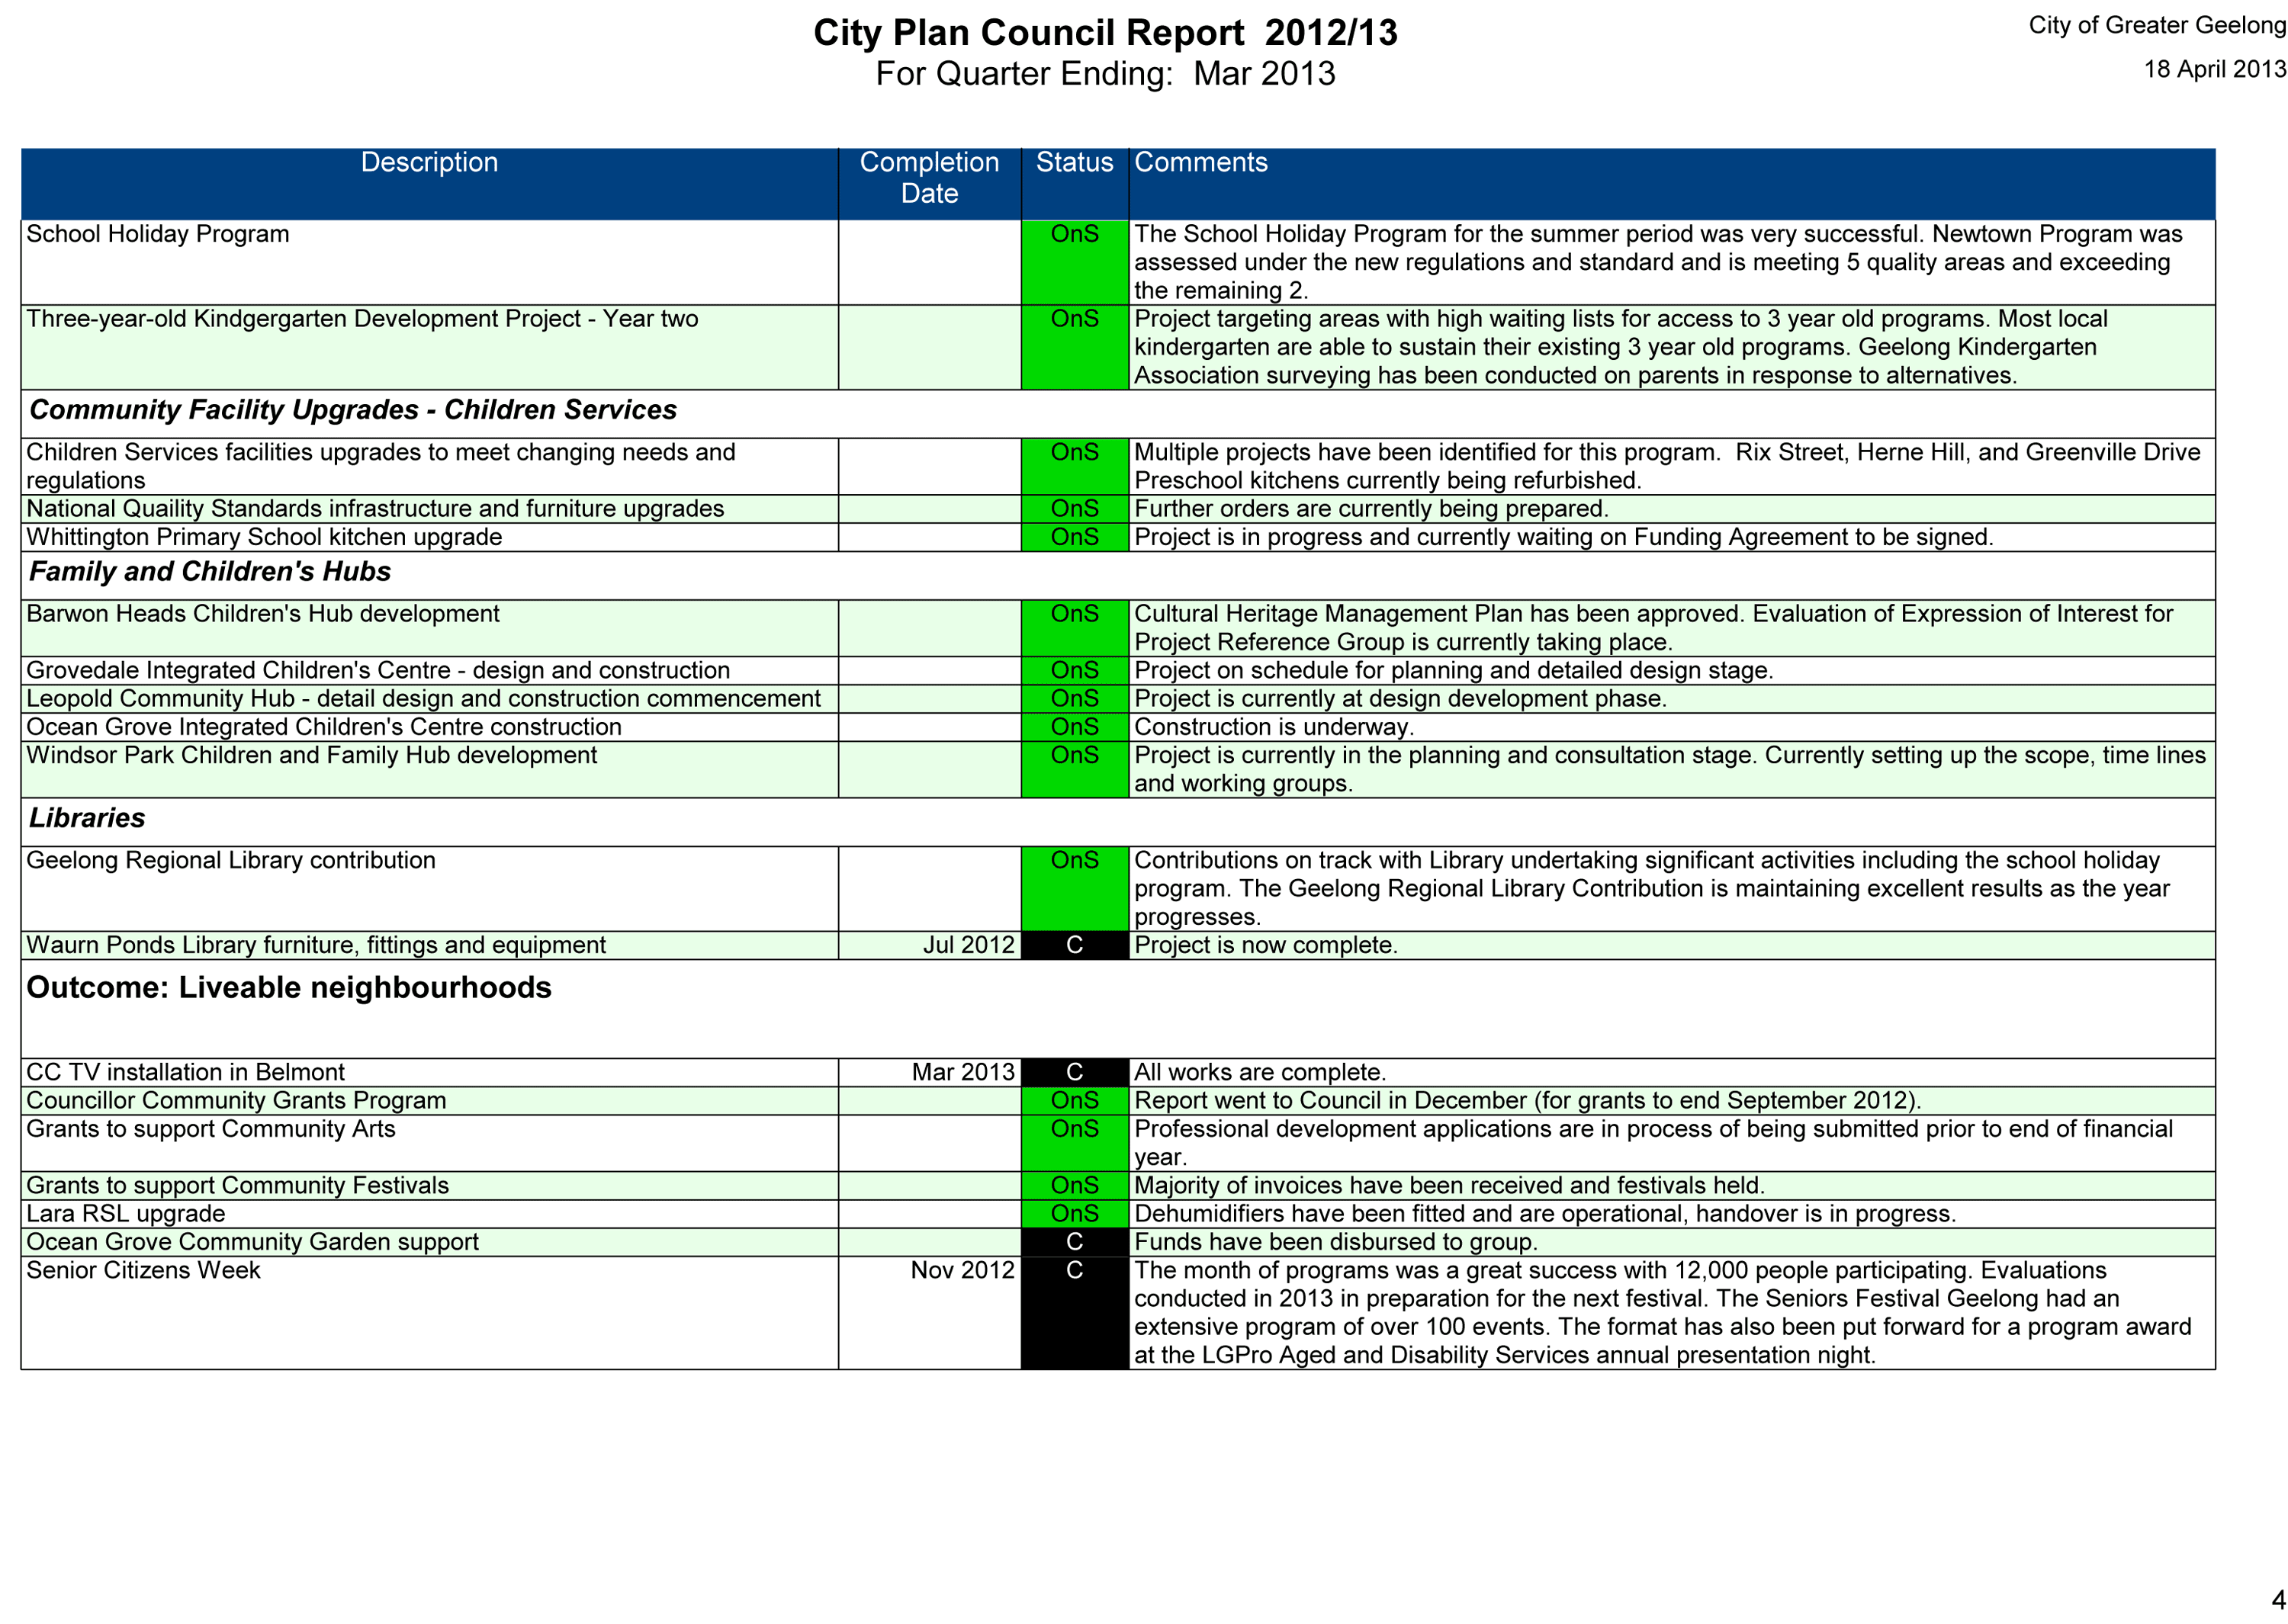
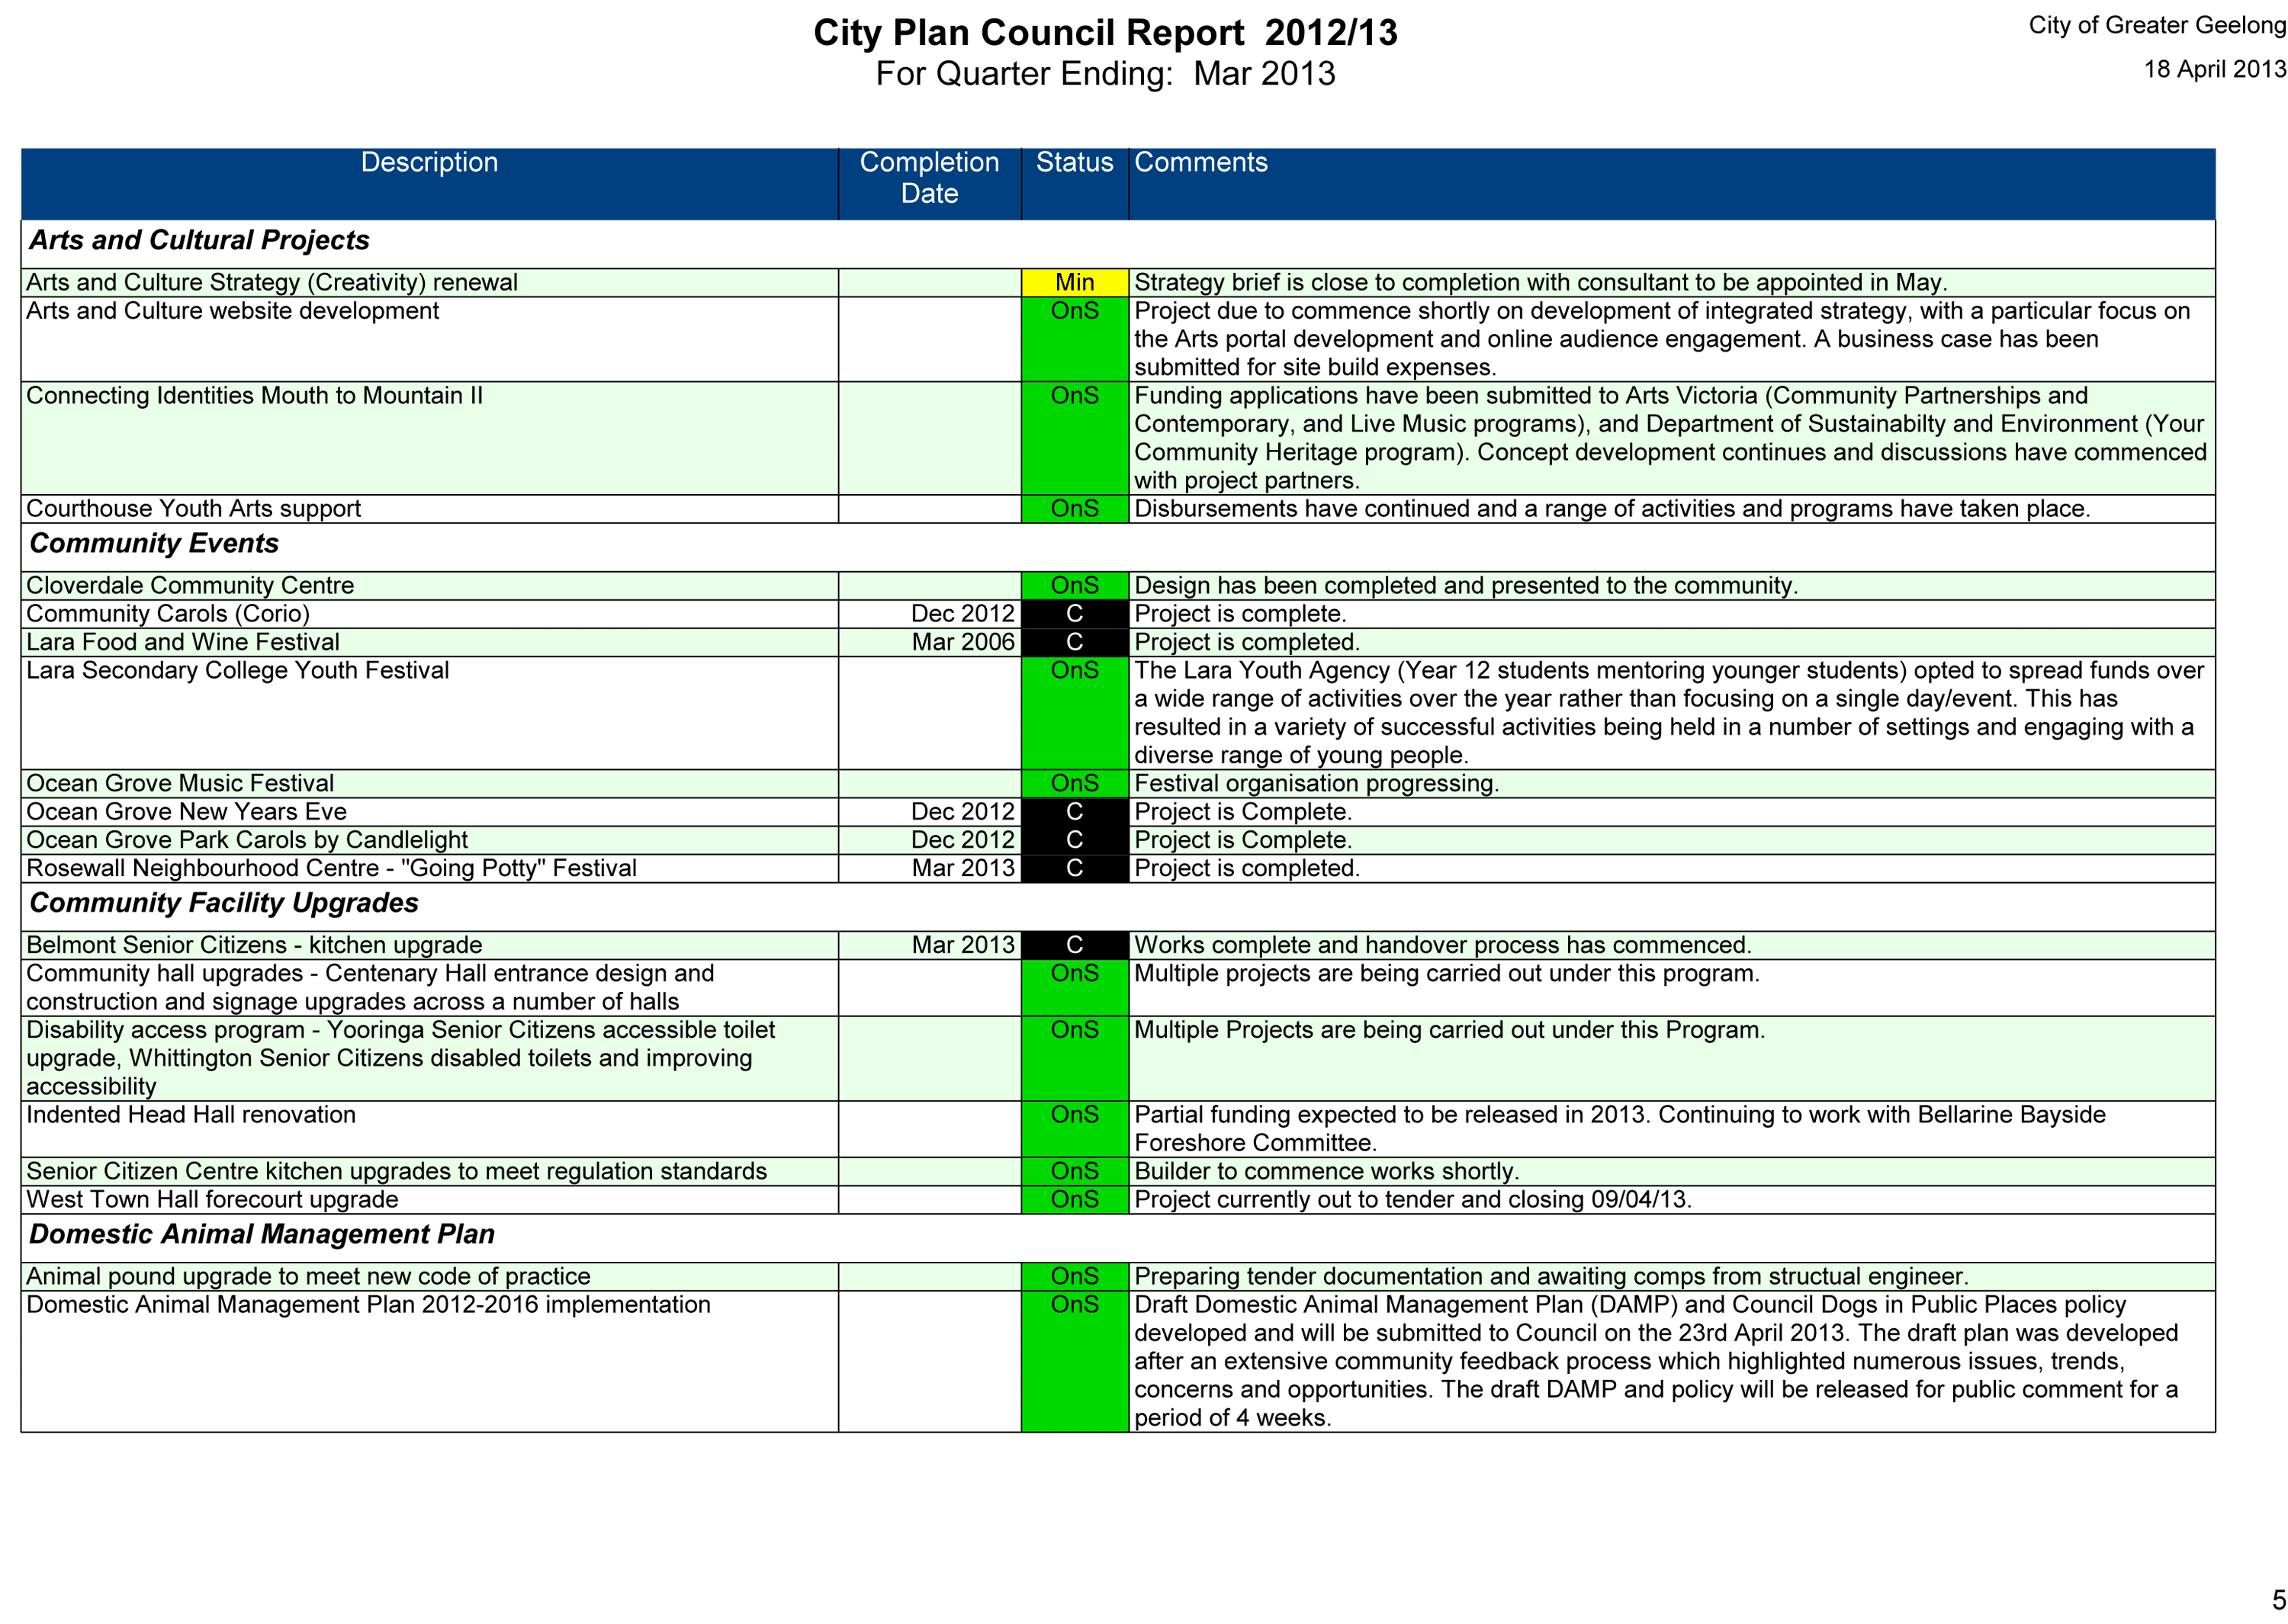
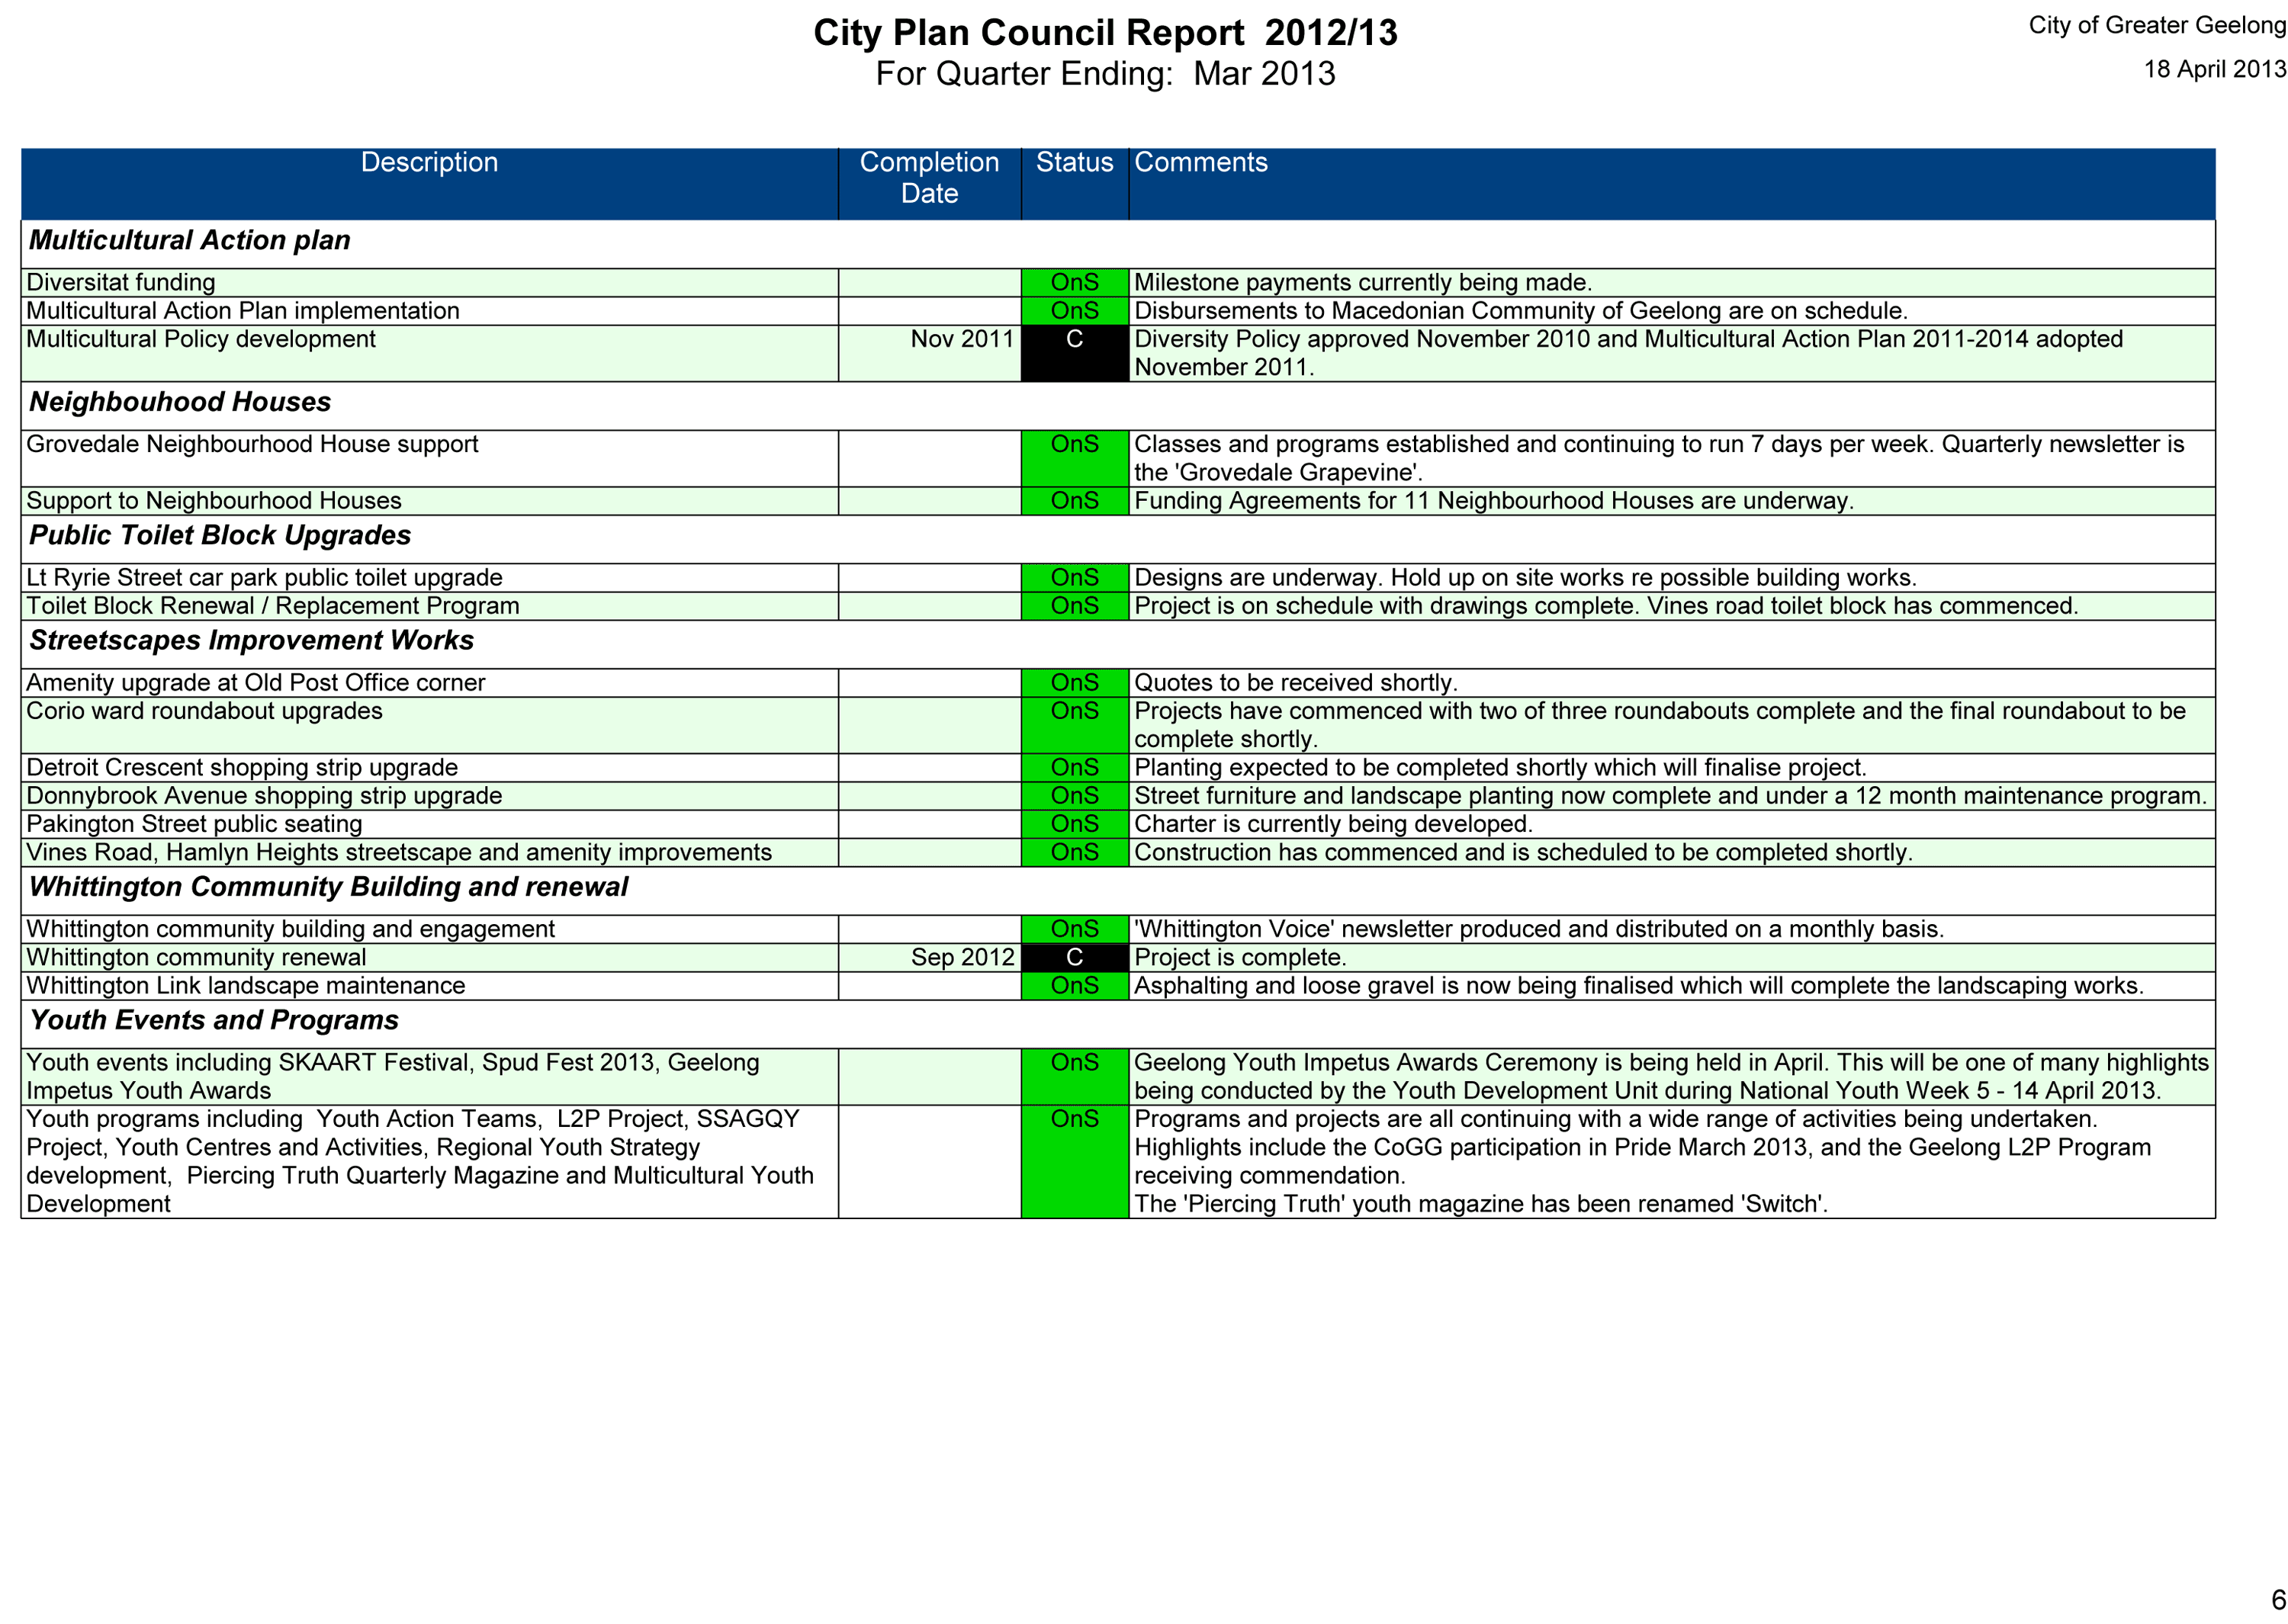
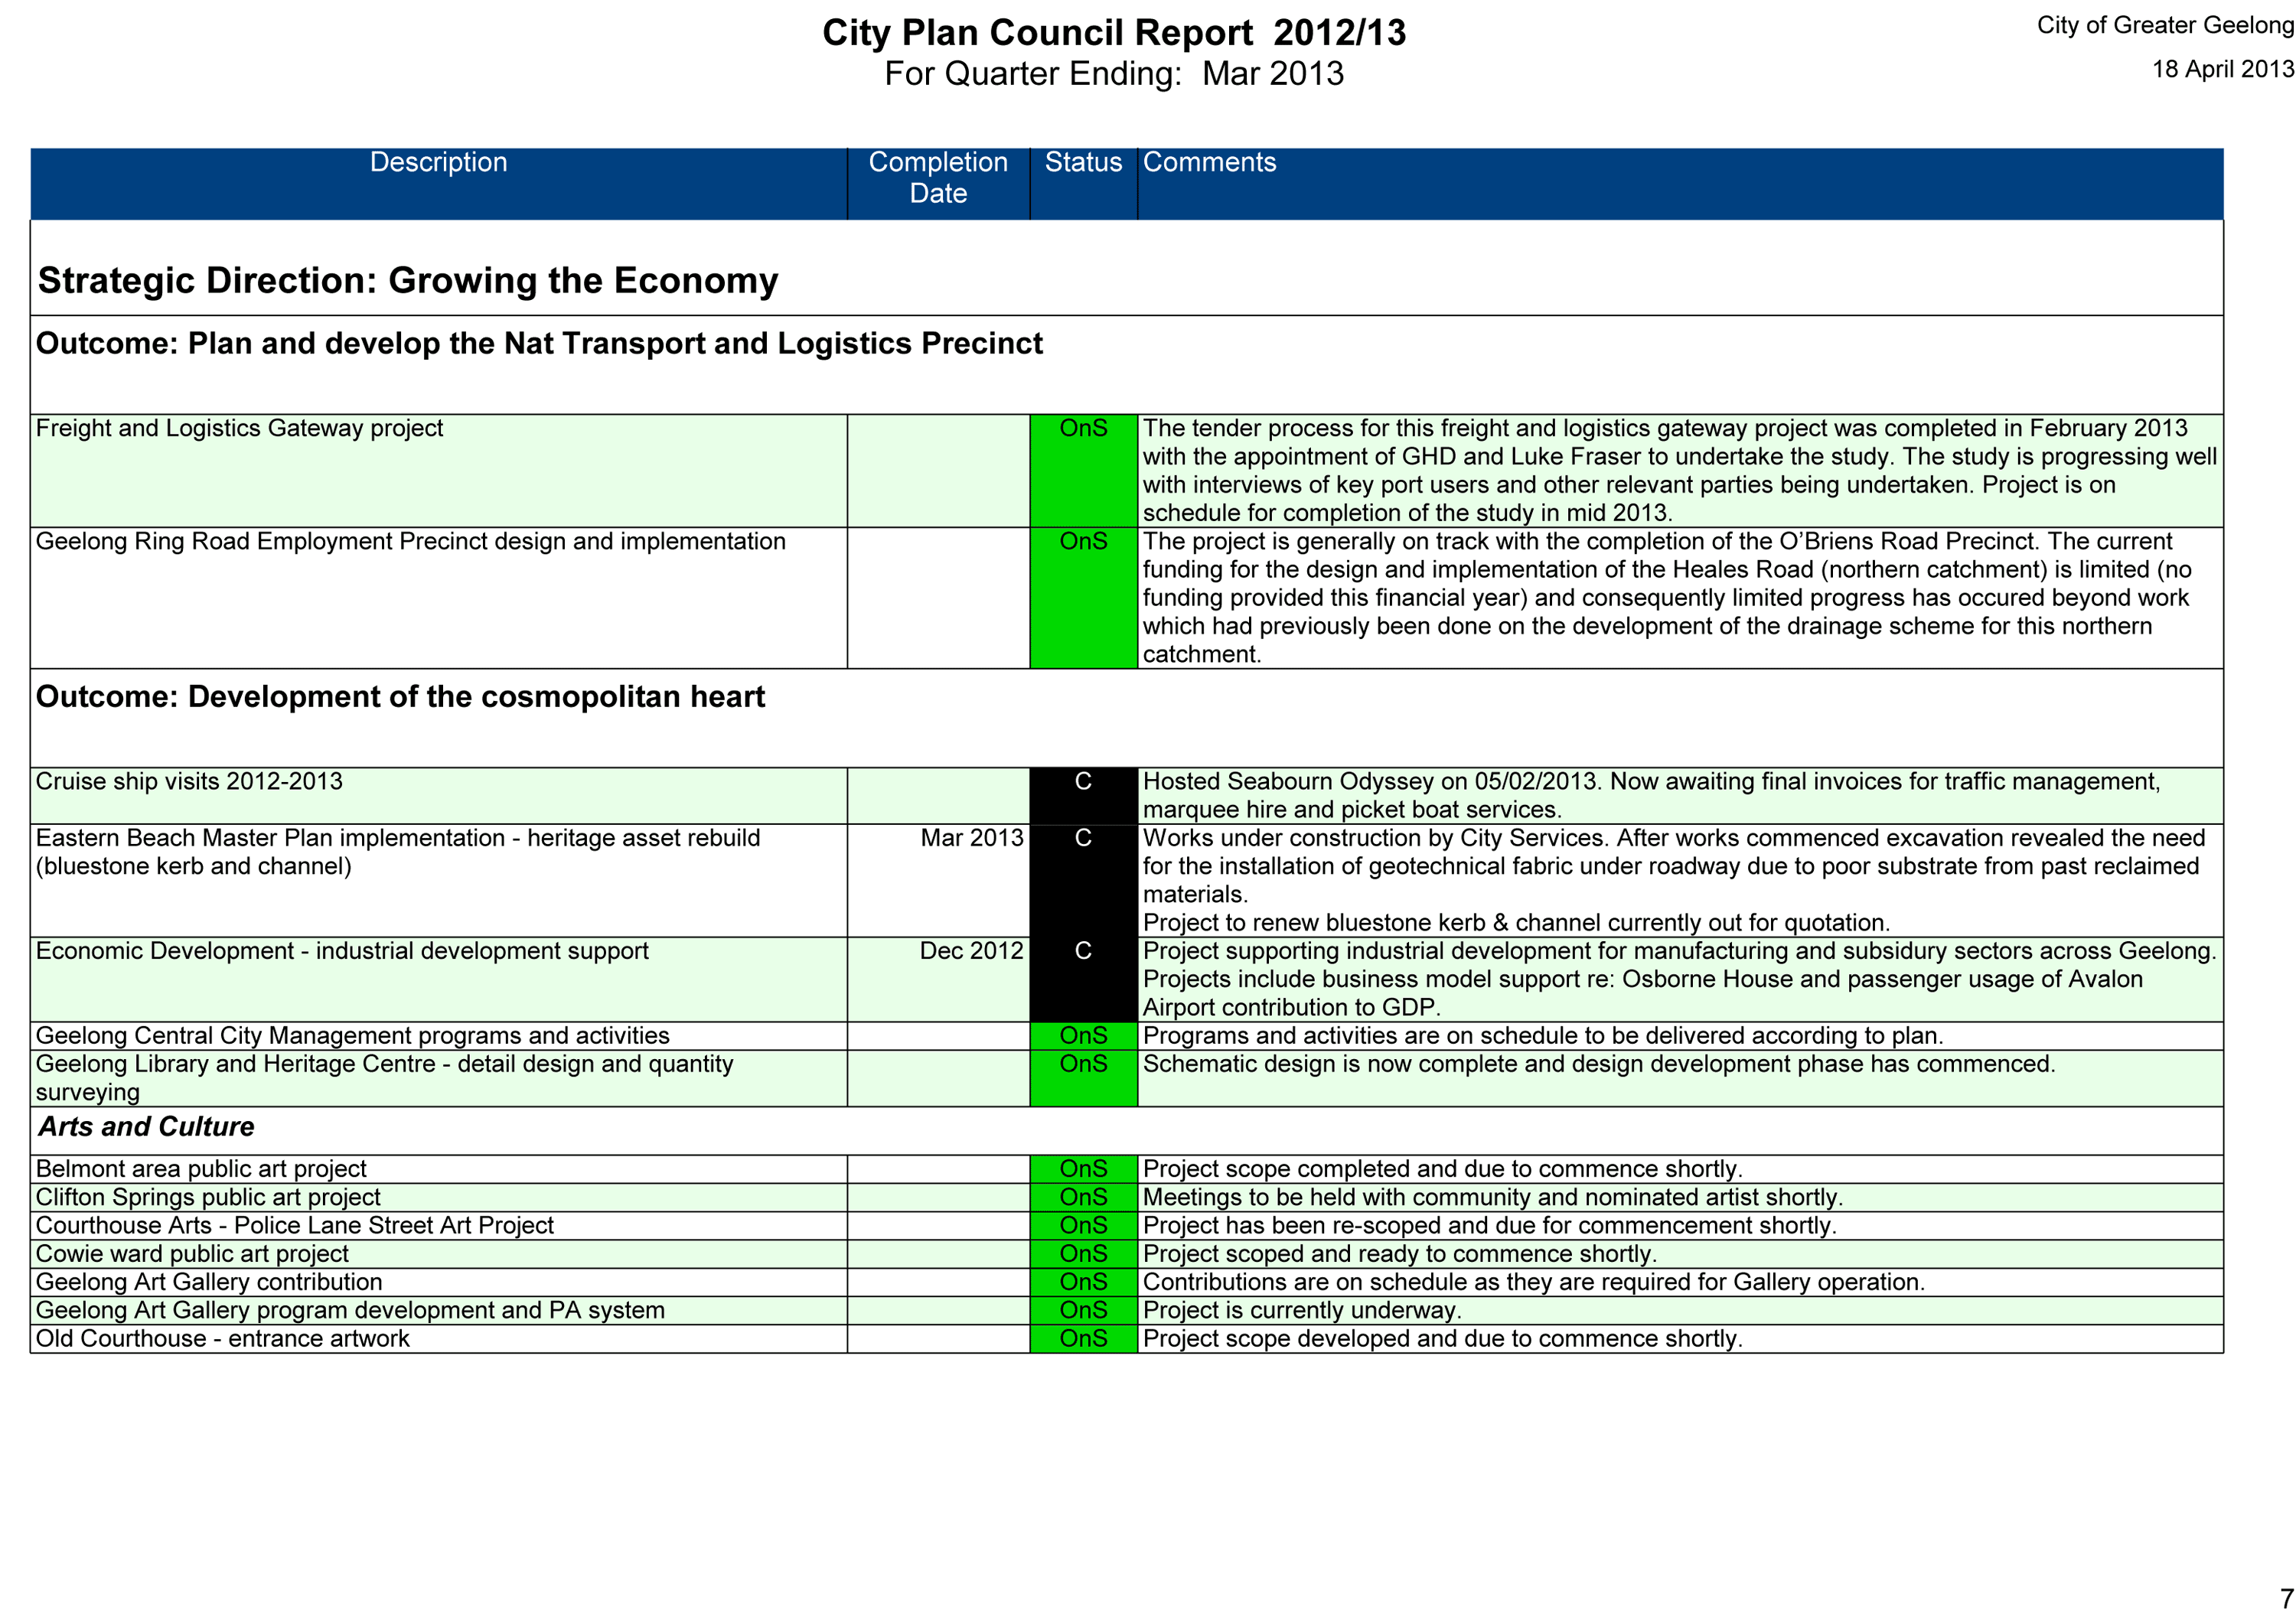
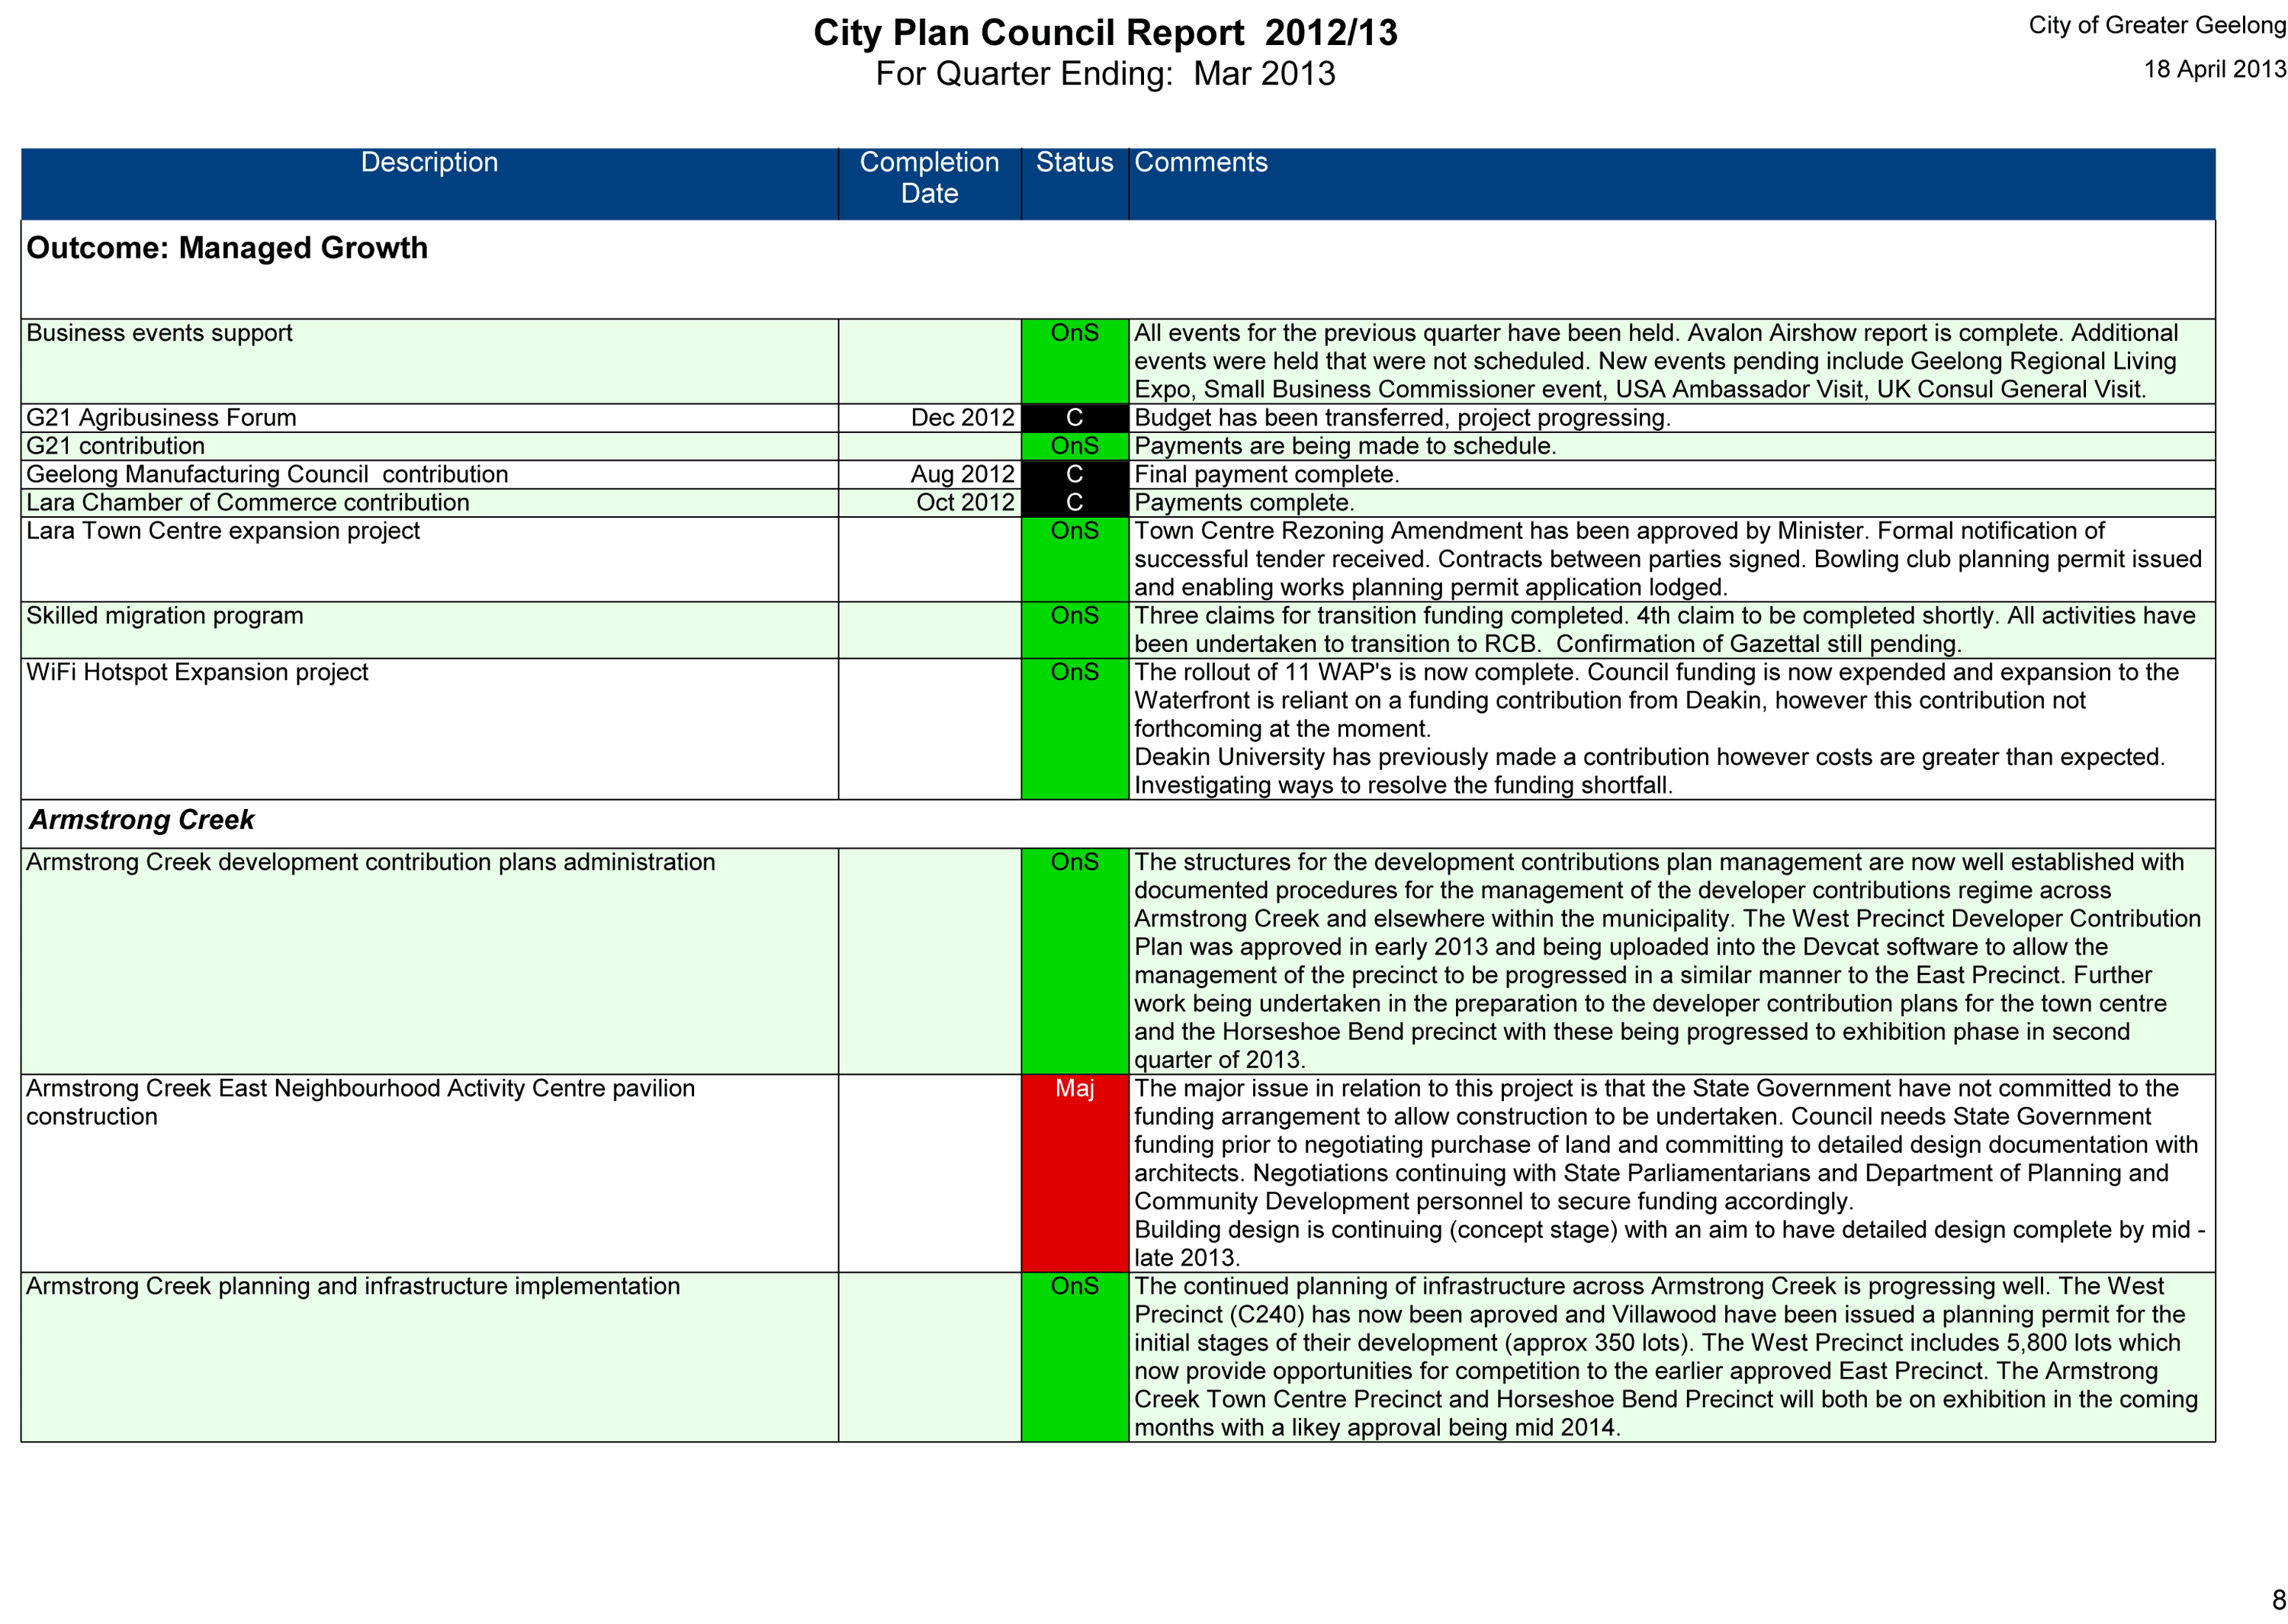
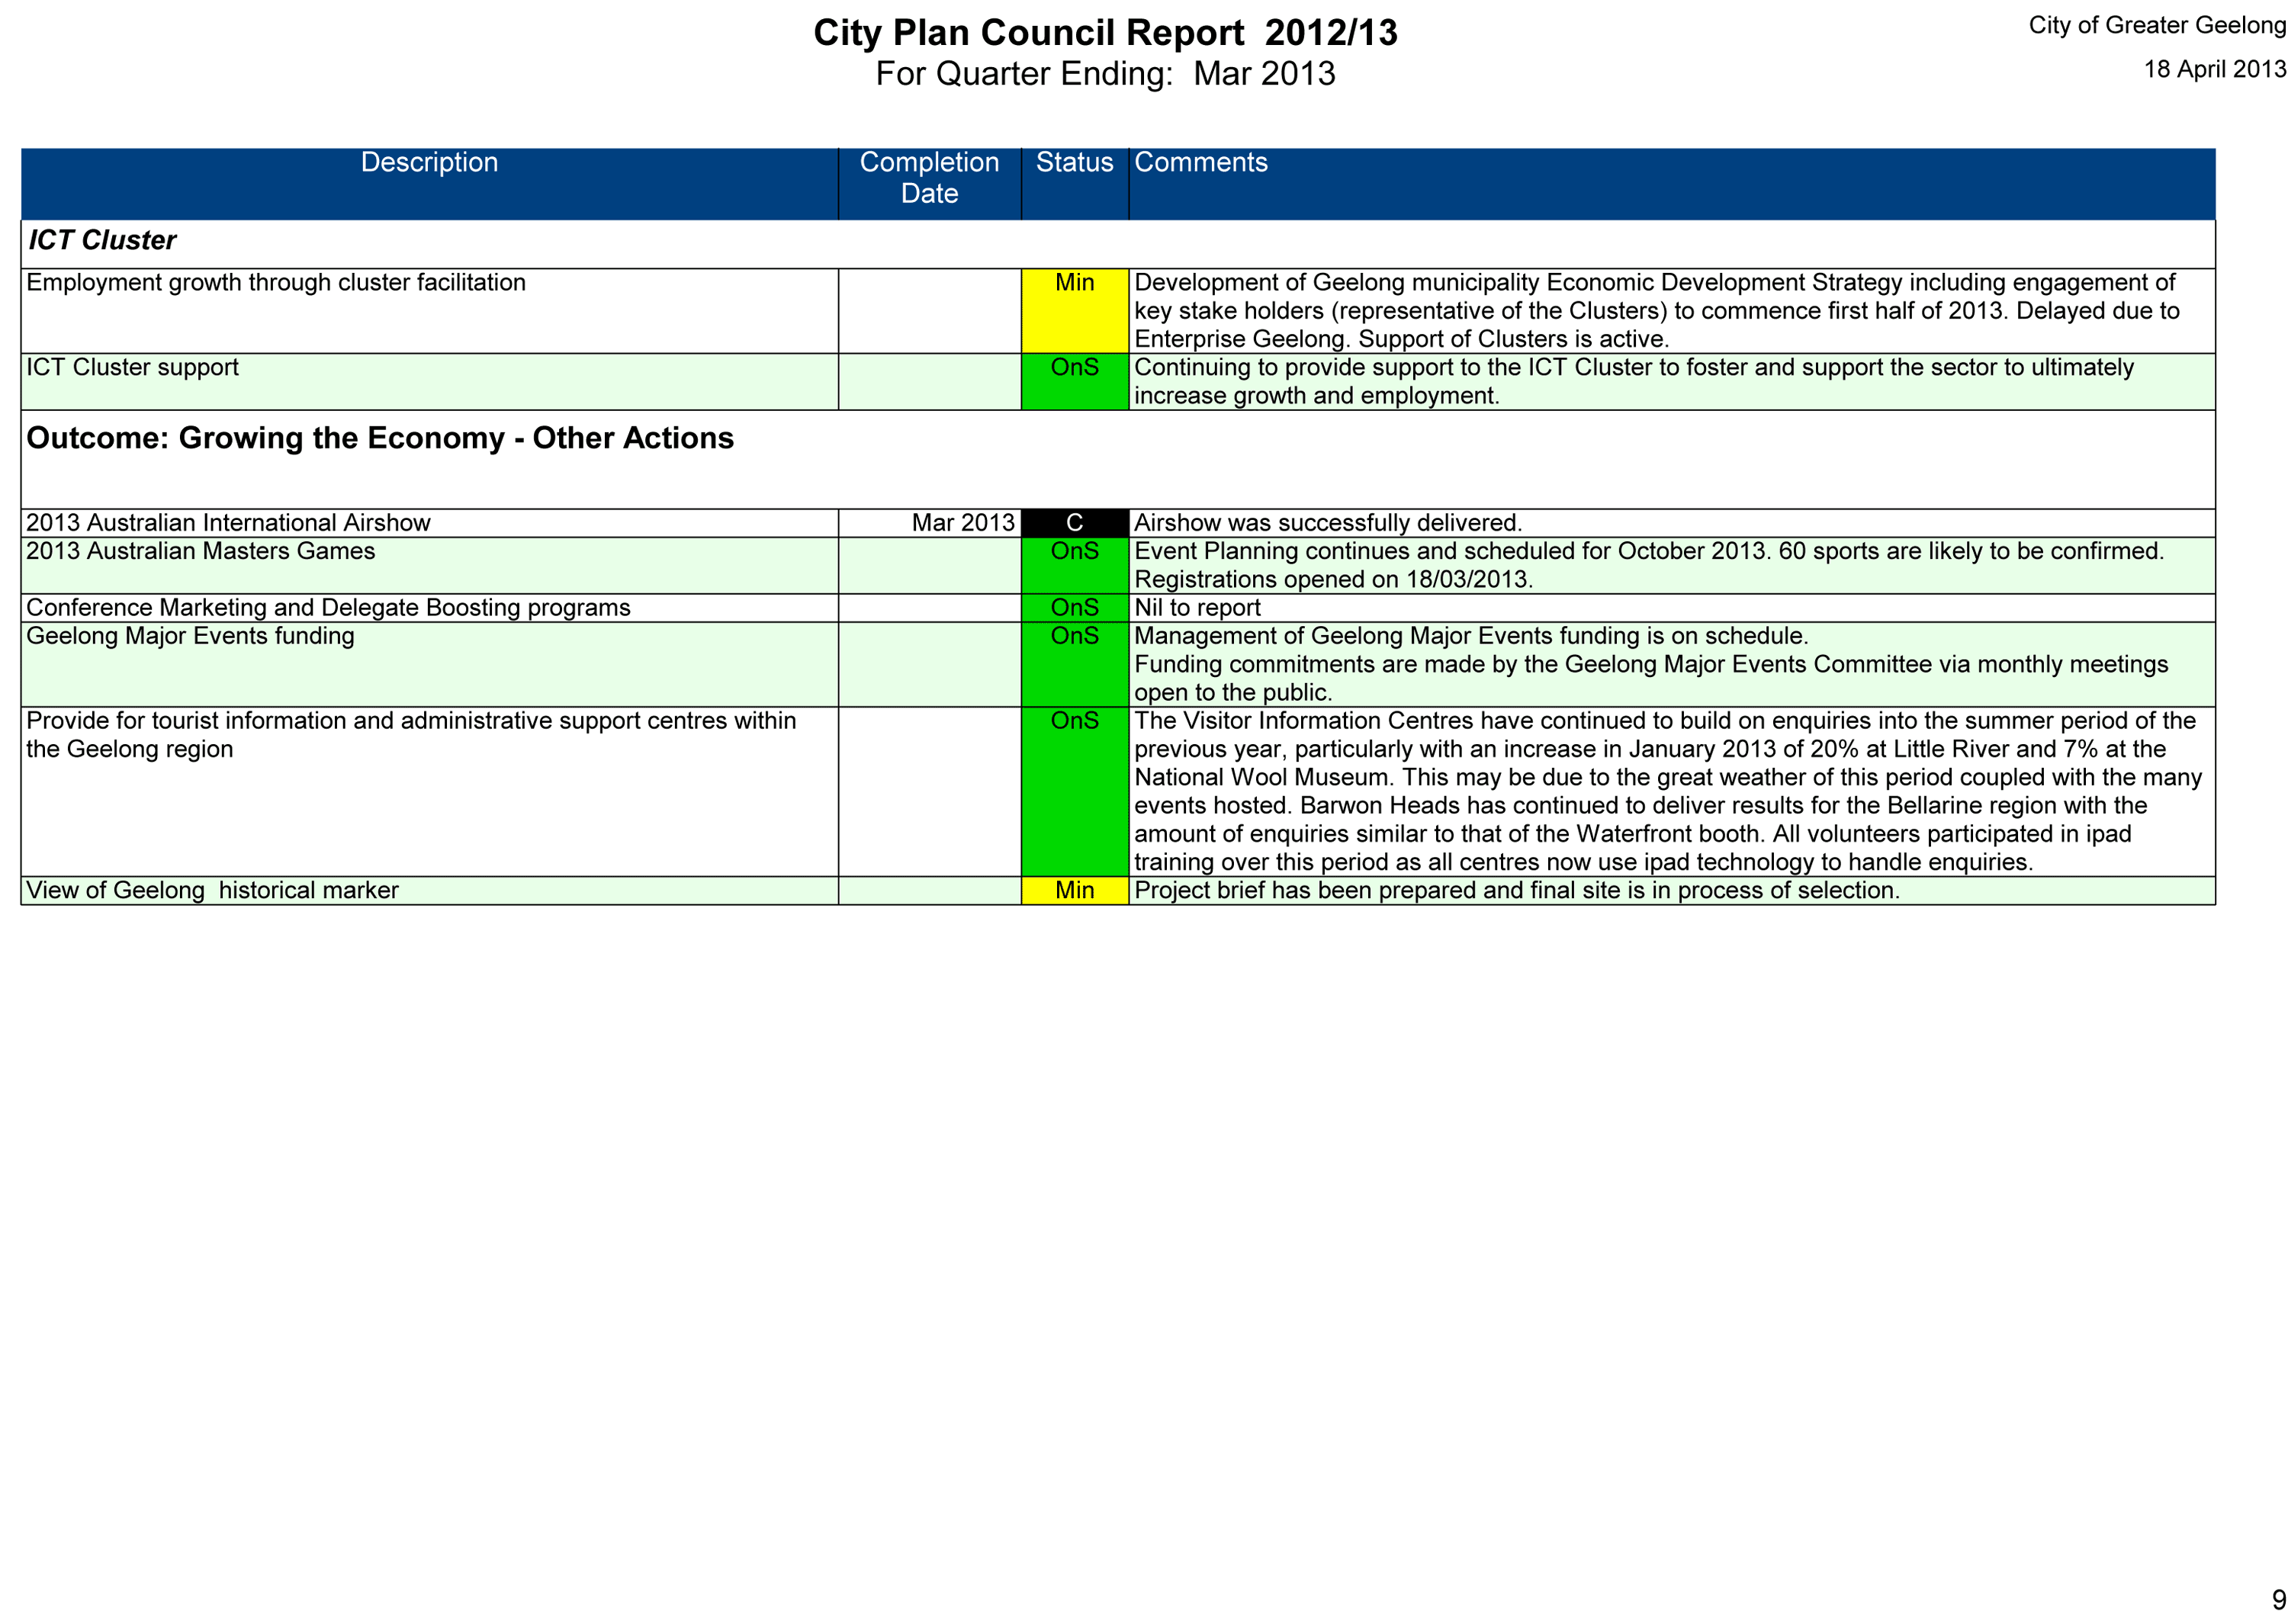
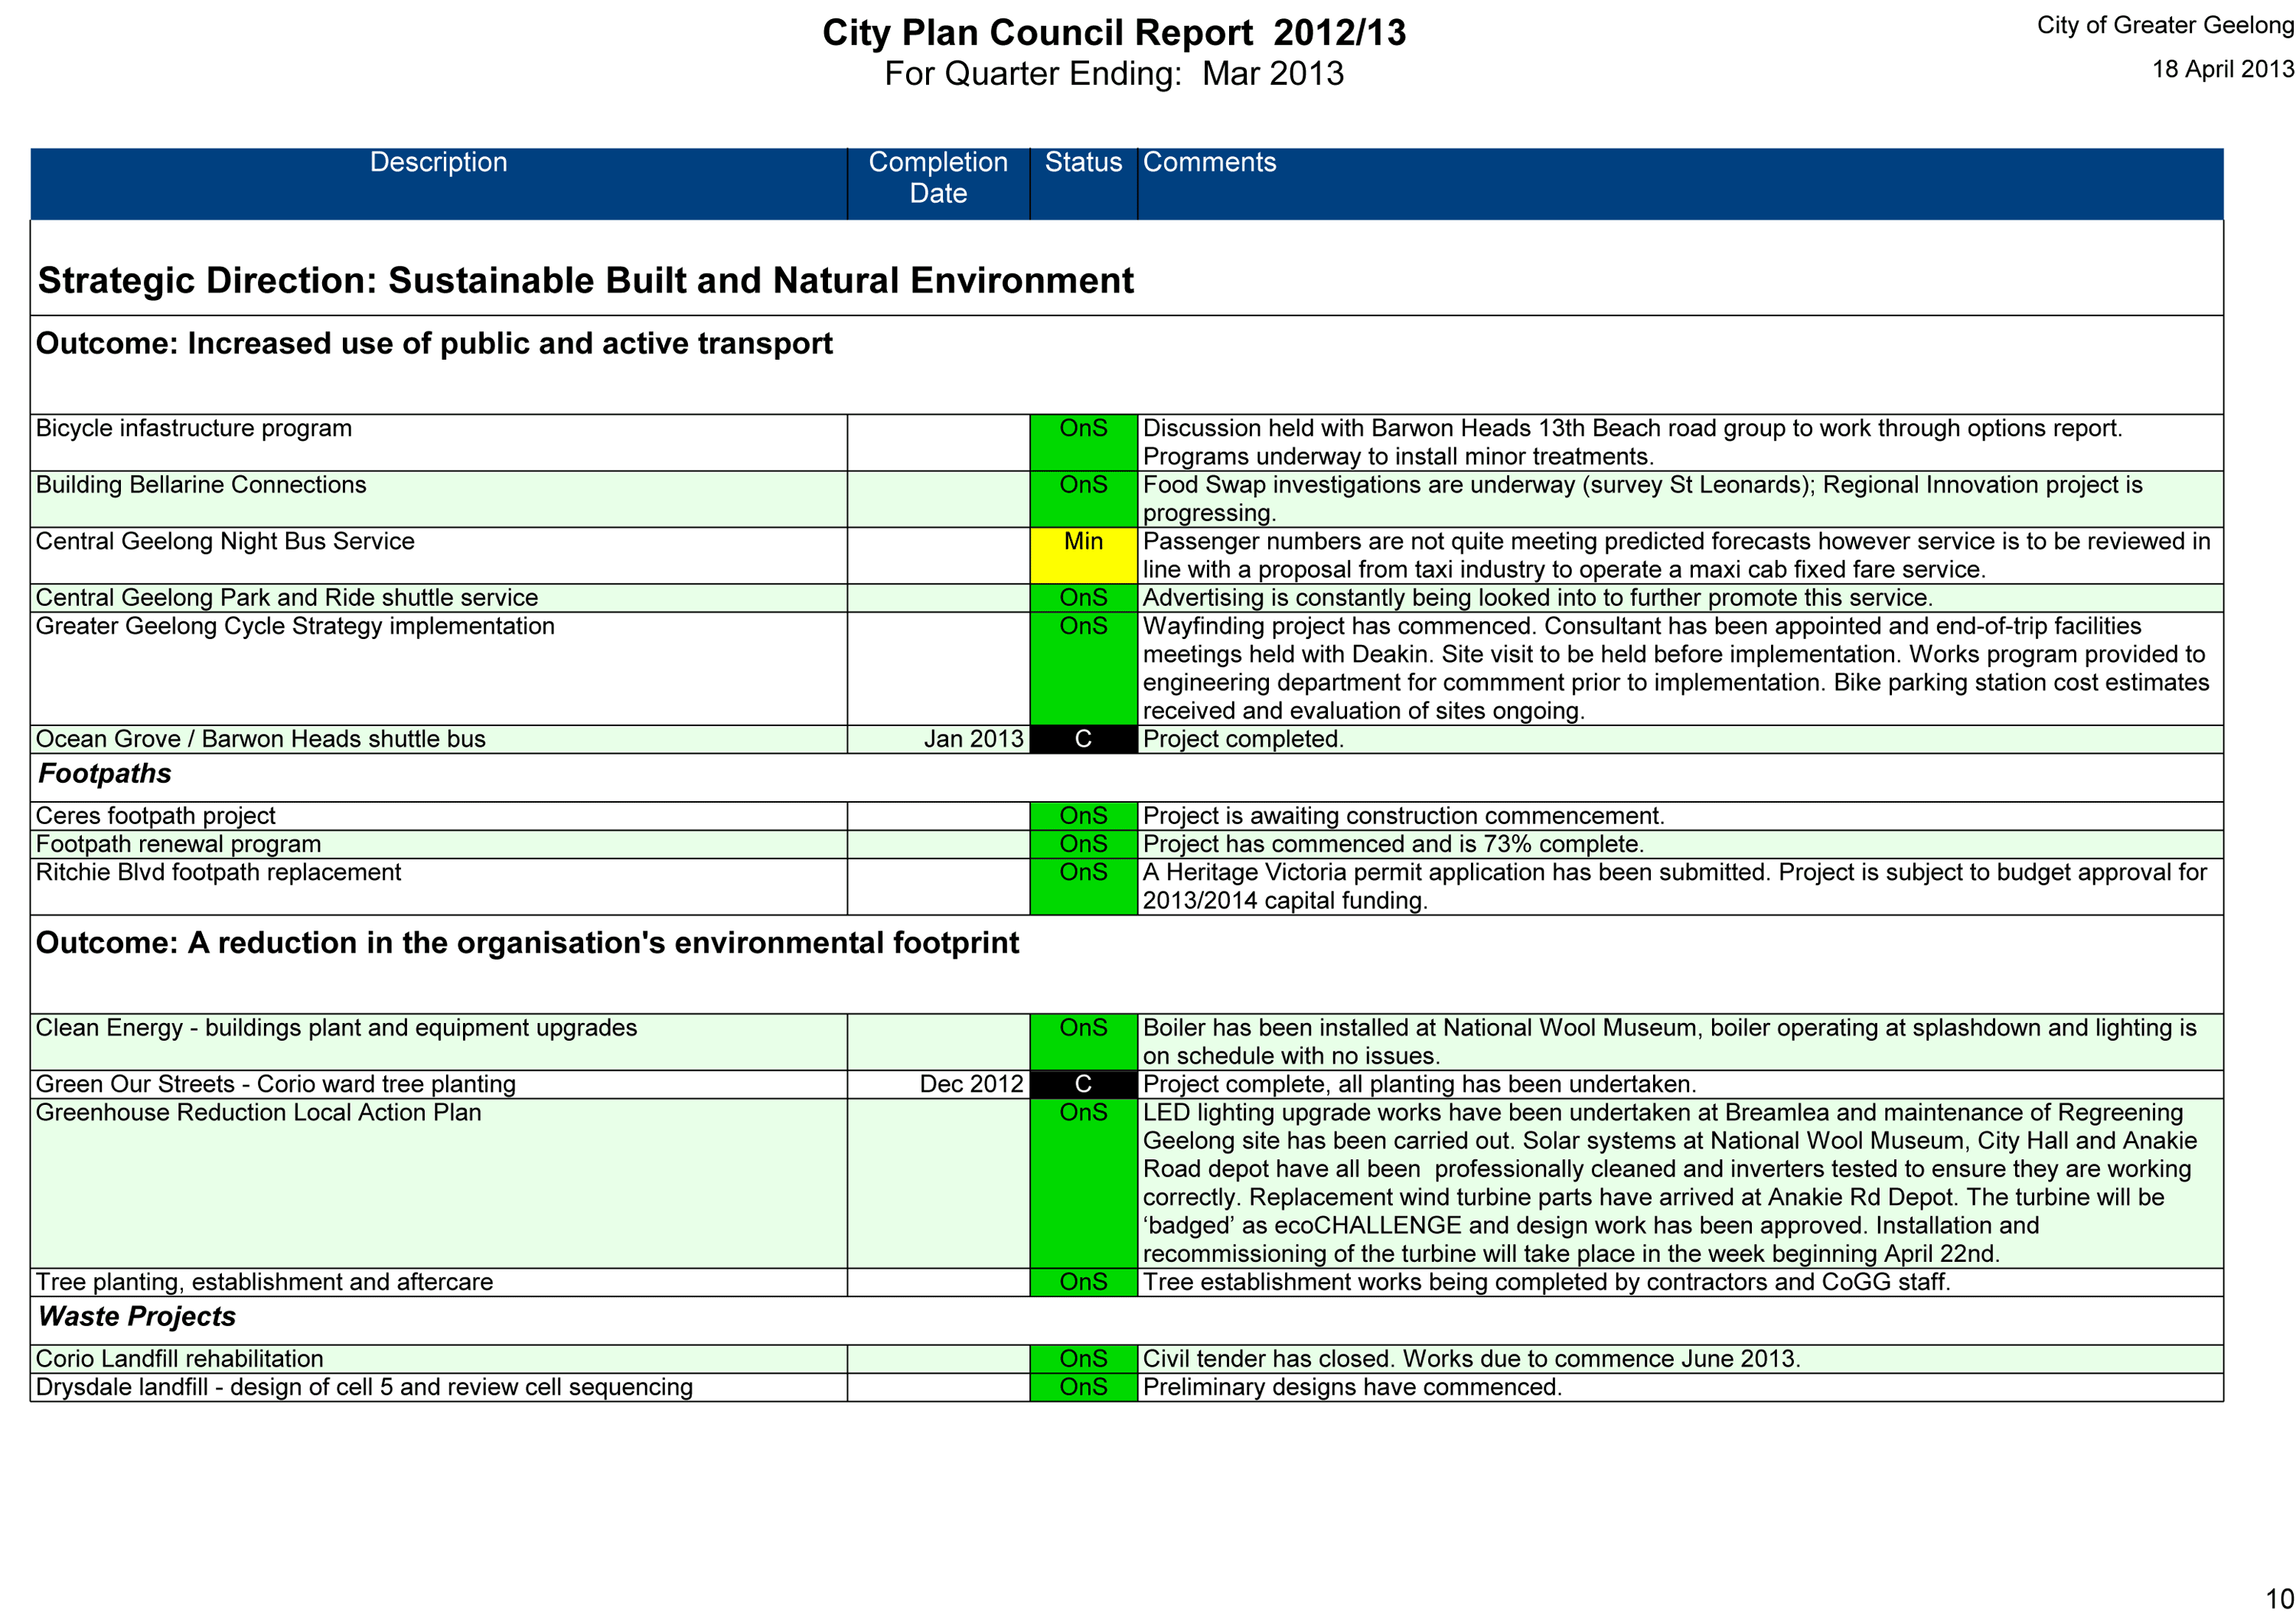
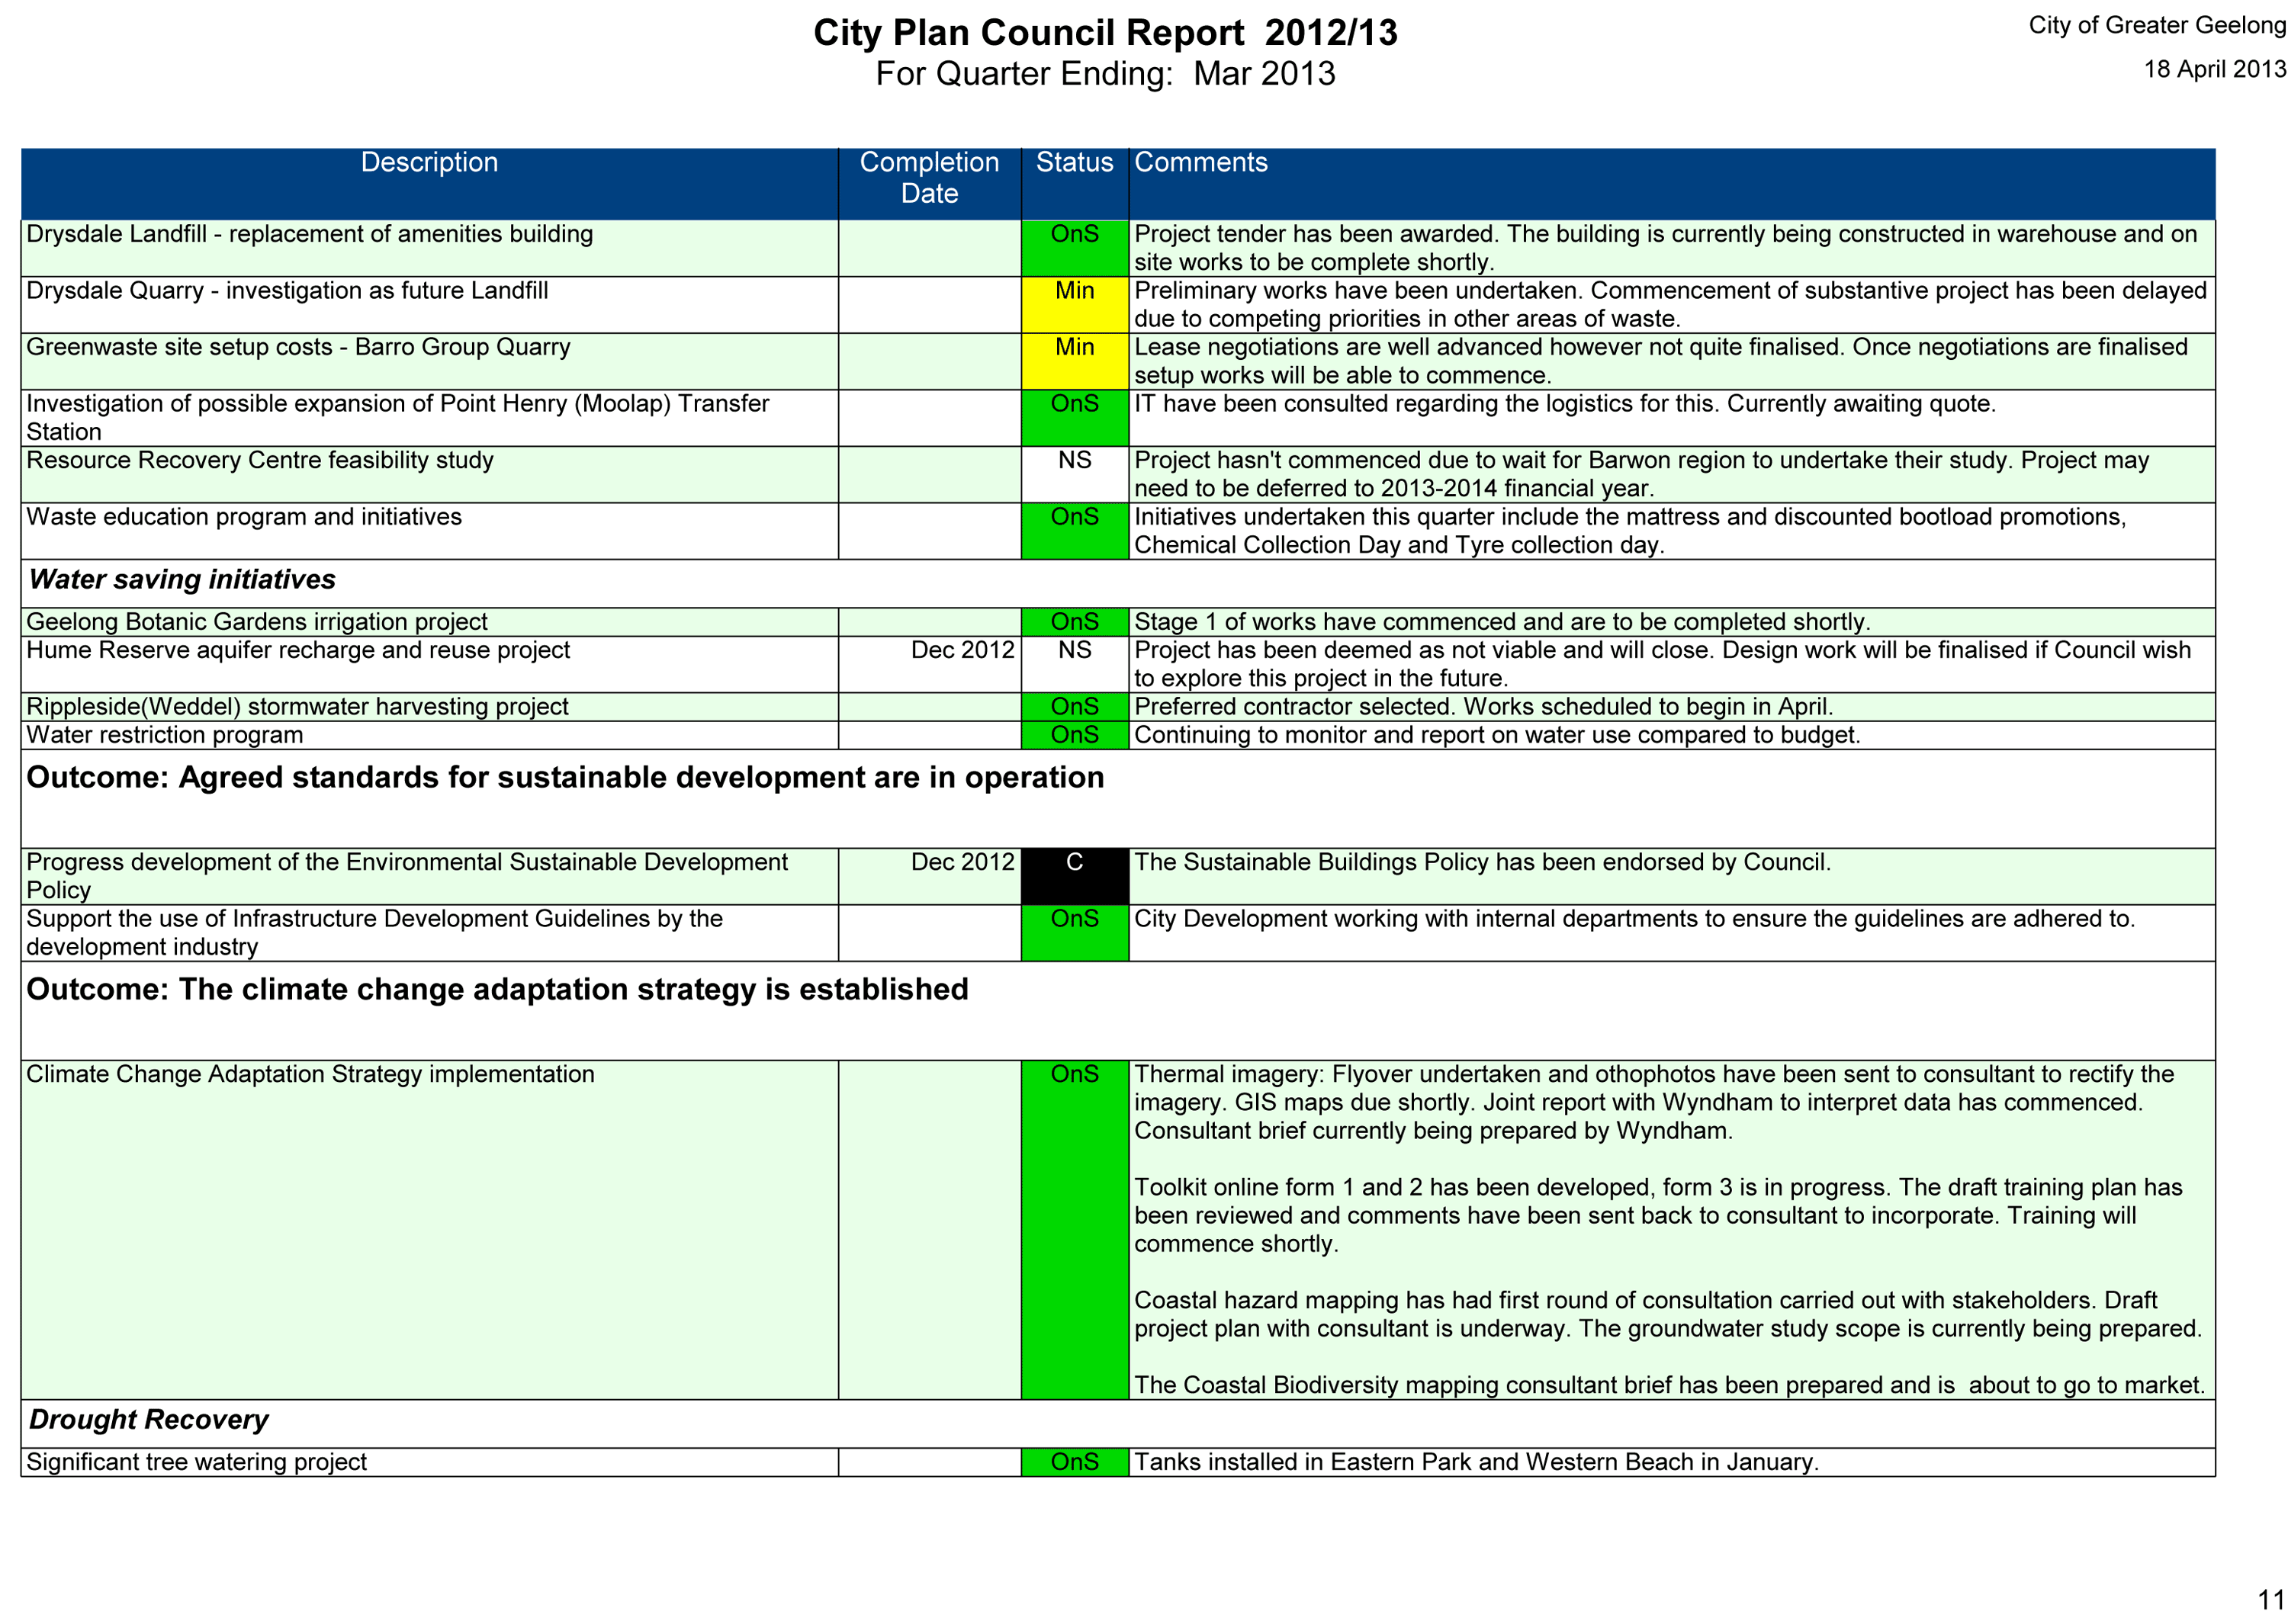
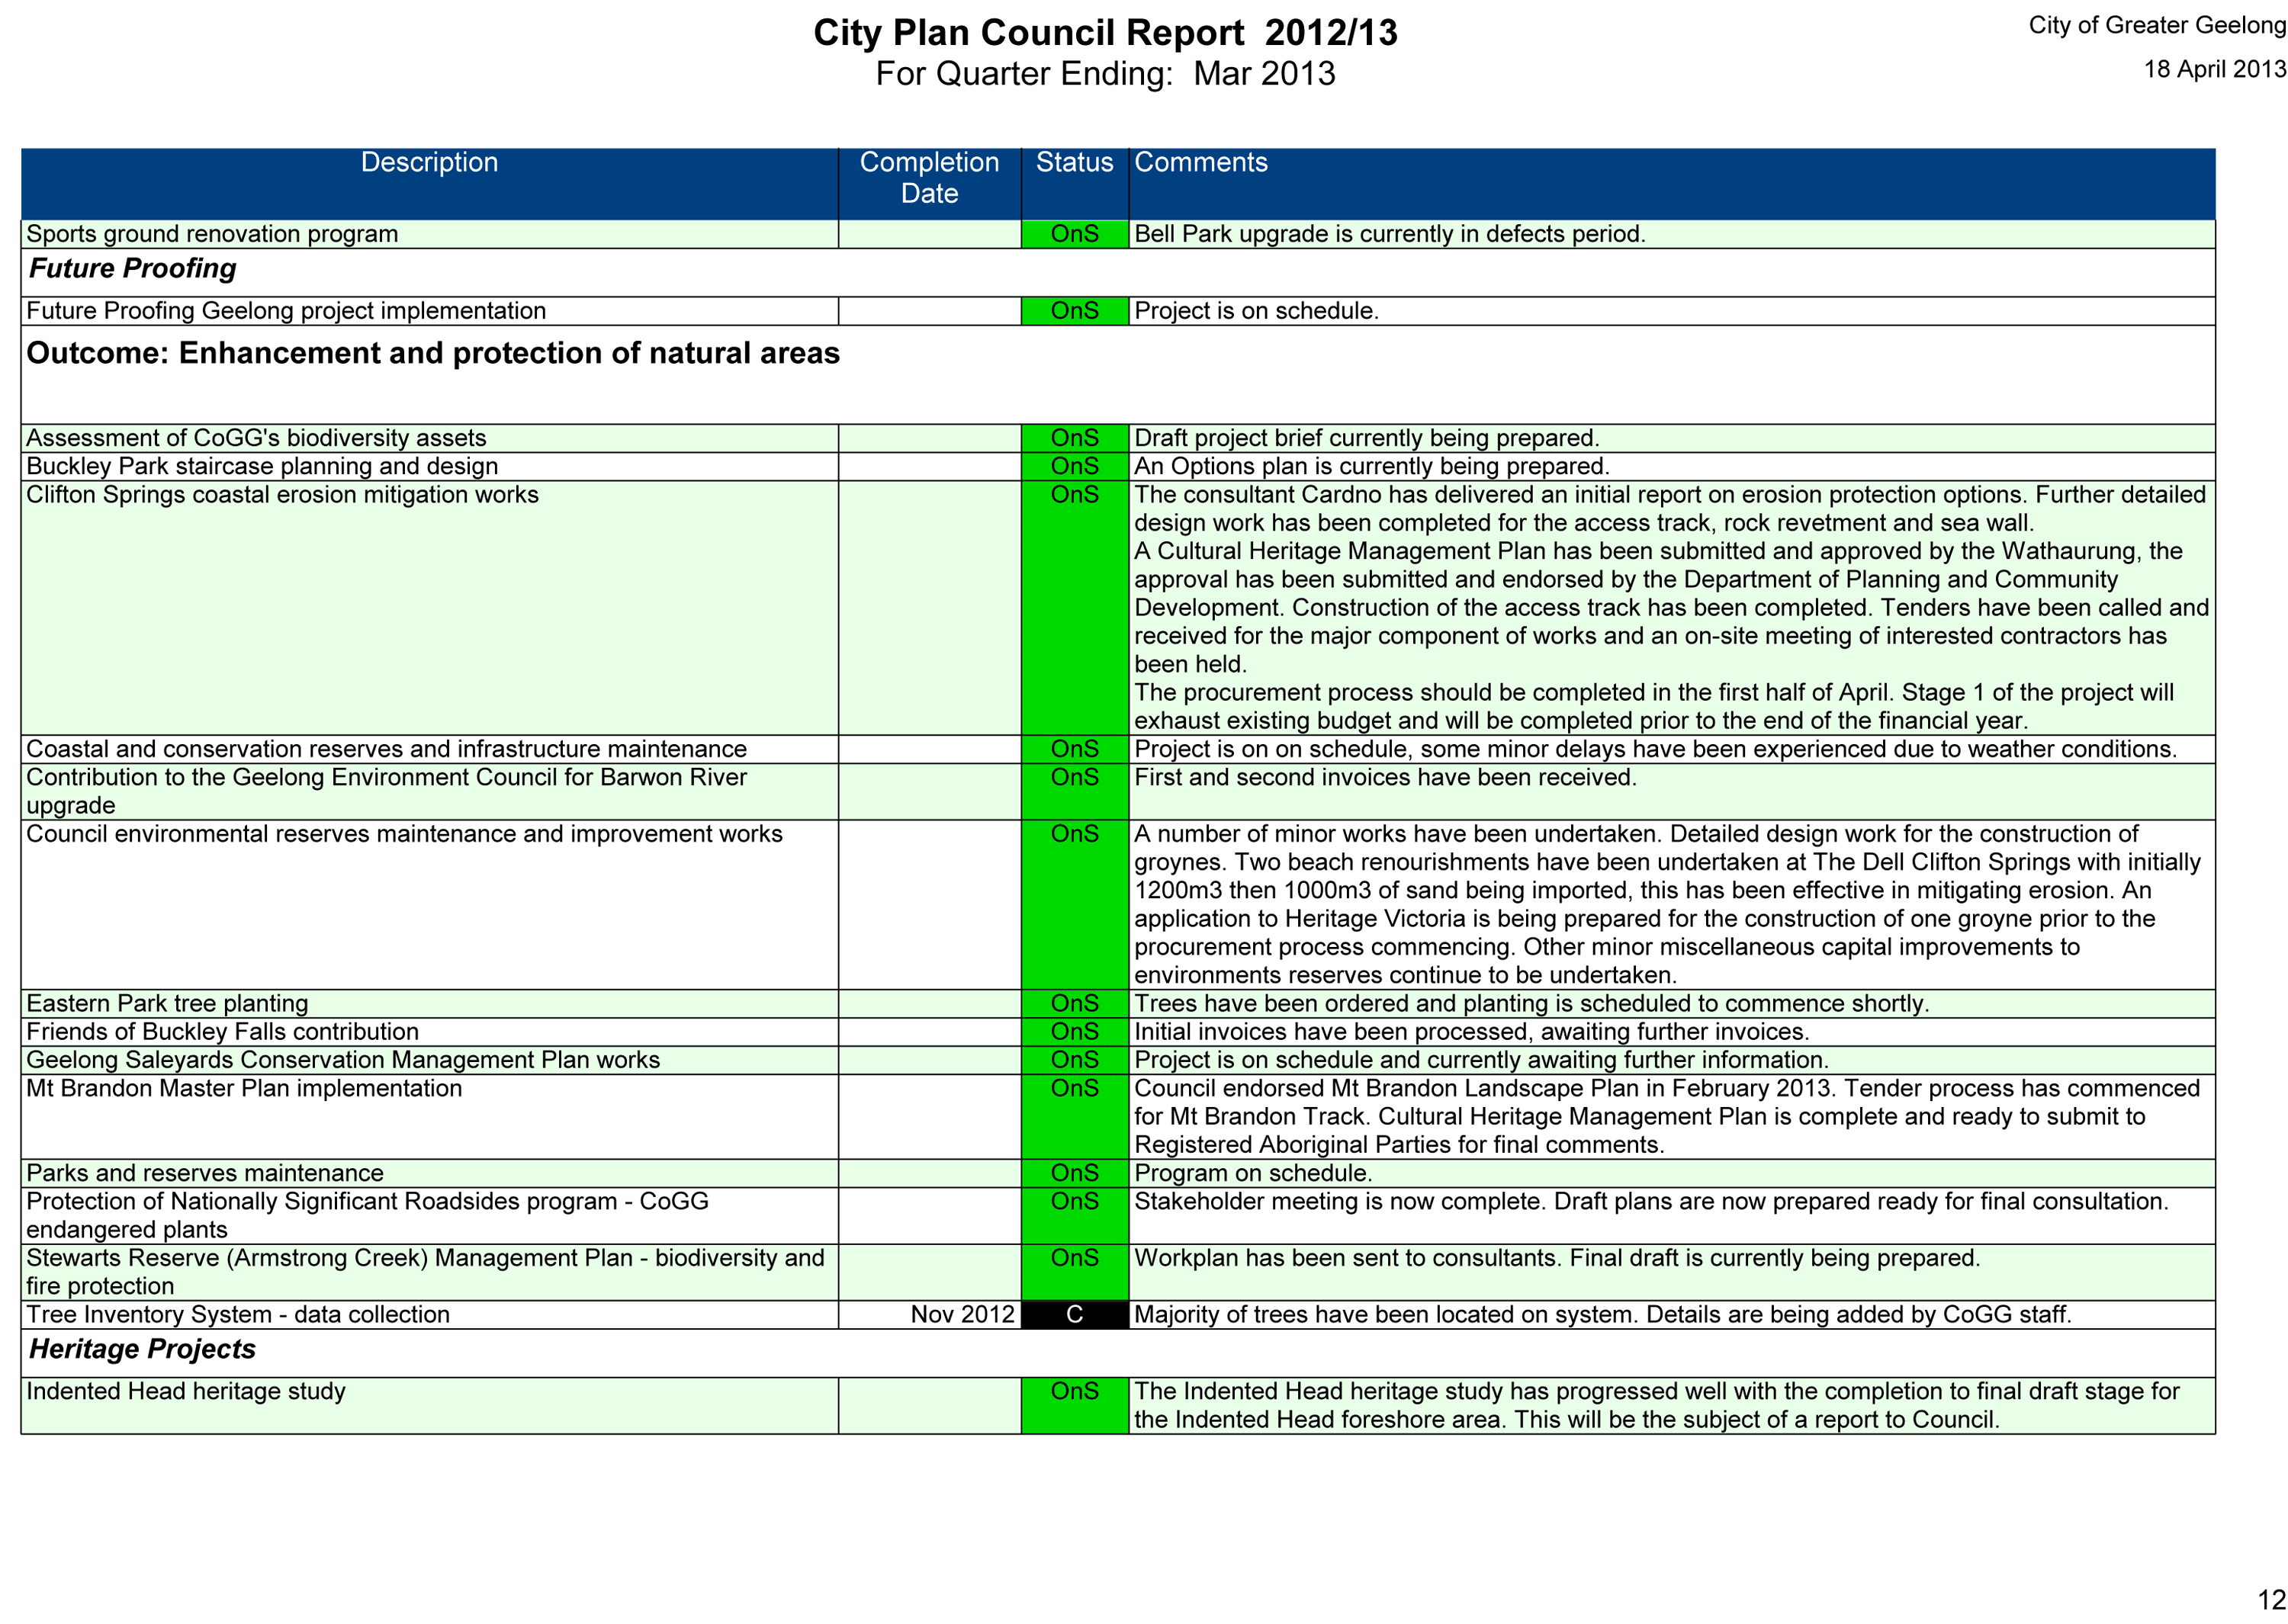
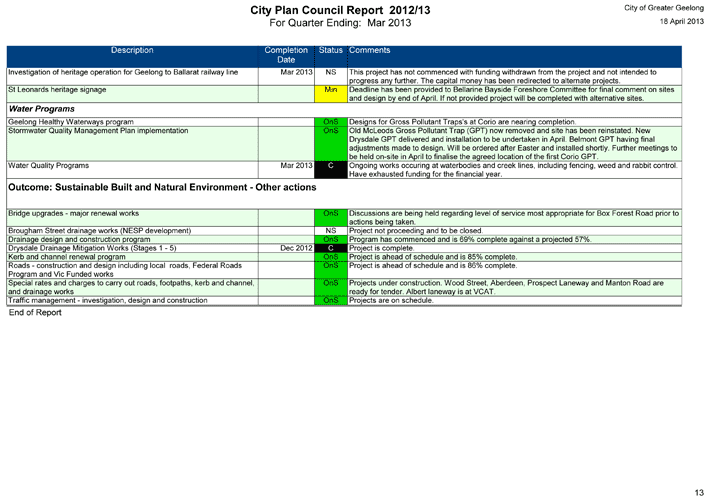
Portfolio: |
Sport & Recreation - Cr Irvine |
Source: |
City Services – Engineering Services |
General Manager: |
Gary Van Driel |
Index Reference: |
Transport, Council Reports 2013 |
The purpose of this report is to inform Council of the work needed to develop an Integrated Comprehensive Transport Plan for the City of Greater Geelong.
This report details the City’s existing transport related studies and strategies, as well as those in progress.
The cost to complete this work is estimated at $120k - $150k based on similar studies of this type.
The extra work would include consultation with stakeholders in the relevant transport areas and across the community.
Cr Richards moved, Cr Heagney seconded -
That Council:
note the report;
requests the General Manager City Services to prepare a study brief to undertake a project to review the current status and prepare an Integrated Comprehensive Transport Plan for the City of Greater Geelong.
Carried.
The City of Greater Geelong has experienced significant population growth over the past five years which will continue for some time. This has changed the transport needs for all forms of transport including, walking, cycling, public transport including trains and buses, private vehicles, and freight including Avalon Airport and the Port of Geelong.
The growth in cycling, both for commuters and for recreation, has not been met by an increase in funding for cycling related infrastructure. Concurrently, many studies and reports have shown that residents are not getting enough exercise, and that the lack of walkability in a community plays a part.
Public Transport provision in the City of Greater Geelong is also limited in its form. It is recognised that the Regional Rail Link will improve some aspects of public transport. However, bus services, access to rail stations and provision of services at rail stations are recognised as inadequate.
The need to make Central Geelong more liveable, and to find alternate routes for freight is also a significant issue, along with the expansion of Avalon Airport and the Port of Geelong.
There are several existing studies and reports that deal with different aspects of transport in the City of Greater Geelong. The most inclusive of these is the Geelong Transport Strategy (December 2003). There is no other plan or strategy that includes all forms of transport and how they work together to move people and goods around and through the City. Given the City of Greater Geelong’s continued growth, it is timely that Council develop a Comprehensive Integrated Transport Plan for all forms of transport.
The quote from ‘Sustainability and Cities’, Newman, P. and Kenworthy, J. (1999), indicates the importance of transportation planning to a city: “The land use and urban form of cities are…fundamentally shaped by priorities in transportation. Those priorities are influenced by many economic, social and political factors, but the essential character of a city’s land use comes down to how it manages its transportation.”
People travel to access employment, shops, education, community, recreational and tourism facilities and social networks or simply to increase their health. Therefore, planning the transport system is critical and will play a significant role in defining the city’s and its inhabitant’s future.
An Integrated Comprehensive Transport Plan specifically would seek to identify issues that influence the performance of Geelong’s transport systems, while also recognising the strategic inter-city issues which impact upon Geelong. Identification and analysis of the issues, including those offered through the Plan’s consultation process, should provide impetus for the development of a range of actions to address current issues and to pursue new initiatives. Importantly, the Plan will provide direction for Geelong to manage its transport needs into the future.
Work to be done to develop an Integrated Comprehensive Transport Plan
Development of a Plan will require an investigation of the existing and current Strategies and Studies that are already in place or underway, along with a comprehensive stakeholder consultation process. The development should be overseen by a Steering Committee consisting of representatives of the key stakeholders including government officers, industry representatives, public transport operators including bus, rail, taxi and community transport providers, various interest groups and the broader community.
The consultation process would need to include:
Workshops involving relevant transport stakeholder representatives and community
Context Scan
Freight Issues
Ecologically Sustainable Development
Car Parking Issues
Public Submissions.
Relevant surveys
Public exhibition
During the course of the Plan’s preparation, the interrelation with a number of transport related studies currently in progress will need to be considered. (Table 1 shows a list of transport related studies currently underway and in Attachment 2). In addition to this, existing studies and strategies, including those of a broader nature that have relevance to transport, are listed in Attachment 1.
The Integrated Comprehensive Transport Plan will require external expertise to deliver the project. Expressions of interest for the completion of this work would need to be called for as soon as a scope of work is finalised and deliverables are set.
Based on projects of a similar breadth and complexity it is estimated that the cost would be:
in the vicinity of $120 - 150k+ if the Plan is to produce a high level document that would bring all studies and strategies together to inform Council planning decisions, policies and actions.
in the vicinity of $60k if the Plan provides an understanding of all existing works and provides linking between them.
An Integrated Comprehensive Transport Plan will provide a transportation framework for the entire Greater Geelong municipality. The Plan will set directions for the planning, development and management of an integrated transport system, defining visions, strategic directions and actions for the next decade and beyond.
Table 1 Transport Related Studies Currently in Progress
|
Study Name |
COGG Representative |
Reason for Study |
How Completed |
Timing |
|
Vision 2 |
Mgr Strategic Project/Urban Design |
Future vision |
Deakin University |
March 2013 |
|
Central Geelong Taskforce |
Mayor |
Central Geelong Planning & Land Use study |
To be established |
|
|
Draft G21 Regional Road Transport Plan 2013-2017 |
Mgr Eng Services |
Review of Study |
G21 Transport Pillar PCG |
June 2013 |
|
Barwon South West Region Integrated Strategic Transport Review |
Mgr Eng Services |
Identify broad SW Region issues in existing strategies in respect to Industry investment trends |
GHD Consultants |
|
|
Central Geelong Transportation Links Study |
Mgr Eng Services |
Study of route options for vehicles through Central Geelong |
DOT Joe Vass Aecom Consultants |
March 2013 |
|
Smart Roads |
Mgr Eng Services, GM City Services |
Modelling of Road Network across all of Municipality resulting in Municipal Wide Road User Hierarchy |
VicRoads
|
June 2013 |
|
Vic integrated Transport Model (VITM) |
Senior Strategic Planner |
Analysis & Modelling of impact of Armstrong Creek Transport |
Aecom Consultants |
March 2013 |
|
Central Geelong Parking Study |
-Mgr Events Central Geelong & Waterfront -Mgr Health & Local Laws |
Review of Central Geelong Parking, Shop Top Development |
Consultant
|
|
|
Port Freight Study |
Mgr Planning Strategy & Economic Development |
Future Freight planning |
|
|
|
G21 Public Transport Strategy |
Mgr Eng Services |
Regional Public Transport |
Aecom Consultants |
July 2013 |
|
Geelong Road Safety Strategy |
Mgr Eng Services |
Road Safety Action Plan and Programs |
Public Exhibition |
April 2013 |
Development of this Integrated Transport Plan will enhance the natural and built environment through the consistent improvement of the infrastructure base. The establishment of this Plan will lead to the understanding of transport issues leading to better environment protection.
There is a direct cost associated with development of this Integrated Transport Plan. The Plan requires the production of a holistic Transport report to be performed by an external consultancy at an estimated cost of $120k - $150k (dependent on the project scope).
These funds can be re-allocated from the Urban Flood Study program should Council determine to proceed with the plan.
This Plan will provide direction for the ongoing improvement of Transport Managementwithin the Municipality and does not have adverse implications.
There are no direct or indirect interests by officers engaged in this report.
The Development of an Integrated Comprehensive Transport Plan will improve Council’s position in terms of the level of understanding of Transport risk issues.
Appropriate Transport planning means that social impacts are properly considered during the development and management of the Transport issues
A wide-ranging consultation process will need to be undertaken with the development of an Integrated Comprehensive Transport Plan to ensure that its contents are made known to relevant staff within the City and greater community.
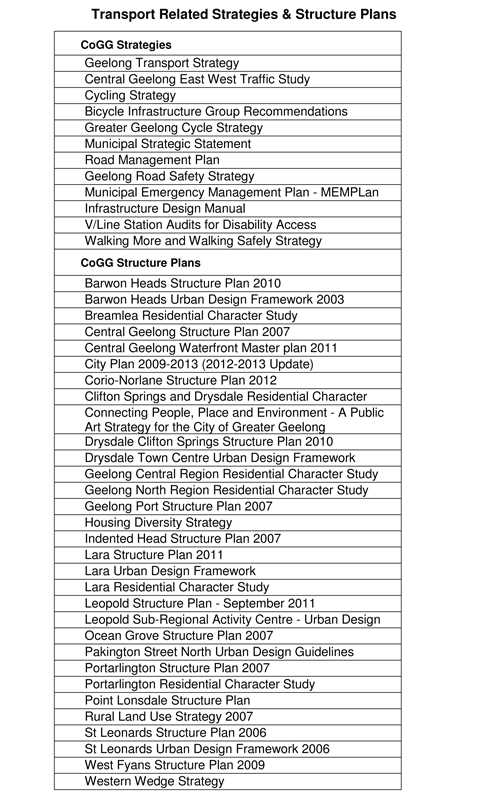
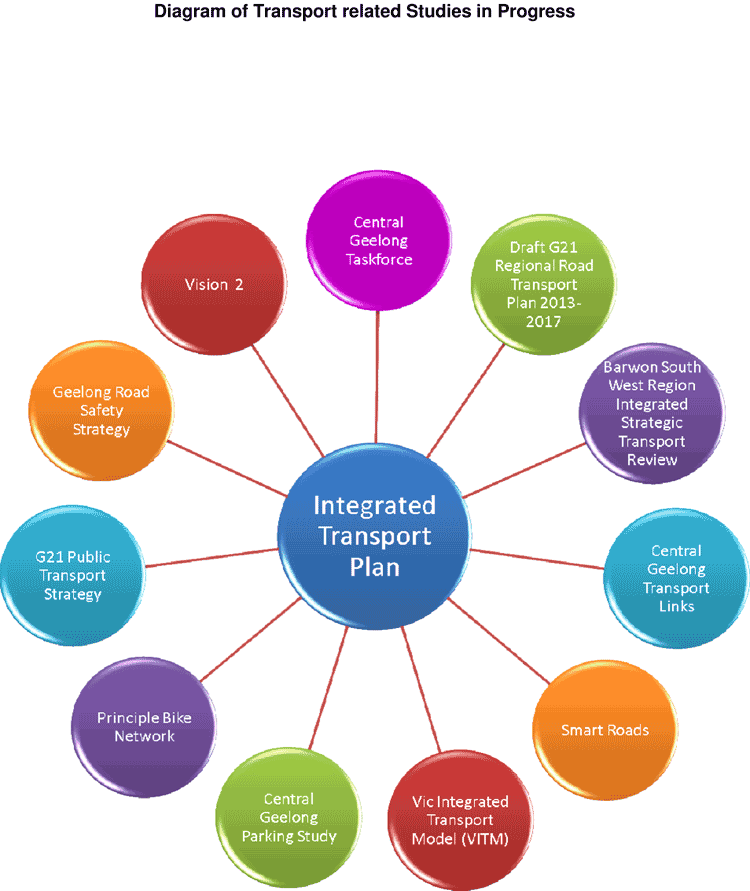
Portfolio: |
Governance – Cr Fagg (Mayor) |
Source: |
Corporate Services – Administration and Governance |
General Manager: |
Jeff Wall |
Index Reference: |
Governance |
The contract of employment for the Chief Executive Officer provides for a review of his key performance indicators.
The Performance Review Committee (the Committee) – Chief Executive, Committee Terms of Reference (TOR), provide for a review of the CEO’s performance criteria. The TOR requires the Mayor of the day as Chairperson and two other Councillors appointed by Council to the Committee, to undertake this review.
Cr Macdonald moved, Cr Richards seconded -
That Council appoint two Councillors, Cr Stretch Kontelj and Cr Bruce Harwood, to the Committee to assist the Mayor in undertaking a review of the CEO’s performance indicators.
Carried.
In accordance with section 86 of the Local Government Act 1989, Council has established a special committee for the purposes of undertaking a review of the CEO’s performance, including a review of the CEO’s performance indicators.
In accordance with the TOR of the Committee and the instrument of delegation, Council must review the CEO’s key performance indicators.
The committee is being convened to review and assess the CEO’s current performance indicators and to determine whether any amendments are appropriate in light of Council’s revised City Plan 2013 – 2017.
City Plan 2013-2017 contains Sustainable Built and Natural Environment objectives which will be considered by the committee when reviewing the CEO’s performance indicators.
A review of the CEO’s performance indicators does not involve any financial considerations.
The performance review committee has been established pursuant to the provisions of section 86 of the Local Government Act 1989 and instrument of delegation of 14 February 2013. The TOR set by Council provide for a review of the CEO’s performance indicators.
There are no Council Officers involved in preparing this report who have a direct or indirect interest.
The review has been undertaken in accordance with clearly established TOR providing for a transparent and accountable process.
A review of the CEO’s performance indicators involves consideration of community aspirations.
The committee will make a recommendation to Council regarding any proposed changes to the CEO’s performance indicators.
Portfolio: |
Community Development - Cr Fisher |
Source: |
Community Services |
General Manager: |
Jenny McMahon |
Index Reference: |
Subject: Community Building / Early Years |
Cr Macdonald moved, Cr Ansett seconded –
That in accordance with Section 89 (2) (d) of the Local Government Act 1989, this contractual matter be considered at the conclusion of all other business at which time the meeting be closed to members of the public.
Carried.
Contents | Previous Page: Section A - Procedural Matters | Next Page: Section C - Common Seal Register
