Council Minutes - Section B: Reports (9-15) - 25 September 2012
Contents | Previous Page: Section B - Reports (1-8) | Next Page: Section C - Urgent Business
Contents | Previous Page: Section B - Reports (1-8) | Next Page: Section C - Urgent Business
Reports 9-15, tabled at the Ordinary Meeting of Council on Tuesday 25 September 2012 held at City Hall, Little Malop Street in Geelong.
Local Authorities Superannuation Fund – Defined Benefit Plan
Marshalltown Road, Marshall – Proposed Footpath Construction SRC328 – Declaration of Charge
Portfolio: |
Community Development – Cr Fisher |
Source: |
Community Services |
General Manager: |
Jenny McMahon |
Index Reference: |
Project: C10503 - Leopold Community Hub |
The purpose of this report is to update Council on the Leopold Community Hub Project.
Council last received a report on this project in April 2011. Since then work has progressed on completing the concept design and obtaining initial costings.
The total project cost is currently budgeted at $16.2m (this includes $15.7m capital cost and $500,000 for planning and design works).
The scope of the project includes a long day care service, kindergarten, maternal and child health, café, a library and youth/multipurpose space.
Council has been successful in gaining $1.5m in funding from the State Government - Department of Education and Early Childhood Development for the children’s services components of the project.
However, Council was unsuccessful in its application for funding of $750,000 for the library component of the project.
The Project Control Group (PCG) had developed a preferred option assuming full external funding was achieved.
However, given that the external funding has not been realised, there is a need to stage the project in line with the funding available to Council through grants and its long term financial plan.
Cr Macdonald moved, Cr Fisher seconded -
That Council:
Note the successful and unsuccessful funding applications for the Leopold Community Hub.
Rescope the project to deliver the children’s services components in line with the successful grant conditions, as Stage 1 of the total project.
Refer the library, café and youth/multipurpose space components, of the project to the long term financial plan as Stage 2 of the total project.
Carried.
Since the Council resolution of 12 April 2011, the design of the Leopold Community Hub has progressed with a preferred concept agreed upon by the Project Control Group (PCG). This design has been developed assuming total grant applications being successful.
External funding opportunities identified in the Council report April 2011 included
DEECD for the Integrated Early Years Hub for $1m
DPCD Victorian Community Support Fund $1m
Living Libraries $0.5m
Other Federal/State grant opportunities $0.5m
Grant applications were made to the State Government for Children’s Services funding through the Department of Education and Early Childhood Development (DEECD) and for the library through the Living Libraries Fund.
The DPCD Victorian Community Support Fund was reviewed and funds redirected to a new program. It is no longer available in this format for local governments.
The DEECD application for $1.5m (maximum) was successful. However, the Living Libraries grant for $750,000 was unsuccessful.
Additional external funding of $1.5m has also not been realised, resulting in a shortfall to the project of $1.5m.
Designs for the Leopold Community Hub have progressed on the basis that all grant applications would be successful. As with all projects, a number of initial ideas for design were considered with a preferred concept being agreed upon by the PCG, subject to the success of the grant applications.
The preferred concept would require the project to be completed in one stage as a multi-storey facility with the children’s services components located on the lower level and the library located on the upper level. These two components would be linked via a common shared amenities and café area. The topography of the site allows the children’s services and library to be located at half levels below and above the common area respectively.
Council, at its meeting in April, requested a further report be presented to Council if grant applications were unsuccessful, to recommend a way forward.
Given the unsuccessful grant applications, and therefore the shortfall to budget of $1.5m, it is recommended that the Leopold Community Hub is developed in two stages. The first stage will see the completion of the children’s service component in line with the successful grant application, and the second stage will include the library, café and youth/multipurpose space.
As the total scope and cost of the project is significant, discussions will be held with the State Government to explore opportunities for future funding outside standard grant rounds.
Environmentally Sustainable Design (ESD) outcomes have been incorporated into this project where practicable.
This will also include Part J audits to ensure that buildings meet the ESD criteria required in the Building Code of Australia.
In addition to the required Part J audits Council is developing this facility based on a 5 Star ‘equivalent’ rating.
Council has previously agreed to refer budget amounts of $0.5m to the 2011-2012 budget, $8m to the 2012-2013 budget and $7.2m to the 2013-2014 budget (gross figures). These budget amounts included expected income in the order of $3m from grants. The unsuccessful grant applications have resulted in a shortfall to the project of $1.5m.
Each of the four Section 173 agreements that apply to this development have specific clauses in them relating to the progress of works. If these requirements are not meet Council would be required to renegotiate these agreements.
Council has signed four separate Section 173 agreements which commit Council to the construction of the Library and Children’s Hub in Leopold.
The development of the Leopold Community Hub will meet key social policy objectives of Local, State and Federal Government including life-long learning, community building, social inclusion and universal access.
No Council officers involved in the preparation of this report or project have identified an interest in this matter.
As with any project of this nature there are a number of risks that have been identified which are being mitigated through various control measures.
The risk profile for this project includes financial risks associated with not meeting the Section 173 agreement funding conditions.
The Leopold Community Hub project will deliver significant community benefits for all age groupings and facilitate the delivery of quality services. The Hub fulfils Council’s current policy approach to integrate services and promote multi use facilities.
The Leopold Community Hub will be in close proximity to the Leopold Primary School. It will provide the community with an important community gathering place and resource. As a sub-regional facility, commuter communities on the Bellarine Peninsula will also derive significant benefits from the hub development.
All communication about this project with be managed by Council’s Community Services Division in conjunction with Council’s communications department.
Cr Richards declared an Indirect Interest by Close Association in Agenda Item 10, Local Authorities Superannuation Fund – Defined Benefit Plan, in that he has a personal association with several Vision Super Directors, and left the meeting prior to discussion of the item at 8:45pm
Portfolio: |
Finance – Cr Harwood |
Source: |
Corporate Services - Financial Services |
General Manager: |
General Manager: Jeff Wall |
Index Reference: |
Financial Management/Reporting |
The Local Authorities Superannuation Fund (LASF), known as Vision Super since 2002, is a not-for-profit industry fund for Victorian Local Government. Vision Super is the Trustee of both the Defined Benefit Plan (closed since 1993) and an accumulation fund “LASPLAN”. These plans are managed by the Local Authorities Superannuation Board (LASB) who acts on behalf of the three major categories of employers in the scheme, being Local Government, Water Industry and ‘others’. This report is only concerned with the Defined Benefits Plan where Council has an unfunded liability.
In accordance with regulations, Trustees are required to complete an actuarial review of superannuation funds at least every three years to ensure the current assets are adequate to meet the benefits that have previously been promised to members.
An actuarial investigation was completed at 31 December 2011 and finalised on 25 June 2012 with a final unfunded liability. The Actuary recommended, and the Trustee accepted, that authorities should pay the $453M shortfall of 2011, including interest, by 1 July 2013. Including Contributions Tax, the liability is $532.94M.
Vision Super advised in a letter dated 1 August 2012 that the City of Greater Geelong’s apportioned share of the unfunded liability inclusive of interest and Contributions Tax to 1 July 2013 is $23.47M.
This amount will be payable from 1 July 2013, either by way of a single lump sum payment or by instalments over any period not exceeding fifteen years. Any monies not paid by the due date will accrue ongoing interest charged at the implied earning rate of the fund 7.5% p.a.
There is an incentive to make early payment of the unfunded call to reduce the interest portion of unfunded liability which is accruing effective from 31 December 2011. It is estimated that the total liability could be reduced by $1.3M if payment is made in August/September 2012.
Council at its meeting of 27 January 1999 signed and sealed The Local Authorities Superannuation Fund Authority Agreement and Trust Deed Local Authorities Superannuation Fund. Under this agreement the City of Greater Geelong is bound to meet its ongoing requirements as an employer and the associated contributions into the Superannuation Fund.
Council is represented on the MAV taskforce to support advocacy objectives for changes to reduce the future funding burden on Councils by achieving a self-sustaining scheme that minimises the frequency and quantum of call-ins.
Cr Harwood moved, Cr Granger seconded -
That Council commit to the following repayment plan which recognises the early payment of the unfunded liability prior to 1 July 2013 in order to realise savings on the call liability of a maximum $1.28M, as follows:
2012-2013 Budget allocation of $3.3M paid on 31 August 2012.
As per Amended Budget report note the payment of $2.0M on 31 August 2012, funded from 2011-2012 favourable working capital movements.
Delegate to the Chief Executive Officer, authority to make payment of the unfunded liability balance prior to 1 July 2013, from working capital and deferred borrowings as cash flows determine.
The Long Term Financial Plan, prepared as part of the 2013-2014 budget development, include a funding plan to reinstate working capital over four years.
Carried.
The Local Authorities Superannuation Fund (LASF), known as Vision Super since 2002, is a not-for-profit industry fund for Victorian Local Government. Vision Super is the Trustee of both the Defined Benefit Plan (closed since 1993) and an accumulation fund “LASPLAN”.
Both plans are managed by the Local Authorities Superannuation Board (LASB) who acts on behalf of the three major categories of employers in the scheme, being Local Government, Water Industry and ‘others’.
This report is only concerned with the Defined Benefits Plan where Council has been advised of an unfunded liability. The Defined Benefit plan is so called because entitlements are calculated according to pre-determined, or ‘defined’ formulas. Unlike many other superannuation plans, entitlements are not directly linked to the contributions paid to the Fund, or investment returns. The formula used to calculate a benefit follows the general formula: Years of membership x Benefit multiple x adjusted final salary.
When the Defined Benefit Plan closed in 1993 there were 38,000 Defined Benefits members and 7,500 lifetime pensioners. By December 2011 membership has reduced to Active 4,971 and 5,132 lifetime pensioners. The average age of members is 54.1 and lifetime pensioners is 79.1 years. The Actuary estimates that by the year 2031 there will be approximately 2,400 Active Defined Benefit members and less than 300 pensioners.
The City of Greater Geelong currently has 259 members.
In accordance with regulations, Trustees are required to complete an actuarial review of superannuation funds at least every three years to ensure the current assets are adequate to meet the benefits that have previously been promised to members.
In the Defined Benefit Plan, the benefits that employees as members of the fund are to receive on retirement are known and based on their period of employment and salary.
Contributions of 15.25% into the scheme are made up of employee contributions of 6.00% and employer contributions of 9.25%.
Under LASPLAN, members are not required to make any personal contributions to the plan and the employer’s contribution is set by the Federal Government. Currently, the employer’s contribution is set at 9.00%. LASPLAN member’s retirement benefits are unknown and rely on the return on investments generated by the funds.
The Defined Benefits Superannuation Scheme was closed to new members on 31 December 1993 at which time the employer contribution was set at 13.25% comprising two components:
a rate of 9.25% to meet the cost of benefits accruing each year and,
a surcharge of 4% spread across all current members to eliminate the unfunded liability for current and past employees. An unfunded liability is the difference between the present funds available and the actuary’s estimate of total liabilities for past and present members.
Given the prevailing earnings rate of the fund it was projected that the unfunded liability would be eliminated by the year 2006.
In 1995 the Actuary advised that full funding could not be achieved by the original target date unless there was a substantial increase in employer contributions. The board decided, rather than lift the rate, to extend the date of full funding to 2012.
However, in 1995-1996 the unfunded liability rose due to a reduction of income and the fact that 4,670 retrenchment benefits (incurs a higher liability for the fund than a resignation payment) were paid from the scheme. The income to the fund reduced from $35M in December 1993 to $24M in 1995, due to the decline in the salary base on which the surcharge is levied.
Figures published by the Board, show that prior to 1996, the rate at which the unfunded liability was being reduced, the increase in retrenchments in the industry (of which 92% related to municipal councils) the associated decline in income and the increase in benefits paid saw the unfunded liability increase to over $300M.
In 1997 the Local Authorities Superannuation Board advised the City that its apportionment of the unfunded superannuation liability amounted to $12.78M plus the contributions tax.
An Actuarial Review of the fund originally planned for 8 May 2003 had been brought forward 6 months to 31 December 2002 and showed a shortfall of $127M. The City of Greater Geelong’s portion of the shortfall was calculated at $5.32M, along with a contributions tax of $0.94M, totalling $6.26M.
The 2008 actuarial investigation revealed a LASF Defined Benefit Plan shortfall of $71M, however no money was requested from employers at that time. Given the Plan had a $23M surplus in 2005, a five-year funding plan was put in place, designed to return it to full funding by 2013. It was hoped that investment markets would recover sufficiently from the global financial crisis to avoid imposing any financial burden upon authorities unnecessarily.
The markets fell a further five percent between December 2008 and June 2009. They have since improved, but not sufficiently. After the actuarial investigation completed at 30 June 2010 the Actuary recommended, and the Trustee accepted, that authorities should pay the $71M shortfall of 2008 with interest. Vision Super advised that the City of Greater Geelong’s apportioned share of the funding call inclusive of interest to 1 July 2011 is $3.89M. The amount payable inclusive of contributions tax was $4.57M.
Payment could be either by way of a single lump sum payment (plus tax) or by instalments over any period not exceeding ten years. Any monies not paid by the due date will accrue interest at 7.5% p.a.
A summary of the unfunded history is as follows:
|
Year Ending |
Unfunded Liability ($M) |
Authority/Date Paid |
CoGG Share $M |
Contributions Tax $M |
Total $M |
|
1997 |
321 |
19981999 |
12.78 |
2.26 |
15.04 |
|
2002 |
127 |
28/10/2003 |
5.32 |
0.94 |
6.26 |
|
2008 |
71 |
30/6/2011 |
3.89 |
0.68 |
4.57 |
The 31 December 2011 Actuarial review was completed as scheduled.
The City of Greater Geelong and other authorities remain responsible for maintaining and funding the benefits that were promised to staff, and their surviving spouses, at the time.
The LASB as trustees, in meeting their statutory obligations, have advised that an “Actuarial Review” of the Defined Benefit Superannuation Scheme as at 31 December 2011 has resulted in a $453M shortfall in the fund. The City of Greater Geelong’s proportion of this liability amounts to $19,950,112 plus contributions tax of $3,520,608. This amount has been invoiced to Council and is due on 1 July 2013.
The methodology for apportioning unfunded liabilities between Authorities was developed by the 1997 Industry Working Party and endorsed by LASB and the State Government of the day.
It involves splitting the total unfunded liability amount into “pre June 1993” and “post June 1993” amounts. The lifetime pension amount is included in the “pre June 1993” amount. The defined benefit amount is split on the basis of the total of each member’s actual period of membership before and after 30 June 1993. These two amounts are then assigned to individual Authorities as follows:
“Pre June 1993” amount
In 1997, each Authority was assigned a share of the “pre June 1993” unfunded amount equal to the proportion that their total 1993 defined benefit salary base was of the total 1993 LASF defined benefit salary base. For example, if the Authority’s total salaries were 1% of the Fund’s total defined benefit salaries in 1993, it was assigned 1% of the “pre June 1993” unfunded liability amount. This proportion is fixed, and will not change in the future. The pre 30 June 1993 share of the call is 4.00702% or $3.69M for Active members and $3.48M for Pensioners.
“Post June 1993” amount
This amount is not fixed and will change. This amount is apportioned using the same methodology described above, but the proportion is calculated on the basis of salaries at the future measurement time. For example, if the Authority’s salary proportion had reduced to 0.5% it would only be assigned 0.5% of the “post June 1993” amount.
In the examples given above, the Authority would be apportioned 1% of the “pre June 1993” amount and 0.5% of the “post June 1993” amount. The post 30 June 1993 share of the call is 4.66324% or $12.78M.
The Defined Benefit unfunded liability amount and City of Greater Geelong’s share of this liability can be highlighted as follows:
|
|
Total Defined Benefit Plan |
City of Greater Geelong % share |
City of Greater Geelong Liability $M’s |
|
Unfunded Pension liability |
$86,880,972 |
4.00702% |
$3,481,338 |
|
Pre 30 June 1993 Service (Active members) |
$92,079,900 |
4.00702% |
$3,689,660 |
|
Post 30 June 1993 service (Active members) |
$274,039,128 |
4.66324% |
$12,779,114 |
|
Unfunded Liability |
$453,000,000 |
|
$19,950,112 |
|
Contributions Tax 15% (Gross up factor 1.1765) |
$79,941,176 |
|
$3,520,608 |
|
Unfunded Liability |
$532,941,176 |
|
$23,470,720 |
It is recommended that Council commit to a repayment plan which recognises the interest being accumulated on the unfunded liability from the review date (31 December 2011) and the benefit in paying the liability prior to or on the invoice date.
The following payment plan has been developed with the objective to minimise interest up to 1/7/2013 calculated at the earning rate of the fund 7.5%. The total amount paid relative to $23.47M will be dependent on the payment date in 2012-2013.
|
|
2012-2013 |
2013-2014 |
2014-2015 |
2015-2016 |
2016-2017 |
|
Long Term Plan – current allocation |
$3.3M |
$0M |
$0M |
$0M |
$0M |
|
Payment plan August 31, 2012
September 30, 2012 Prior to 1 July 2013
Repayment of working capital: |
$5.3M $9.4M Balance Subject to cash flow |
$10M + $18.2M
$(2.05M) reduction Capital works program |
$(2.05M) reduction Capital works program |
$(2.05M) reduction Capital works program |
$(2.05M) reduction Capital works program |
The funding plan effectively provides increased funding of $2M towards a 2012-2013 payment of $5.3M, then for Council to utilise a maximum of $8.2M working capital as internal ‘borrowings’ and $10M as external borrowings (payable over 5 years at a rate estimated at 6.8%). There may be potential to take advantage of a Treasury Corporation of Victoria loan at a lower rate of interest. Council’s working capital in this context is defined as funding reserved for committed capital programs which carryover from one year to the next. The estimated Capital carryover into 2014-2015 is $19M and some of these funds would be accessed in order to make this payment prior to 1 July 2013.
This payment plan provides for the liability to be fully paid by 1 July 2013 and the early 2012-2013 payment is estimated to save between $1.28M and $0.85M dependent on final payment date (interest and contribution tax portion).
MAV Defined Benefit Superannuation Taskforce
This Municipal Association of Victoria (MAV) has established a taskforce to provide advice to its board regarding the shortfall faced by Victorian Councils across Australia.
Council is represented on the taskforce by its Financial Services Manager, Mike Kelly.
The taskforce is also established to help accomplish the following objectives:
Achieve a return of the scheme as an exempt public sector superannuation scheme under State legislation (requires support from both the Commonwealth and Victorian governments)
Access borrowing through the Treasury Corporation of Victoria (TCV) to reduce the cost to councils of shortfall payments (requires agreement from the Victorian Government)
Exempt payments made by Councils to fund the shortfall from Commonwealth Government contributions tax and State WorkCover premiums (requires support from both the Commonwealth and Victorian governments)
The above objectives are aimed to achieve a self-sustaining scheme that minimises the frequency and quantum of call-ins.
There are no environmental implications in the adoption of this report.
Vision Super have calculated Council’s share of the unfunded liability as $19.95M plus contributions Tax of $3.52M. No payments will be required before 1 July 2013. However, Vision Super have advised that early payments are possible to assist councils reduce the interest applicable to the call amounts which accrues from 31 December 2011.
The Federal Government Tax on superannuation contributions, currently 15% apply to the above amount.
There is also a workcover liability to the State Government that will be calculated separately but is estimated at $0.15M.
Council made a budget allocation of $3.3M as part of the 2012-2013 Budget in the absence of specific advice from Vision Super. The additional amount of the unfunded liability presents a significant financial challenge to Council.
Vision Super have been proactive to highlight a number of funding options for councils as follows:
Up front payments – to reduce interest calculated at 7.5% from 31 Dec 2011 to 1 July 2013.
Borrowings – investigate potential to borrow from Treasury Corporation of Victoria (State Government Guaranteed).
A municipal bond issue.
Accessing a 15 year deferred funding plan - special arrangement entered into between the Trustee and the Regulator (APRA).
Some mix of upfront and deferred plan.
Officers recommend a combination payment plan including:
The immediate payment of the budget allocation $3.3M plus budget amendment amount of $2M.
Payment of the remaining liability from working capital and deferred borrowings, prior to the invoice date 1 July 2013, to save a maximum of $1.28M (including interest and contributions tax). A plan for repayment of working capital will be adopted as part of the 2013-2014 Budget development.
In 1998 the State Government enacted legislation that repealed the Local Authorities Superannuation Act 1988 and transferred the fund to Commonwealth supervision under the Superannuation Industry (Supervision) Act 1993.
To put these changes into effect it was necessary to establish a Corporate Trustee (Local Authorities Super Pty Ltd) and transfer the funds governing rules from legislation to a Trust Deed.
The City of Greater Geelong, as a participating employer was required under the Commonwealth Act to execute the documentation to give effect to the change from State to Commonwealth administration.
Council at its meeting of 27 January 1999, resolved to sign and seal:
The Local Authorities Superannuation Fund Authority Agreement, and
Trust Deed Local Authorities Superannuation Fund.
Under this agreement the City of Greater Geelong is bound to meet its ongoing requirements as an employer and the associated contributions into the Superannuation Fund.
In turn, the Australian Prudential Regulation Authority (APRA) legislation requires that Trustees of Superannuation Funds maintain funds under their stewardship in a sound financial position at all times.
Office Direct or Indirect Interest
Vision Super is the superannuation fund of most Council employees and accordingly an indirect interest exists on this basis.
The City of Greater Geelong has 1,962 members of Vision Super of whom 259 are currently members of the Defined Benefit Scheme. Actuarial projections suggest that fund membership, both active and lifetime pension members, will continue beyond 2031. Therefore there is significant ongoing risk, that lower than required performance of the fund will result, in future unfunded liability obligations on Council.
Not applicable.
The magnitude of the call will have a significant impact on Local Government and Council’s current and future operating budgets. The recommended funding model outlined in the report is financially responsible and represents the best approach to a financial liability. There is a need to communicate to all ratepayers that Council is managing this liability within existing budget considerations to minimise the threat of rate increases.
Cr Richards re-entered the meeting room at 8:58pm.
Portfolio: |
Infrastructure - Cr Richards |
Source: |
City Services |
General Manager: |
Gary Van Driel |
Index Reference: |
Asset Management |
Council has received over time a number of requests from private developers seeking to maintain various constructed public assets as part of their developments.
Council has seen VCAT decisions handed down assigning responsibility to developers to manage certain assets on behalf of Council for nominated periods of time.
The form of agreement discussed in this report seeks to put the legal framework in place to formalise such arrangements where approved by Council and to protect the interests of Council in relation to the care and maintenance of constructed public assets.
Cr Richards moved, Cr Harwood seconded -
That Council endorses Option 3 outlined in this report when assigning the care and maintenance of constructed public assets to other parties as negotiated from time to time.
Cr Granger left the meeting room at 8:58pm
Cr Granger re-entered the meeting room at 9:00pm
Carried.
An increasing number of developers wish to retain the ongoing care and maintenance of what would traditionally be called public assets, often built by the developer and then transferred to and maintained by, the Council. Such public assets might include:
public open space (playgrounds etc);
road reserves and nature strips;
ponds, water features or the like; and
public art or other constructions (eg. gateways, street furniture).
The developers' reasons for this might include:
wanting to maintain a higher or "better" level of maintenance than the Council's (reasonable) budgetary constraints may allow;
to improve the marketability of a particular development (ie. the development will look more attractive over the time of a long term sales period); and
in respect of specialised public infrastructure which the Council might not otherwise want to accept (e.g., complex water management systems).
Developers may want to take on this responsibility for the short to medium term for example, in a staged subdivision where it wishes the earlier stages of the subdivision (in terms of the public areas) to be very well maintained to encourage purchasers.
For the long term, or indefinitely, where the developers maintain an interest in a subdivision, for example retaining ownership in a commercial or industrial estate wishing to maintain high levels of maintenance to maximise rent returns and tenant interest. The "Keystone" proposed development at 425 Barwon Heads Road is an example of a proposal for a permanent commitment.
Potential Approaches
In response to such requests the Council can consider 3 options:
refuse the arrangements and leave in place "traditional" levels of Council maintenance;
with the developers' agreement, shift, substantially, away from the traditional model leaving such things as roads, public access areas and the like, in the ownership of an Owners Corporation. Parts of Sanctuary Lakes are an example of this model.
where the Council in the traditional way takes a transfer (or has vested in it roads, road reserves, public areas and infrastructure) and allows the developers, and in due course the Owners Corporation, to maintain specified public assets to an agreed standard and secures those arrangements by section 173 agreements.
There are arguments for and against the different options. The key factors in that assessment include:
It may be best for various reasons to ensure certain public infrastructure remains in the ownership and care and maintenance of the Council. The actual road surface and major drainage infrastructure will often fall into this category, but not always;
The option where ownership of roads and other public areas, drainage etc., remains initially with the developer and later transfers to an Owners Corporation (Option 2 above) creates the need for special easements and access arrangements to be secured for the general public via various documentation and the like. It can also create confusion for the public and residents within such developments, they usually turning first to the Council for what are considered to be traditional council services. There is also an element of loss of control and governance associated;
The third option proposed in this report, namely the normal transfer of public assets to Council but the maintenance carried out by the developers, carries with it a need to minimise risk to the Council, clarity around the precise standards of care and maintenance and a need to retain with the Council a right to "step in" and recommence the care and maintenance in particular circumstances.
Option 3 is the preferred and recommended option because it reflects the traditional arrangements but provides a choice to Council to "allow" (on specific terms) the Owners Corporation and individual lot owners to have their own higher levels of maintenance if they so choose, at their own cost. It is a cooperative approach which encourages high quality outcomes and to a limited extent reduces costs to Council, particularly where developments adopt unique public areas and infrastructure.
One key risk management strategy built into the recommended option is a right in favor of the Council, if it chooses, to step in and carry out care and maintenance and, if appropriate, to levy differential or special rates/charges, to cover that cost. Council can also reduce the level of maintenance.
The Proposed Structure (How it Works)
The arrangements are secured, legally framed via:
appropriate planning permit conditions;
an initial Developer Agreement with the developers and owners of the land in question; and
a longer term Public Asset Care Agreement, the parties to which include an Owners Corporation to be created, the ongoing owners of the land (i.e., future individual lot owners) and Council.
Developer Agreement
The Developer Agreement has the following key elements:
General description of parties, the land, the objectives and the arrangement and intent.
It either lists the agreed public assets which will be the subject of the arrangements, or sets out the method by which those public assets will be later identified and agreed.
If defining the public assets is to be decided later, Council's agreement to deciding relevant public assets will be a precondition to the Council's consent to any statement of compliance for the first stage of any subdivision.
The agreement will either set out a detailed "Public Asset Program", or establish the method by which such Public Asset Program must be established. Again, the finalisation of a Public Asset Program, to the satisfaction of the Council, will be a precondition to the grant of any statement of compliance for subdivision of the land.
Attached to the Developer Agreement will be a set of Asset Care Conditions, dealing with issues at a higher level than the detailed Public Asset Program, this covering such issues as the right to subcontract, OH&S, insurances and the like.
Step in Rights - The agreement secures an ability in the Council (subject to notice, except in emergency) to step back into the role of care and maintenance if there is a failure by the developer to appropriately maintain. This includes rights in the Council, as it thinks fit to:
reduce any special levels of asset care and maintenance to Council levels; and
Introduce a differential rate or special rate/charge if Council's fulfillment of that role creates special or additional costs to the Council.
Section 173 Agreement - Developer Agreement is set out in the well understood model of the Section 173 Agreement pursuant to the Planning and Environment Act 1987. It will generally be registered on the title to the land. The Developer Agreement will be removed from the title to the land as the obligation to maintain the relevant public assets shifts to the Owners Corporation.
Transfer of Responsibility to Owners Corporation - The Development Agreement envisages the transfer of responsibility for the public asset care to an Owners Corporation established by the subdivision of the land. This transfer of responsibility may occur in one step if the development is a single stage subdivision or progressively where a development has multiple stages of subdivision.
A copy of the draft Public Asset Care Agreement will be attached to the Developer Agreement so there can be no dispute as to the form of the long term agreement that must be entered into to achieve the transfer responsibility to the Owners Corporation, bind future lot owners and as a precondition to any approval of a stage of subdivision.
Public Asset Care Agreement
In many respects, the Public Asset Care Agreement is a repeat of much of the Developer Agreement. By this stage the public assets negotiated to be maintained will be agreed to and will be subject to the arrangements set out below:
The Public Asset Program will exist and be incorporated as a Schedule to the this Agreement.
It will repeat the step in rights held by the Council, including the conditions regarding levels of maintenance and the potential for special rates if the Council exercises its right to step in.
The obligation to create an Owners Corporation in the Developer Agreement will have created a legal entity with which Council can contract. Additional provisions in the Public Asset Care Agreement will require future lot owners to recognise the special arrangements and acknowledge, as a matter of contract, what might happen if the Owners Corporation fails to properly maintain and the Council took over those roles via its step in rights.
The Public Asset Care Agreement must be signed by the Owners Corporation, immediately upon it coming into existence and be lodged on all privately owned land. This means the future owner of any individual lot will be made aware of the arrangements and will be bound by the arrangements. This does not mean a future lot owner will be individually responsible to carry out the maintenance; that role is with the Owners Corporation, but it does contain provisions about how and individual lot owner may act in terms of its body corporate rights, to the extent that those rights can be changed by contract.
Diagrammatic representation
Attachment 11-1 to this report is a diagram which sets out the proposed arrangements.
There are no environmental implications associated with this report.
The cost to maintain constructed public assets developed from subdivisions traditionally falls to Council. There is an opportunity to transfer a proportion of these costs directly to a developer and /or an Owners Corporation subject to agreement with Council.
In other municipalities arrangements have included a form of reimbursement to offset the cost of the base level of service that Council would normally have provided, in examples where a higher service level is desired. This is not being proposed in this instance.
Opportunity to include a form of security deposit is available to protect Councils interest should these arrangements cease.
These forms of agreement exist in other Council areas and are a tool which can be enabled through negotiations with developers and structured through planning permit conditions. Council needs to consider the policy position of providing an opportunity for such agreements.
No officers involved with the preparation of this report have a direct or indirect interest in matters to which this report relates.
The form of agreement seeks to limit the exposure of Council to risk and explicitly share risk with the maintained asset.
Community expects public assets to be maintained to acceptable standards. The proposed framework provides flexibility, whilst retaining Councils interest.
This report has highlighted the potential to support asset maintenance via a number of structured arrangements.
It will be necessary to communicate with residents in relation to arrangements which may from time to time be adopted.
Portfolio: |
Infrastructure - Cr Richards |
Source: |
City Services - Engineering Services |
General Manager: |
Gary Van Driel |
Index Reference: |
Barrabool Road, Scenic Road, Highton |
This report relates to the construction of footpath at the corner of Scenic and Barrabool Roads, Highton abutting St Luke’s Uniting Church, as shown on attached Plan – Appendix 12-3.
Footpath has recently been constructed to the north abutting the cemetery in Scenic Road and Mt Pleasant Road and there is existing footpath in Barrabool Road to the north.
There is only one property in the scheme and the total cost of the works is $25,445 with 50% contribution by owners and the Council.
The property owner receives benefit from the works by way of improved pedestrian access and improvement to the area fronting the property.
Council received one submission from the property owner, St Luke’s Church. A Submissions Panel Hearing was held in April 2012.
The scheme has been prepared in accordance with the Special Rates and Charges provisions of the Local Government Act, along with Council’s Special Rates and Charges Policy.
This report seeks a resolution by Council to “Declare the Charges” for the footpath scheme in Barrabool Road and Scenic Road, Highton in accordance with the Special Charge process as shown in Process Chart – Attachment 12-1.
Cr Richards moved, Cr Macdonald seconded -
That:
The following declaration of a Special Charge be confirmed:
A special charge be declared for the period until the work has been completed and the scheme finalized.
The special charge be declared for the purpose of defraying any expenses incurred by Council in relation to the construction of a footpath in Barrabool Road and Scenic Road, Highton, abutting 170-172 Barrabool Road, which project:
will provide proper pedestrian access, improved nature strip and enhancement to the general amenity for each of the properties included in the scheme;
Council considers is or will be a special benefit to those persons required to pay the special charge (and who are described in succeeding parts of this Resolution); and
arises out of Council’s function of planning for, and providing infrastructure for property owners.
The:
cost of performing the function described in Part 1 (b) of this Resolution based on estimated cost for the modified scheme, be recorded as $25,445.
total amount of the special charge to be levied, as based on estimated cost for the scheme, be recorded as $10,455.
It be recorded that, for the purposes of Section 163(2A) of the Local Government Act 1989, the special charge proceeds will not exceed the amount calculated in accordance with the prescribed formula (R x C = S), the:
‘benefit ratio’ (R) being calculated at 100%, and representing the total benefits of the special charge scheme that will accrue as special benefits to all persons liable to pay the special charge; and
‘community benefit’ (C) being assessed as 50% in Barrabool Road and Scenic Road, Highton.
The following be specified as the area for which the special charge is so declared:
The area within municipal district of Council highlighted in the plan attached to this Resolution (“the area”).
The following be specified as the land in relation to which the special charge so declared:
All land within the area shown on the plan.
The following be specified as the criteria which form the basis of the special charge so declared:
Ownership of any land described in Part 1(e) of this Resolution.
The following be specified as the manner in which the special charge so declared will be assessed and levied:
The frontage of lots abutting the works shall be used to calculate the individual cost to a lot.
The special charge will be levied by sending a notice to the person who is liable to pay, pursuant to section 163(4) of the Local Government Act 1989.
Having regard to the preceding parts of this Resolution but subject to Section 166(1) of the Local Government Act 1989, it be recorded that, subject to any further Resolution of Council, the special charge will be due and payable on the date(s) fixed under Section 167 of the Local Government Act 1989 as the date or dates on or by which Council’s general rates are due.
There are no incentives declared as incentives to be given by Council for the payment of the special rate before the date(s) specified for its payment under Section 167(3) of the Local Government Act 1989.
Council’s Chief Executive Officer be authorised to levy the Special Charge in accordance with Section 163(4) of the Local Government Act 1989.
Carried.
This project involves the provision of footpath in a fairly heavily pedestrianized area being at the corner of Scenic Road and Barrabool Road, Highton. St Luke’s Uniting Church is located on this corner and the proposed scheme involves the provision of footpath along each street frontage.
The Highton Cemetery is located to the north and Council has recently provided footpath in Mt Pleasant Road and Scenic Road abutting the Cemetery.
Barrabool Road has footpath on both sides. Both Barrabool and Scenic Roads are bus routes.
This project provides for missing infrastructure.
A Submissions Panel Hearing was convened on 2 April 2012. St Lukes representatives addressed the Panel and indicated that generally cost was an issue and should the works proceed, this may mean curtailing projects elsewhere. It was indicated that pedestrians do not cut the corner from Scenic Road to Barrabool Road and use the car park as access. The Submissions Panel considered the opinion of the Church representatives and sought further information from Council Officers regarding the overall footpath strategy for the area. This was subsequently provided.
The property owner receives benefit for footpath by way of improved pedestrian access, enhancement of the naturestrip area and improved general amenity.
Council policy provides for a 50% contribution by owners and 50% by Council. The estimated cost is as follows:
|
|
Estimated Cost |
|
Council half share |
$10,455 |
|
Owners half share |
$10,455 |
|
Additional works by Council |
$4,535 |
|
Total |
$25,445 |
The issue of pedestrians continually using the Church carpark as access is not a satisfactory long term solution. Although representatives did not raise the issue, public liability must be of concern. Due to the lack of footpath and currently difficult nature strip conditions, pedestrian are encouraged to make this decision.
A question often raised by Churches and similar organisation, is that since they are non rateable (do not pay the general rate) can they be charged a special rate or charge?
In accordance with Section 154 (2)(d) of the Local Government Act 1989 land vested in a trust or religious body is not rateable land. However at Section 221 (3); “Council may declare in relation to any land in its municipal district which is not rateable land and is not crown land a special rate or charge in relation to street construction”
A footpath is a component of street construction, and therefore it is quite legitimate for Council to levy a charge on a Church which is not rateable.
Footpath projects in general are aimed at providing a safe off road facility for pedestrians and as well to encourage walking in lieu of using a motor vehicle.
During the course of construction and the manufacture and procurement of materials there is expenditure of energy and greenhouse emission. This does cease, however, when construction is complete. Should the footpath project achieve the aim in part, to encourage walking over driving, there will be a positive environmental impact.
The project does not create waste with the exception of some excess spoil. The proposal does not affect any natural habitats.
The project has a one off capital cost as indicated above and there will be minimal ongoing maintenance costs. The scheme may proceed in the current financial year if approved. The owner meets half the cost of the works.
The scheme has been prepared in accordance with the special rate and charge provisions of the Local Government Act along with Council’s Special Rates and Charges Policy.
There are no Council Officers involved in the administration or subsequent construction of the works, whom have a direct or indirect interest in the project.
There are no risks associated with Council proceeding to adopt the recommendation and advertising the scheme. The footpath, should it proceed, will have a positive impact on risk reduction relating to vehicle/pedestrian accidents and slips and falls.
A footpath is a project which encourages walking and could be considered to enhance the social well being of the local community.
The owners representatives have had the opportunity through the Submissions Panel process to address issues and concerns.
The works for the construction of footpath in Scenic Road and Barrabool Road, Highton which consist of excavation, footpath, reinstatement of nature strip, miscellaneous construction works, legal advice and professional services associated with survey, engineering design, drafting, supervision and administration of the project all as included in the cost estimate shown below.
Cost Estimate for Construction of Footpath
Scenic Road and Barrabool Road, Highton
Section 1 - Footpath
|
ITEM |
DESCRIPTION |
QUANTITY |
UNIT |
RATE $ |
AMOUNT $ |
|
1.00 |
Site establishment, set out and traffic control |
|
item |
|
2,470 |
|
2.00 |
Excavation, trimming, supply and placement of bedding and formwork |
132 |
m |
5 |
660 |
|
3.00 |
Supply and place 75mm depth reinforced concrete footpath |
132 |
sqm |
100 |
13,200 |
|
4.00 |
Make good disturbed nature strips with 100mm depth approved loam and seed |
132 |
lm |
5 |
660 |
|
Sub Total |
$16,985 |
|
|
|
|
Total |
$20,909 |
Section 2 – Additional Works
|
ITEM |
DESCRIPTION |
QUANTITY |
UNIT |
RATE $ |
AMOUNT $ |
|
1.00 |
Site establishment, set out and traffic control |
|
item |
|
535 |
|
2.00 |
Infill concrete bus slab |
|
item |
|
750 |
|
3.00 |
Concrete kerb ramp |
2 |
No |
750 |
1,500 |
|
4.00 |
Adjust sewer lid level |
|
item |
|
900 |
|
Sub Total |
$3,685 |
|
|
|
|
Total |
$4,536 |
Special Charge Scheme for Footpath Construction
Scenic Road and barrabool Road, Highton
|
COL 1 |
COL 2 |
COL 3 |
COL 4 |
|
DESCRIPTION OF PROPERTY |
ESTIMATED COST ($) |
PROPERTY REFERENCE |
PROPERTY DETAILS |
|
1/2 Share 8034m2 CA 1H Sec 19 |
$3,131.45
|
220689
|
170 |
Barrabool Road |
Highton |
|
1/2 Share 8034m2 CA1H Sec19 |
$7,323.55
|
220696
|
174 |
Barrabool Road |
Highton |
Portfolio: |
Infrastructure - Cr Richards |
Source: |
City Services - Engineering Services |
General Manager: |
Gary Van Driel |
Index Reference: |
Subject: Special Rates and Charges |
This report relates to the proposed Special Charge Scheme for footpath construction in Marshalltown Road, Marshall, south side between Barwarre Road and the railway line. (See Plan – Appendix 13-3).
The total cost of the project is $61,976 with 50% of the cost to be borne by abutting property owners and 50% by Council.
Property owners’ contributions are based on the frontage of the properties. Estimated charges are shown in Schedule B (Appendix 13-2) and vary from $838.68 to $5991.90.
The proposed footpath scheme provides an important link to the Railway Station.
Property owners receive benefit from the works, by way of improved pedestrian access, improvement to the area fronting the property and possible increase in property values.
Council has received 3 objections to the scheme and none have requested to be heard by a Submissions Panel.
The scheme has been prepared in accordance with the Special Rate and Charge provisions of the Local Government Act, along with Council’s special rates and charges policy.
This report seeks a resolution by Council to “Declare the Charges” for the footpath construction in Marshalltown Road, Marshall in accordance with the special charge scheme process.
Cr Richards moved, Cr Macdonald seconded -
That:
The following declaration of a special charge be confirmed:
A special charge be declared for a period until the works have been completed and the scheme finalised;
the special charge be declared for the purposes of defraying any expenses incurred by Council in relation to construction of footpath in Marshalltown Road, Marshall, south side from Barwarre Road to the railway line, which project:
will provide proper pedestrian access, improved nature strips and enhancement to the general amenity for each of the properties included in the scheme;
Council considers is or will be a special benefit to those persons required to pay the special charge (and who are described in succeeding parts of this Resolution); and
arises out of Council’s function of planning for and providing infrastructure for property owners.
The:
total cost of performing the function described in Part b of this Resolution based on estimated cost be recorded as $61,976
total amount of the special charge be levied and be recorded as $30,988.
it be recorded that, for the purposes of Section 163 (2A) of the Local Government Act 1989, the special charge proceeds will not exceed the amount calculated in accordance with the prescribed formula (R x C = S), the:
‘benefit ratio’ (R) being calculated at 100%, and representing the total benefits of the special charge scheme that will accrue as special benefits to all persons liable to pay the special charge; and
‘community benefit’ (C) being assessed as 50% in Marshalltown Road, Marshall.
the following be specified as the area for which the special rate is so declared:
the area within municipal district of Council highlighted in the Plan (Appendix 13-3) attached to this Resolution (“the area”).
the following be specified as the land in relation to which the special charge so declared:
all land within the area shown on the plan (Appendix 13-3).
the following be specified as the criteria which form the basis of the special charge so declared:
ownership of any land described in Part e of this Resolution.
the following be specified as the manner in which the special charge so declared will be assessed and levied:
the frontage of the lots abutting the works shall be used to calculate the individual cost to a lot;
in the case of unit development with common property fronting the works, the cost has been divided in accordance with the schedule of entitlements and liabilities shown on the plan of subdivision.
the special charge will be levied by sending a notice to the person who is liable to pay pursuant to section 163(A) of the Local Government Act
Having regard to the preceding parts of this Resolution but subject to Section 166 (1) of the Local Government Act 1989, it be recorded that subject to any further Resolution of Council, the special charge will be due and payable on the date(s) fixed under Section 167 of the Local Government Act 1989 as the date or dates on or by which Council’s general rates are due.
There are no incentives declared as incentives to be given by Council for the payment of the special rate before the date(s) specified for its payment under Section 167(3) of the Local Government Act 1989.
Council’s Chief Executive Officer be authorised to levy the Special Charge in accordance with Section 163(4) of the Local Government Act 1989.
Carried.
This project involves the proposed construction of footpath in Marshalltown Road, Marshall on the south side between Barwarre Road and the railway line. Footpath has generally been provided in the more recently developed areas of Marshall with a considerable amount of path in this area, however there are some missing links on the roads which have been laid out for some time.
The area is predominantly residential however there are focus points for pedestrians in the immediate area being the Primary School, a supermarket and the Railway Station. This project effectively fills in one of the missing links.
Council receives regular requests for footpath in this area.
Council Officers did attempt to complete this scheme by means of a negotiated up-front agreement, however this was not successful.
The scheme has been advertised and 3 objections were received. A copy of these objections has been circulated to Councillors, separately. Objections do not trigger a Submissions Panel Hearing, however must form a part of Council’s decision making process on the scheme. The three owners did not request to be heard.
Property owners receive benefit by way of improved pedestrian access, improved general amenity of the area and possible increase in property values.
Council policy provides for Council to meet 50% of the cost of footpath projects in recognition of the community benefit of the project, with abutting property owners meeting 50%.
It is proposed that the costs be apportioned to each property on the basis of frontage.
There are no environmental implications associated with this project.
Given approval of the scheme, it could be completed in this financial year.
The estimated cost of the project is $61,976, summary as follows:
|
Property owners 50% of works |
$30,988 |
|
Council 50% of works |
$30,988 |
|
Total |
$61,976 |
The scheme has been prepared in accordance with the Special Rate and Charge provisions of the Local Government Act along with Council’s Special Rates and Charges Policy.
There are no risks associated with Council proceeding to adopt the recommendation and advertise the scheme.
There are no risks associated with Council proceeding to adopt the recommendation and advertise the scheme.
Provision of a paved footpath will provide an important link and improved access for the local community, particularly for those that may suffer from a physical disability.
The scheme has been advertised and property owners given the opportunity to make submissions/objections.
The works for the construction of footpath in Marshalltown Road, Marshall which consist of excavation, footpath, reinstatement of nature strip, miscellaneous construction works, legal advice and professional services associated with survey, engineering design, drafting, supervision and administration of the project all as included in the cost estimate shown below.
Cost Estimate for Construction of Footpath
Marshalltown Road, Marshall
|
ITEM |
DESCRIPTION |
QUANTITY |
UNIT |
RATE $ |
AMOUNT $ |
|
1.00 |
Site establishment, set out and traffic control and setup
|
|
Item |
|
3,500 |
|
2.00 |
Excavation, trimming, supply and placement of bedding and formwork |
235 |
m |
15 |
3,525 |
|
3.00 |
Supply and place 75mm depth reinforced concrete footpath |
350 |
sqm |
110 |
38,500 |
|
4.00 |
Supply and place 125mm depth reinforced concrete driveways |
30 |
sqm |
120 |
3,600 |
|
5.00 |
Make good disturbed nature strips with 100mm depth approved loam and seed |
215 |
m |
5 |
1,075 |
|
Sub Total |
$50,200 |
||||
|
6.00 |
Contingency 10% |
$5,200 |
|||
|
7.00 |
Design and administration of Special Charge Scheme |
$6,576 |
|||
|
Total |
$61,976 |
||||
|
Council Proportion @ 50% Property owner proportion @ 50% |
$30,988 $30,988 |
||||
|
TOTAL |
$61,976 |
||||
Special Charge for Footpath Construction
Marshalltown Road, Marshall
|
|
COL 1 |
COL 2 |
COL 3 |
COL 4 |
|
|
PROPERTY DESCRIPTION |
TOTAL ESTIMATED |
PROPERTY |
PROPERTY DETAILS |
|
1 |
Lot 1 PS 607936 |
$2,462.19 |
340267 |
92 Marshalltown Road, Marshall |
|
2 |
Lot 5 PS 607936 |
$2,483.72 |
232642 |
90 Marshalltown Road, Marshall |
|
3 |
Lot 6 PS 607936 |
$5,991.90 |
340270 |
82-88 Marshalltown Road, Marshall |
|
4 |
Lot 1 PS 430881 |
$5,021.30 |
311585 |
78-80 Marshalltown Road, Marshall |
|
5 |
Lot 1 PS 635089 |
$1,453.89 |
343198 |
1/76 Marshalltown Road, Marshall |
|
6 |
Lot 2 PS 635089 |
$ 228.85 |
343199 |
2/76 Marshalltown Road, Marshall |
|
7 |
Lot 5 LP 220356 |
$3,365.48 |
232638 |
74 Marshalltown Road, Marshall |
|
8 |
Lot 1 PS 323268 |
$ 838.68 |
299141 |
1/70-72 Marshalltown Road, Marshall |
|
9 |
Lot 2 PS 323268 |
$ 838.68 |
299142 |
2/70-72 Marshalltown Road, Marshall |
|
10 |
Lot 3 PS 323268 |
$ 838.68 |
299143 |
3/70-72 Marshalltown Road, Marshall |
|
11 |
Lot 4 PS 323268 |
$ 838.68 |
299144 |
4/70-72 Marshalltown Road, Marshall |
|
12 |
Lot 1 PS 334008 |
$ 875.02 |
297802 |
1/68 Marshalltown Road, Marshall |
|
13 |
Lot 2 PS 334008 |
$ 875.02 |
298293 |
2/68 Marshalltown Road, Marshall |
|
14 |
Lot 1 PS 337788 |
$ 875.02 |
298414 |
1/66 Marshalltown Road, Marshall |
|
15 |
Lot 2 PS 337788 |
$ 875.02 |
298415 |
2/66 Marshalltown Road, Marshall |
|
16 |
Lot 1 LP 220356 |
$3,125.86 |
232626 |
64 Marshalltown Road, Marshall |
|
|
|
$30,988.00 |
|
|
Portfolio: |
Infrastructure - Cr Richards |
Source: |
City Services - Engineering Services |
General Manager: |
Gary Van Driel |
Index Reference: |
Subject: Special Rates and Charges - Reports |
This report relates to a proposed special charge scheme for construction of road pavement, kerb and channel and drainage in Wood Street, South Geelong between Barwon Terrace and Gravel Pits Road, as shown on Plan – Appendix 14-3.
This section of road has a partial seal with kerb and channel on the west side, at the Barwon Terrace end. The remainder is unsealed.
The area is heavy industrial with six property owners having frontage to this section of Wood Street.
The total cost of the project is $270,177, with owners responsible for $148,834 and Council contributing $121,283.
Owners costs vary between $10,105 and $67,684.
Council received 2 submissions and a Hearing Panel was convened. One attended and requested further information which was provided.
The scheme has been prepared in accordance with the special rate and charge provisions of the Local Government Act, along with Council’s Special Rates and Charges Policy.
This report seeks a resolution by Council to “Declare the Charges” for the kerb and channel and road pavement scheme in Wood Street, South Geelong in accordance with the Special Charge Scheme process as shown in the Process Charge.
Cr Richards moved, Cr Macdonald seconded -
That:
The following declaration of a special charge be confirmed:
A special charge be declared for a period until the works have been completed and the scheme finalised;
the special charge be declared for the purposes of defraying any expenses incurred by Council in relation to construction of kerb and channel and road pavement in Wood Street, South Geelong between Barwon Terrace and Gravel Pits Road which project:
will provide proper sealed road access, kerb & channel, improved nature strips and enhancement to the general amenity for each of the properties included in the scheme;
Council considers is or will be a special benefit to those persons required to pay the special charge (and who are described in succeeding parts of this Resolution); and
arises out of Council’s function of planning for and providing infrastructure for property owners.
The:
total cost of performing the function described in Part 1 (b) of this Resolution based on estimated cost, be recorded as $270,177.
total amount of the special charge to be levied, as based on estimated cost, be recorded as $148,834.
It be recorded that, for the purposes of Section 163 (2A) of the Local Government Act 1989, the special charge proceeds will not exceed the amount calculated in accordance with the prescribed formula (R x C = S), the:
‘benefit ratio’ (R) being calculated at 100%, and representing the total benefits of the special charge scheme that will accrue as special benefits to all persons liable to pay the special charge; and
‘community benefit’ (C) being assessed at zero for road pavement, kerb and channel and drainage in Wood Street, South Geelong.
The following be specified as the area for which the special rate is so declared:
the area within the municipal district of Council highlighted in the plan attached to this Resolution (“the area”).
The following be specified as the land in relation to which the special charge so declared:
all land within the area shown on the plan – Appendix 14-3.
The following be specified as the criteria which form the basis of the special charge so declared:
ownership of any land described in Part 1(e) of this Resolution.
the following be specified as the manner in which the special charge so declared will be assessed and levied:
the costs be apportioned as follows;
costs be allocated to the following properties on the basis of frontage:
9 Gravel Pits Road;
59-63 Wood Street;
65-69 Wood Street; and
11-13 Gravel Pits Road
costs to be allocated to the following properties on the basis of the cost of works applicable to the frontage of the properties:
86-90 Barwon Terrace; and
92-96 Barwon Terrace.
the special charge will be levied by sending a notice to the person who is liable to pay, pursuant to section 163(A) of the Local Government Act 1989.
Having regard to the preceding parts of this Resolution but subject to Section 166 (1) of the Local Government Act 1989, it be recorded that:
the owners of the land described in Column 1 of Schedule B to the resolution are estimated liable for the respective amounts set out in Column 2 of Schedule B; and
such owners may, subject to any further resolution of Council pay the special charge in the following manner:
The charge will become due and payable within one month of the issue of the notice requesting payment pursuant to Section 167 (3) of the Local Government Act 1989.
Interest will not be charged for six months after the issue of the notice provided the person liable makes timely payment in accordance with any repayment arrangements that may be agreed on by Council.
In accordance with Section 172 of the Act, the rate of interest which is payable on the Special Charge which has not been paid by the specified date is set at Council’s overdraft rate, reviewed every three months (provided that it shall not exceed the rate fixed by the Governor in Council by Order for the purposes of Section 172 (2A) in which case the rate of interest shall be the maximum rate fixed by the Governor in Council by Order for the purposes of this section).
There are no incentives declared as incentives to be given by Council for the payment of the special rate before the date(s) specified for its payment under Section 167(3) of the Local Government Act 1989.
Council’s Chief Executive Officer be authorised to levy the Special Charge in accordance with Section 163(4) of the Local Government Act 1989.
Carried.
This report relates to the proposed construction of Wood Street, South Geelong between Barwon Terrace and Gravel Pits Road. A section of this road is partially constructed on the side boundaries of the two properties fronting Barwon Terrace. The remainder is unconstructed.
Council has received enquiries from property owners regarding construction with dust an important issue. The area is industrial and the road caters for heavy traffic entering and exiting the properties. There are six properties involved in this scheme.
An intention to declare charges report was presented to Council on 28 June 2011. The scheme was subsequently advertised and 2 submissions received. One submitter agreed with the proposal and sought the provision of a driveway culvert for further access purposes. The second submitter questioned the extent of works and cost attributed to the property he was representing. Further information was subsequently supplied to this owners representative and no further response was forthcoming. The Panel considered that on provision of this information, the project should proceed.
Property owners receive benefit from the planned infrastructure as follows
proper sealed road access;
improved drainage;
removal of nuisance, dust and mud;
improvements to the general amenity of the area; and
likely increase in property values.
There are no Council properties in the scheme.
As part of the road is already constructed and the intention is to remove kerb & channel in poor condition and remove the section and reshape the pavement, this work will not be charged to owners.
This is based on the principle that owners are only charged for the “first up” infrastructure provision. This is the basis on which Council is making a contribution.
The summary of the estimated costs is as follows:
|
Owners Cost |
$148,834 |
|
Council Costs |
$121,283 |
|
Total |
$270,117 |
The costs have been apportioned to properties in a fair and equitable manner as follows:
|
Property |
Manner of apportionment |
|
86-90 Barwon Terrace 92-96 Barwon Terrace |
Actual cost of works across frontage calculated and attributed directly to each property. Council contribution for removal and replacement of existing infrastructure |
|
9 Gravel Pits Road 59-63 Wood Street 65-69 Wood Street 11-13 Gravel Pits Road |
Cost of works fronting all of these properties calculated then apportioned on a basis of frontage |
The road infrastructure proposed, provides proper sealed access, drainage and a generally safer environment.
During the course of construction and the manufacture and procurement of materials, there is expenditure of energy sources and greenhouse emissions. This does cease, however, when construction is complete.
The project does not create waste with the exception of some excess spoil.
The proposal does not affect any natural habitats.
The project has a one off capital cost as indicated above and there will be minimal ongoing maintenance costs. The scheme may proceed in the current financial year if approved.
The scheme has been prepared in accordance with the special rate and charge provisions of the Local Government Act along with Council’s Special Rates and Charges Policy. The project does not impinge on any Human Rights Charter issues.
There are no Council Officers involved in the administration or subsequent construction of the works, who have a direct or indirect interest in the project.
There are no risks associated with Council proceeding to adopt the recommendation and advertising the scheme.
There are no social considerations which may impact a Council’s decision to proceed to advertise the scheme.
The scheme has been advertised and owners given the opportunity to make submissions/objections.
The works for the construction of and kerb & channel and road pavement in Wood Street, South Geelong between Barwon Terrace and Gravel Pits Road which consist of excavation, reinstatement of nature strip, pavement works, kerb & channel, sealing, miscellaneous construction works, legal advice and professional services associated with survey, engineering design, drafting, supervision and administration of the project all as included in the cost estimate shown below.
|
ITEM |
DESCRIPTION |
QUANTITY |
UNIT |
RATE $ |
AMOUNT $ |
|
Section A – Owners |
|||||
|
1.00 |
Site establishment, set out and traffic control |
|
Item |
|
3,627 |
|
2.00 |
Earthworks |
|
|
|
|
|
2.01 |
Supply and place boxing |
83 |
m |
50 |
4,150 |
|
2.02 |
Grade table drain |
|
Item |
|
1,500 |
|
3.00 |
Pavement works |
|
|
|
|
|
3.01 |
200mm compacted depth of class 2 20mm FCR pavement |
284 |
cm |
120 |
34,084 |
|
3.02 |
Primerseal 7mm |
1,023 |
sqm |
4 |
4,092 |
|
3.03 |
Final seal 14mm |
1,023 |
sqm |
4.5 |
4,604 |
|
Sub Total |
$52,057 |
||||
|
4.00 |
Contingency 10% |
|
5,206 |
||
|
5.00 |
Design and Administration of Special Charge Scheme |
6,820 |
|||
|
Total |
$64,083 |
||||
|
ITEM |
DESCRIPTION |
QUANTITY |
UNIT |
RATE $ |
AMOUNT $ |
|
Section B (i) - Owner |
|||||
|
1.00 |
Site establishment, set out and traffic control |
|
Item |
|
3,836 |
|
2.00 |
Earthworks |
|
|
|
|
|
2.10 |
Excavation and disposal of material |
100 |
cm |
50 |
5,000 |
|
2.30 |
Supply and place boxing |
8.5 |
cm |
50 |
425 |
|
3.00 |
Pavement |
|
|
|
|
|
3.10 |
200mm compacted depth of class 2 20mm FCR pavement |
30 |
cm |
120 |
3,600 |
|
3.20 |
410 mm compacted depth of class 2 FCR in widening trench |
85 |
cm |
130 |
11,050 |
|
3.30 |
50 mm compacted depth 10mm nom size type N asphalt with geofabric reinforcing layer |
200 |
sqm |
30 |
6,000 |
|
3.40 |
Primerseal 7mm |
108.5 |
sqm |
4 |
434 |
|
3.50 |
Final seal 14mm |
108.5 |
sqm |
4.5 |
488 |
|
4.00 |
Concrete Works |
|
|
|
|
|
4.10 |
Supply and place B2 kerb and channel, including excavation and bedding |
150 |
m |
70 |
10,500 |
|
4.20 |
Supply and place concrete driveways |
30 |
sqm |
150 |
4,500 |
|
5.00 |
Drainage |
|
|
|
|
|
5.10 |
Supply and place 90mm sub soil drains |
150 |
m |
22 |
3,300 |
|
5.20 |
Supply and place 300mm dia RC pipe |
6 |
m |
200 |
1,200 |
|
5.30 |
Construct 900mm * 600mm SEP less than 1.5m deep |
3 |
NO |
750 |
2,250 |
|
6.00 |
Landscaping |
|
|
|
|
|
6.10 |
Topsoil and seed nature strips |
300 |
sqm |
8 |
2,400 |
|
7.00 |
Subtotal |
54,983 |
|||
|
8.00 |
Contingency 10% |
5,498 |
|||
|
9.00 |
Design and Administration of Special Charge Scheme |
7,203 |
|||
|
Total |
$67,684 |
||||
|
ITEM |
DESCRIPTION |
QUANTITY |
UNIT |
RATE $ |
AMOUNT $ |
|
Section B (ii) - Owner |
|||||
|
1.00 |
Site establishment, set out and traffic control |
Item |
|
|
966 |
|
2.00 |
Earthworks |
|
|
|
|
|
2.10 |
Supply and place boxing |
8.5 |
cm |
50 |
425 |
|
3.00 |
Pavement |
|
|
|
|
|
3.10 |
200mm compacted depth of class 2 20mm FCR pavement |
30 |
cm |
120 |
3,600 |
|
3.20 |
Primerseal 7mm |
108.5 |
sqm |
4 |
434 |
|
3.30 |
Final seal 14mm |
108.5 |
sqm |
4.5 |
488 |
|
4.00 |
Concrete Works |
|
|
|
|
|
4.10 |
Supply and place concrete driveways |
30 |
sqm |
150 |
4,500 |
|
5.00 |
Drainage |
|
|
|
|
|
5.10 |
Supply and place 300mm dia RC pipe |
6 |
m |
200 |
1,200 |
|
5.20 |
Construct 900mm x 600mm SEP less than 1.5m deep |
3 |
No |
750 |
2,250 |
|
|
Subtotal |
|
|
|
13,865 |
|
6.00 |
Contingency 10% |
|
|
|
1,386 |
|
7.00 |
Design and Administration of Special Charge Scheme |
|
|
|
1,816 |
|
|
Total |
|
|
|
17,067 |
|
ITEM |
DESCRIPTION |
QUANTITY |
UNIT |
RATE $ |
AMOUNT $ |
|
Council Costs |
|||||
|
1.00 |
Site establishment, set out and traffic control |
ITEM
|
|
|
6,874 |
|
2.00 |
Earthworks |
|
|
|
|
|
2.1 |
Demolish and dispose of existing kerb and channel |
145 |
m |
30 |
4,350 |
|
2.2 |
Strip and dispose existing seal |
75 |
cm |
30 |
2,250 |
|
2.3 |
Sawcut concrete and seal |
40 |
cm |
50 |
2,000 |
|
3.00 |
Pavement |
|
|
|
|
|
3.1 |
Re sheet existing pavement with 100mm nom depth class 2 FCR |
175 |
cm |
120 |
21,000 |
|
3.2 |
50mm compacted depth 10mm nom size type N asphalt with geofabric |
1,395 |
sqm |
30 |
41,850 |
|
4.00 |
Concrete Works |
|
|
|
|
|
4.1 |
Supply and place B2 kerb and channel, including excavation and bedding |
150 |
m |
70 |
10,500 |
|
5.00 |
Drainage |
|
|
|
|
|
5.1 |
Supply and place 90mm sub soil drains |
150 |
m |
22 |
3,300 |
|
5.2 |
Modify existing pit to match finished surface and supply gatic type lid |
4 |
No |
1,000 |
4,000 |
|
6.00 |
Landscaping |
|
|
|
|
|
6.1 |
Topsoil and seed nature strips |
300 |
sqm |
8 |
2,400 |
|
7.00 |
Sub Total |
|
|
|
98,524 |
|
8.00 |
Contingency 10% |
|
|
|
9,852 |
|
9.00 |
Design and Administration of Special Charge Scheme |
|
|
|
12,907 |
|
|
Total |
|
|
|
$121,283 |
|
COL 1 |
COL 2 |
COL 3 |
COL 4 |
|
DESCRIPTION OF PROPERTY |
ESTIMATED COST ($) |
PROPERTY REFERENCE |
PROPERTY DETAILS |
|
CA 3 Sec 11A |
$17,067 |
212025 |
86 |
Barwon Terrace |
South Geelong |
|
CA 20 Sec 11A |
$31,298 |
214037 |
9 |
Gravel Pits Road |
South Geelong |
|
TP 819057 |
$67,684 |
212028 |
92 |
Barwon Terrace |
South Geelong |
|
Lot 3 PS 446573 |
$10,105 |
315017 |
59 |
Wood Street |
South Geelong |
|
Lot 2 PS 446573 |
$10,105 |
315016 |
65 |
Wood Street |
South Geelong |
|
Lot 1 PS 446573 |
$12,576 |
315015 |
11 |
Gravel Pits Road |
South Geelong |
|
Total |
148,834 |
|
|
|
|
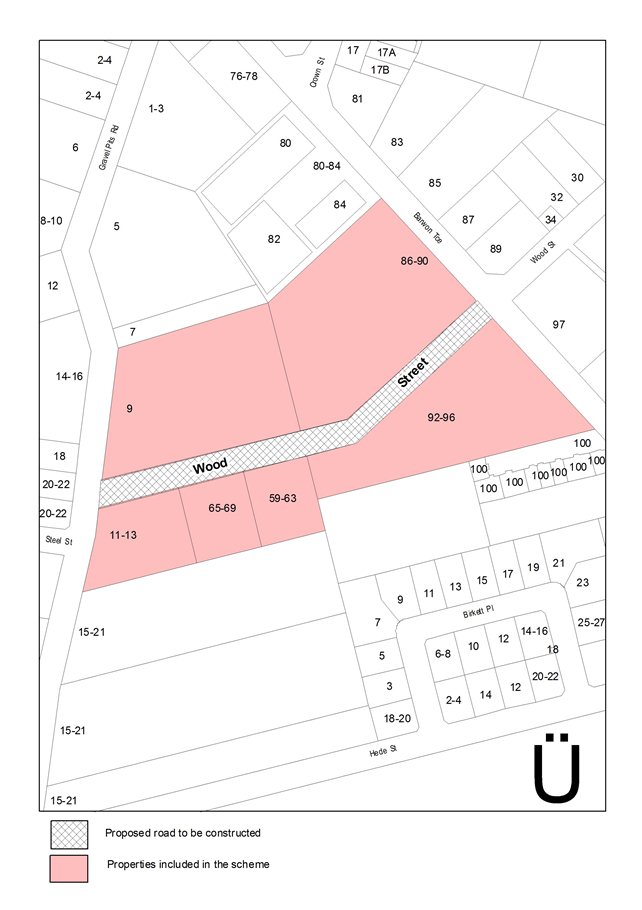
Portfolio: |
Community Development – Cr Fisher |
Source: |
Projects, Recreation & Central Geelong |
General Manager: |
Dean Frost |
Index Reference: |
T1200185 |
CoGG ran a select tender choosing six suppliers from the Department of Transport’s Construction Supplier Register. The Construction Supplier Register is a pre-qualification scheme for building and construction industry consultants and contractors available for use by approved Government and non-Government organisations. The suppliers selected were all pre-qualified capable of delivering new commercial construction for a project of this scale.
Following a detailed assessment of each of the submissions the Evaluation Panel recommend that E.J. Lyons & Sons Pty Ltd be awarded the contract.
Council has achieved a favourable tender result due to depressed market conditions currently being experienced in the building industry for projects of this scale. It is expected that a moderate project saving will now be achieved.
Cr Farrell moved, Cr Fisher seconded -
That Council:
accept the tender submission from E.J. Lyons & Sons Pty Ltd for the lump sum amount of $6,258,840 exclusive of GST;
sign and seal the contract documents.
Carried.
Tenders were invited through Tenderlink on Friday 20 July 2012.
At the close of tenders on the 15th August 2012 the following tender submissions were received:
|
Tenderer |
|
E.J. Lyons & Sons Pty Ltd |
|
Rendine Constructions Pty Ltd |
|
Walton Construction Pty Ltd |
|
Ireland Brown Pty Ltd |
|
BDH Constructions Pty Ltd |
|
Devco Project & Construction Management Pty Ltd |
The tenders were evaluated by a panel consisting of:
|
Panel Member |
Title |
|
Dean Frost |
General Manager Projects, Recreation & Central Geelong |
|
Frank Giggins |
Co-ordinator Family Services Development |
|
David Ash |
Senior Capital Projects Officer |
|
Scott Cavanagh |
Manager Capital Projects |
|
Peter Walker |
Senior Contracts Officer (Advisor) |
|
Brett Gilliland |
Contracts Officer (Advisor) |
|
Mark Anderson |
Senior Associate, Slattery Australia (Technical Advisor) |
|
Ian Perkins |
Principal, Perkins Architects (Technical Advisor) |
Stage One – Mandatory Criteria
The Mandatory requirements that apply to this Tender are:
|
Tenderers must comply with OH&S requirements detailed in the Tender Schedule. |
All submissions complied with the mandatory criteria and proceeded to the second stage of evaluation.
Stage Two –Comparative Criteria
Tender submissions were assessed based on the respondent’s performance or tender response in the following areas:
|
Criteria |
Weighting |
|
Price |
50% |
|
Capability & Experience / Past Performance |
15% |
|
Economic Contribution to Geelong Region |
5% |
|
Methodology/plan for performing contract (including Timelines, Staffing, Plant, Subcontracting) |
20% |
|
Flexibility and responsiveness (ability to meet CoGG timeframes) |
5% |
|
Quality Management & Environmental Systems |
5% |
|
|
100% |
At the conclusion of the evaluation the tenderers were ranked in the following order:
|
Tenderer |
Rank |
|
E.J. Lyons & Sons Pty Ltd |
1 |
|
Ireland Brown Pty Ltd |
2 |
|
Walton Construction Pty Ltd |
3 |
|
Rendine Constructions Pty Ltd |
4 |
|
BDH Constructions Pty Ltd |
5 |
|
Devco Project & Construction Management Pty Ltd |
6 |
Preferred Supplier
The Evaluation Panel assessed submissions using Council’s standard evaluation methodology. With the application of the equivalency rule* E.J. Lyons & Sons Pty Ltd (t/a Lyons Construction) were selected as the preferred supplier.
Lyons Construction provided the lowest tendered price and scored highly against all the comparative criteria demonstrating to the Evaluation Panel that they have the capability to successfully deliver a value for money outcome. Their works schedule stated a practical completion date of 29 November 2013 in line with Council requirements.
Lyons Construction has operated in Geelong for 83 years, recently receiving the regional builder of the year award. They demonstrated their capability and experience through their extensive list of projects ranging in price from $700k up to $7 million including the Waurn Ponds Library ($3.5 million) and the Bellarine Aquatic Centre ($6.9 million) which they successfully delivered for the City of Greater Geelong.
Lyons Construction being Geelong based source the majority of their materials locally while employing local subcontractors as required. They offer an experienced workforce and have a proven track record with Council regarding OH&S compliance.
*The Equivalency Rule states that if the lowest value tender falls within two points of the highest Final Score then that tender is to be recommended. The Equivalency Rule applies to all tender evaluations.
Overview of Unsuccessful Tenders
Ireland Brown demonstrated that they have the capability to deliver the works submitting a technically acceptable submission. They rated highly for their extensive list of past projects providing examples of their work at the Avondale Heights Community Centre ($3.6 million) and the Clare Court Children’s Centre in Yarraville ($3.5 million). They submitted a detailed project timeline and provided evidence of their certified quality, environmental and OH&S systems.
Walton Construction scored highly for their staffing, equipment and experience with an extensive list of completed construction projects ranging in price from $3 million to $50 million (although no relevant childcare projects were listed). They operate quality, environmental and OH&S systems that have been independently audited and certified. Their final score was adversely impacted by their quoted price which was the most expensive of the tenders received.
Rendine Constructions provided a list of previous projects, including the $5.3 million Old Geelong Courthouse Projects. They have a proven OH&S record on Council projects, are ISO 9001 certified for their quality systems and as a Geelong based supplier were able to demonstrate a direct economic contribution to the Geelong Region.
BDH listed their previous contracts which ranged in value from $500k to $13 million (predominantly in the education sphere). BDH operate an Office in Geelong and intend to source all of the materials locally while engaging local subcontractors to perform the works as required. BDH did not submit a project plan/methodology as requested.
Devco demonstrated experience working on a variety of construction projects up to $22 million including the Phoenix Park Children's Centre ($3.4 million), the Wyndham Vale Community Centre & Library ($6 million) and the Crown Street Community Hub ($8 million). However they did not submit a methodology for performing the contract and their submission was lacking in a number of key areas.
Any environmental implications associated with this contract will arise from the execution of the civil works. It is considered that these are the responsibility of the Contractor and will be managed through the contract documentation.
The Evaluation Panel acknowledge that the tendered prices were on average 10% lower than anticipated which can largely be attributed to the present depressed state of the construction industry.
Council had been advised prior to tender that recent tenders for projects in this range were coming in at between 5% and 10% below pre tender estimates.
These lower than expected prices will provide Council with modest cost savings on the construction component of the project. This is a marked change from councils experience over recent years when we were tendering in more buoyant market conditions.
The requirements of Section 186 of the Local Government Act have been complied with for this tender. There are no other policy, legal or statutory implications associated with this tender process.
No officers or contractors involved in the preparation of this report have a direct or indirect interest in matters to which this report relates.
There are not considered to be any risks associated with the acceptance of this tender that cannot be managed through the contract conditions.
There are no social implications that will arise from the acceptance of this tender.
There are no communication issues associated with the acceptance of this tender. Council’s representative will liaise with affected community groups.
Contents | Previous Page: Section B - Reports (1-8) | Next Page: Section C - Urgent Business
